

🧨 Are Credit Card Points at Risk?
The Hidden Law That Could Wipe Out Rewards
If you’ve built your lifestyle or travel strategy around credit card points, cashback, or premium perks — you need to pay attention. A legislative push happening right now in Washington could quietly dismantle the entire rewards ecosystem.
A bill called the Credit Card Competition Act (CCCA) is back — and this time, it was nearly added as a last-minute amendment to the bipartisan GENIUS Act, a popular tech-focused bill. While the CCCA didn’t make it in (yet), the fact that it got this close has set off alarms among banks, airlines, and rewards enthusiasts.
On the surface, the CCCA aims to lower costs for merchants.
But behind the scenes? It could mean the end of points, miles, and perks as we know them.
Let’s break it down in plain English — what this bill does, what’s at stake, and what you can do.
🏛️ What Is the Credit Card Competition Act (CCCA)?
The CCCA is a bipartisan proposal from Senators Durbin (D-IL) and Marshall (R-KS) aimed at increasing competition in credit card processing.
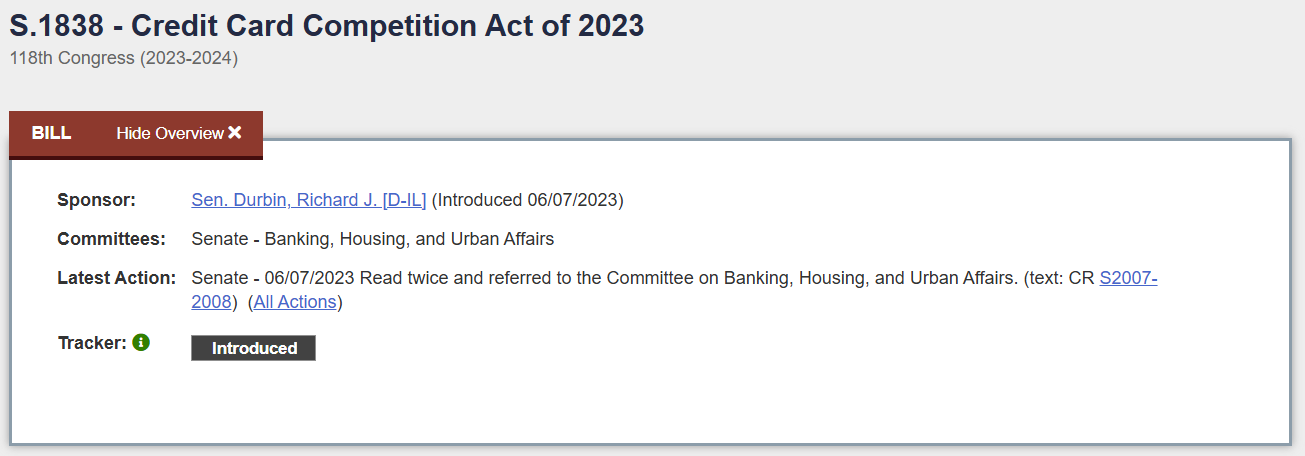
Today, most major credit cards operate on either Visa or Mastercard networks — and banks choose which one to use. The CCCA would require large banks (those with over $100B in assets) to enable at least two unaffiliated payment networks on each card.
In practice, this means merchants — not banks or consumers — would decide which network processes your payment.
And here’s the catch: they’ll almost always choose the cheapest one.
💸 Why That Could Kill Credit Card Rewards
Swipe fees — the charges merchants pay when you use a credit card — fund the entire credit card rewards ecosystem. These fees typically range from 1.5% to 3%, and they help pay for:
Points & miles
Cashback rewards
Sign-up bonuses
Travel protections
Fraud detection systems
Premium benefits (like lounge access or insurance)
If the CCCA passes, it could divert transactions to low-cost networks that don’t support these features — meaning banks make less on every swipe.
Less revenue = fewer rewards.
It’s not hard to imagine the ripple effect:
🔻 Smaller sign-up bonuses
⚠️ Fewer transfer partners
💳 Lower earning rates
🧾 Reduced purchase protections
❌ Premium cards (like the Amex Platinum or Chase Sapphire Reserve) potentially not sustainable
🧩 Where the GENIUS Act Comes In
The GENIUS Act is a bipartisan bill focused on regulating stablecoins and digital assets. It has broad support and is seen as a landmark piece of fintech legislation.
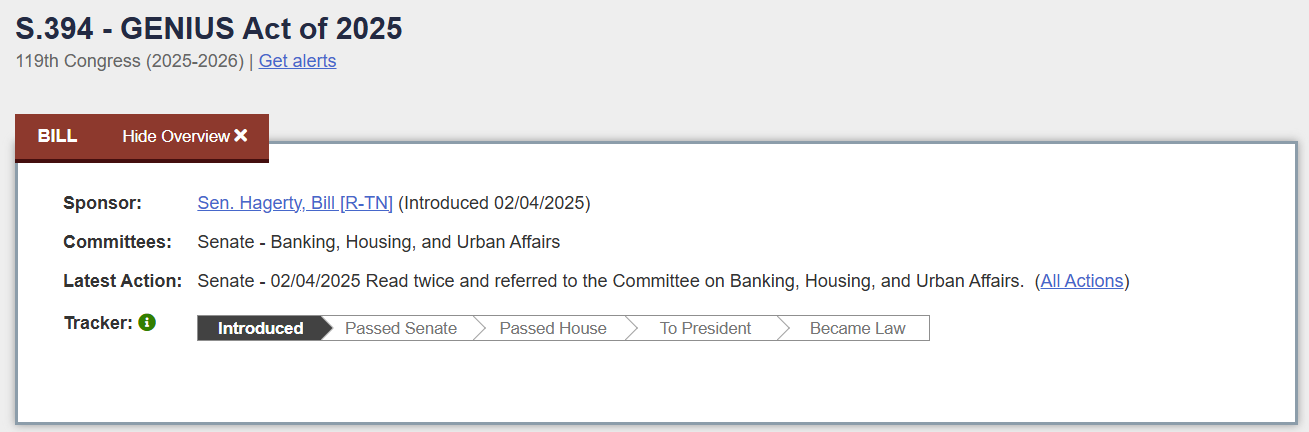
Recently, some lawmakers tried to attach the CCCA as a hidden amendment to the GENIUS Act — a move that would’ve allowed it to pass with little debate.
That effort failed (for now). A coalition of airlines, travel companies, banks, and consumer advocates pushed back, calling the CCCA a “poison pill” that could derail the GENIUS Act entirely.
But don’t relax just yet — backers of the CCCA have made it clear they plan to try again, possibly on a future spending or defense bill.
😡 Who’s Opposed — and Why
This isn’t just about protecting banks.
Opposition to the CCCA includes:
✈️ Airlines & Hotels — like Delta, United, Marriott, and Hyatt
🏦 Banks — like Chase, Amex, and Citi
🎯 Consumers & Points Experts — who warn that rewards could be gutted
🛡️ Fraud Prevention Advocates — who argue cheaper networks may lack strong protections
Even some critics of big banks admit: while merchants may save money, there’s no guarantee they’ll pass those savings on to consumers. In fact, many worry the CCCA would:
Transfer power from consumers to retailers
Eliminate choice and value for cardholders
Hurt low-income users who rely on cashback cards the most
🛑 What Happens If It Passes?
If the CCCA becomes law, the consequences could include:
🔻 Reduced Rewards — Smaller bonuses, lower earning rates, fewer transfer partners
❌ Elimination of Premium Perks — Lounges, statement credits, and protections may disappear
🚫 Collapse of Co-Branded Cards — Banks and brands may scale back or end partnerships
📉 Fewer New Products — Banks may avoid launching new reward cards if they’re no longer profitable
In short, we could be looking at the end of the golden age of rewards.
💬 What Can You Do?
As of today, the CCCA has not passed — and it’s not attached to the GENIUS Act. But the threat remains, especially if lawmakers try to slip it into other bills later this year.
If you value your rewards:
✅ Contact your representatives — Let them know you oppose the CCCA.
✅ Support advocacy groups — Like Hands Off My Rewards and others fighting this bill.
✅ Use your points wisely — Earn, burn, and diversify your strategy before the landscape shifts.
💭 Final Thoughts
Credit card rewards aren’t just a luxury — for millions, they’re a practical financial tool.
They make travel more affordable, offer fraud protection, provide emergency benefits, and help make life a bit more flexible. The CCCA may be well-intentioned, but its consequences could quietly erase all of that — especially if it’s passed without a full public debate.
Stay alert. Stay vocal. And make the most of your rewards while the system still works.
⚡ TL;DR — What You Need to Know
🏛️ The Credit Card Competition Act would force banks to enable low-cost processing networks.
💸 That means fewer swipe fees — and fewer rewards.
❌ If passed, perks like points, miles, lounges, and protections could disappear.
🧠 Lawmakers tried to attach the bill to the bipartisan GENIUS Act — but failed (for now).
📣 Take action: Contact your reps, follow the news, and use your points while you can.