

In the first quarter of 2025, NVIDIA’s stock price experienced a significant correction. Let’s analyze the financial indicators that influenced this situation and why investors reacted the way they did.
Financial Results
The company demonstrated an impressive revenue growth of 78%, reaching $39.3 billion.
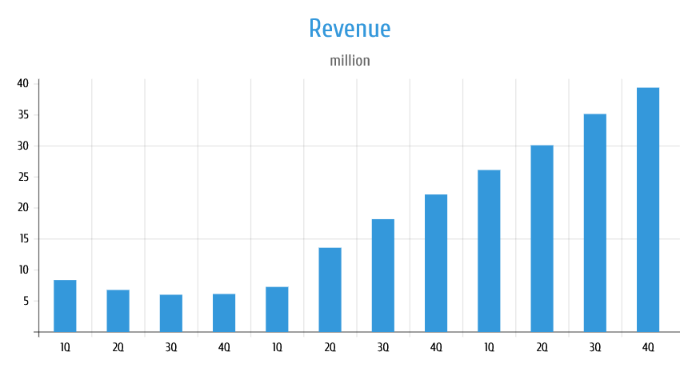
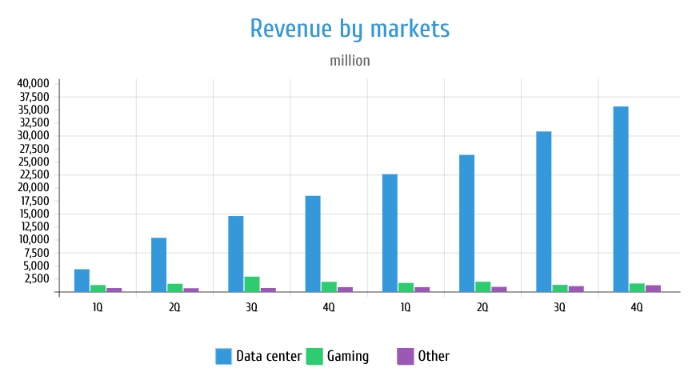
The data center division stood out in particular.
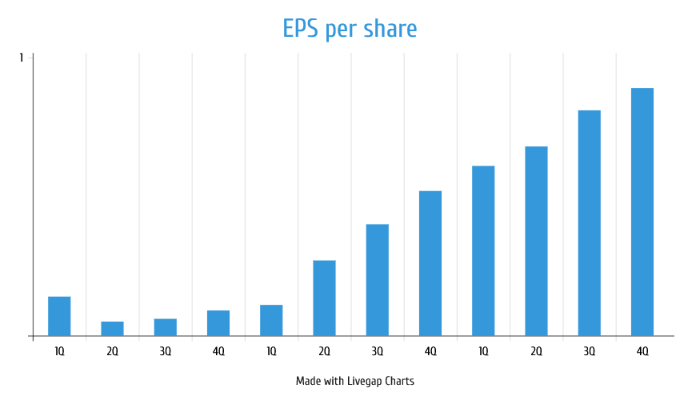
At the same time, NVIDIA’s operating margin remains at a high level—over 70%. This indicates the company’s strong business efficiency.
The primary driver of growth was the data center segment. In 2023, revenue from this sector was only $3.6 billion, whereas in 2025, it soared to $35.5 billion. This segment remains NVIDIA’s key source of income.
However, despite these impressive results, the company’s stock dropped by 8.5% after the earnings report. Why did this happen? Let’s examine the reasons.
Reasons for the Price Correction
1. High Analyst Expectations
Market analysts expected even better results than those reported. As a result, when the company failed to meet the overly optimistic forecasts, the market reacted with a decline in stock value.
2. High Valuation
NVIDIA’s market capitalization reached $2.8 trillion, making it one of the largest companies in the world. However, such a high valuation raises concerns among investors about the company’s future growth potential.
The price-to-earnings (P/E) ratio stood at 39.1, which is also a high figure.
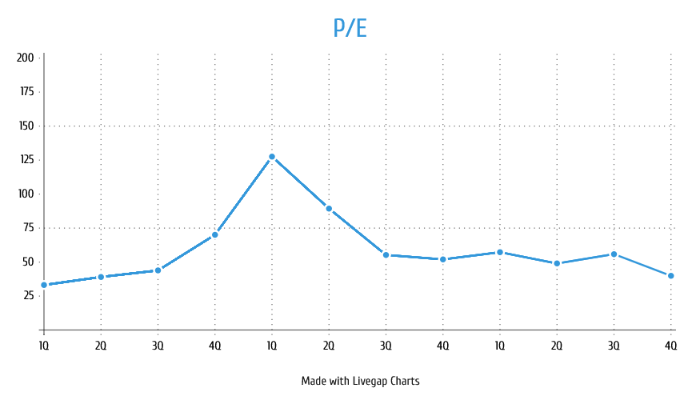
Although this level is not excessively expensive for a high-tech company, many investors believe that future growth may slow down.
Future Demand Risks
There is a possibility that peak demand for NVIDIA’s products, especially AI chips, will be reached by 2026. After that, maintaining current production volumes will become the company’s top priority. Investors fear that periodic product updates may be less profitable than creating entirely new solutions.
Investment Strategy
Despite the risks, NVIDIA remains an attractive company for long-term investments. If you plan to build a diversified investment portfolio, purchasing NVIDIA shares during the current correction may be a profitable strategy.
New Technologies
One of the key factors behind NVIDIA’s success is the introduction of the new Blackwell graphics processor, which generated record quarterly revenue of $11 billion. This technology delivers a 100-fold increase in computing power.
Moreover, the company is preparing to unveil new chips—Blackwell Ultra and Rubin—which promise to usher in a new era in AI technology development.
External risk factors
The U.S. President announced new tariffs on China, Canada, and Mexico. These measures could lead to import duties on NVIDIA’s Asian-manufactured chips, negatively impacting the company’s global sales.
Thus, while NVIDIA’s prospects remain positive, investors should consider potential risks associated with global trade policies and changes in product demand.
Become a member to receive more useful information. Thank you to everyone who shared the post on social media.
It is not an investment recommendation. Consult with a financial advisor before making investment decisions