

Let's examine the report of JD.com, the largest Chinese online retailer. Unlike its main competitor, Alibaba, JD.com purchases goods directly from manufacturers and sells them through its own platform.
Financial results
The fourth quarter brought good news—revenue increased by 14%.
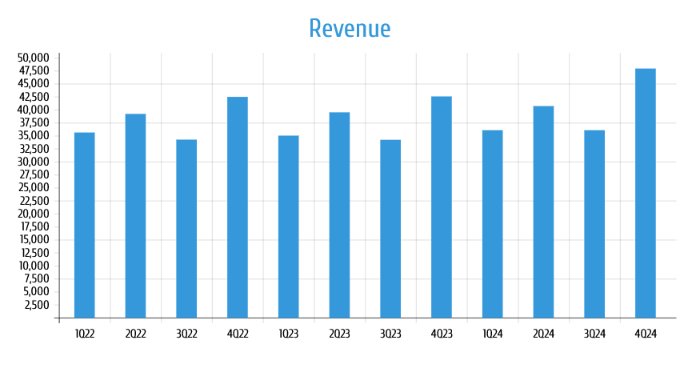
The annual growth dynamics are also impressive: the total increase amounted to 13%. Notably, after a decline in 2020-2021, the company is showing a confident acceleration in revenue growth.
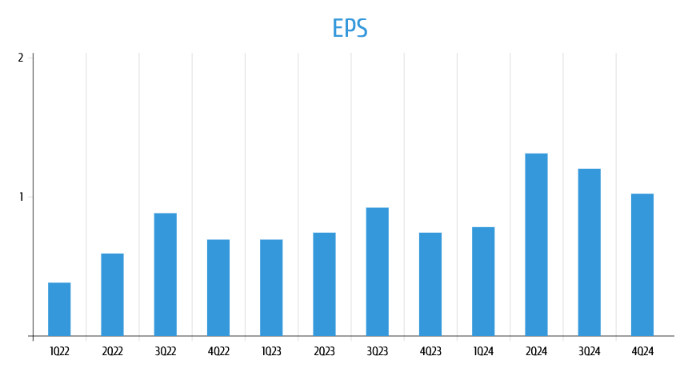
Earnings per ADR increased to 1.02, significantly exceeding last year's level of 0.74.
Management announced a dividend payout of $1 per ADR. Additionally, the company plans to allocate 20% of its net profit for dividend payments, while using the remaining portion for a share buyback program. This means that shareholders will benefit not only from dividends but also from the appreciation of the remaining shares due to the buyback.
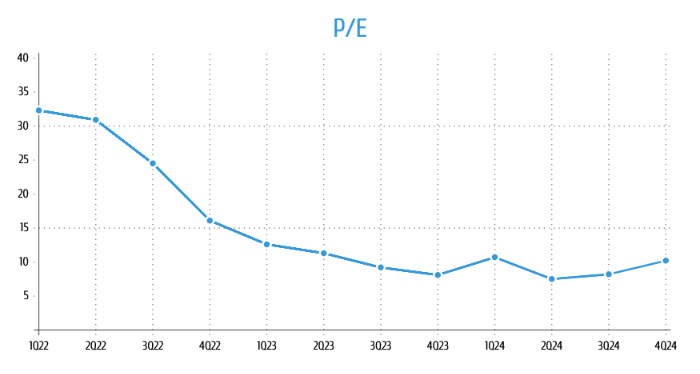
The P/E ratio stands at 10.2, making JD.com shares attractive to investors, especially in comparison with competitors like Alibaba, where this figure is 17.
Business segments
JD Retail: The primary source of the company's revenue, showing a 15% growth.
Logistics segment: Grew by 10%, indicating the stable operation of the company’s logistics infrastructure.
New business initiatives: Despite a negative dynamic (-31%), management continues to develop these areas, seeing long-term potential.
Net profit margin increased from 2.7% to 3.3%, demonstrating the company’s successful efforts in cost optimization and operational efficiency improvement.
Free cash flow (FCF) increased to 43.7 billion yuan compared to 40.7 billion the previous year. The company consistently expands its free cash flow volume, ensuring flexibility in implementing strategic initiatives.
Prospects and risks
Consumer demand: A key success factor for JD.com is the recovery of consumer activity in China. After a two-year crisis in the real estate sector, Chinese consumers have begun to spend actively again. If this trend continues, further revenue growth can be expected.
Risk factors: The main risks include potential deterioration of China-US relations and general economic challenges. These factors may put pressure on stock prices, but the company has already demonstrated its ability to adapt to a challenging market environment.
Become a member to receive more useful information. Thank you to everyone who shared the post on social media.
It is not an investment recommendation. Consult with a financial advisor before making investment decisions