
بِسْمِ اللهِ الرَّحْمٰنِ الرَّحِيْم.
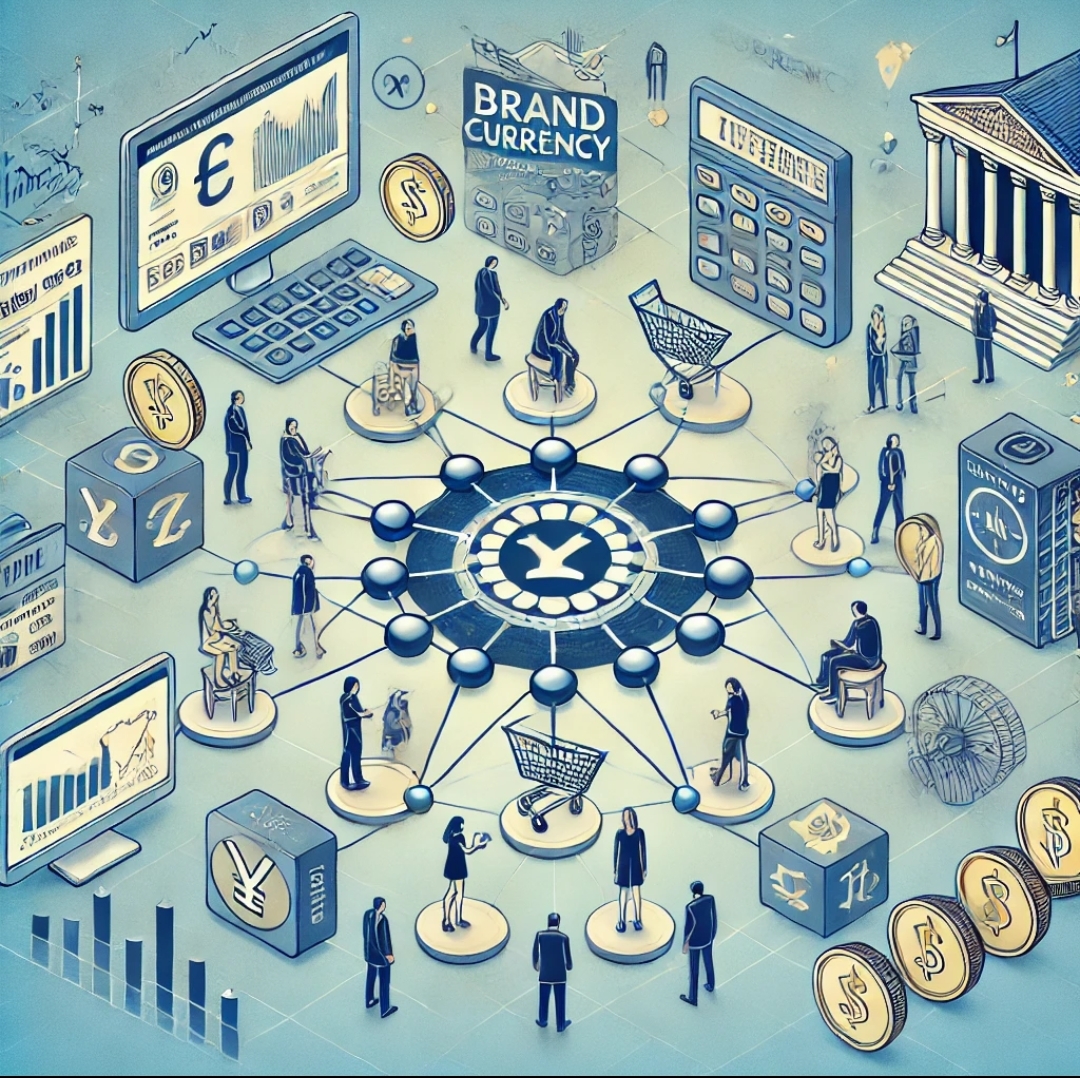
The Brand Currency System will fundamentally shift the way global economies operate by placing individuals at the center of the economy. With every sale, a digital coupon will be attached, which is held by the central bank. Unlike traditional currency, these coupons will not carry the risk associated with central banks because they won’t be issued by the banks themselves. Instead, they will serve as tools for businesses and individuals to interact, creating an economy that prioritizes people’s transactions and value.
This system will require the central bank’s involvement because, just like today, the central bank plays a vital role in regulating the economy. However, the central bank does more than just raise interest rates or inject liquidity into the market—something many people don't understand. The central bank uses several tools to manage inflation, regulate the money supply, and ensure the economy remains stable.
The truth is, the Federal Reserve and other central banks don’t have all the answers. They use the tools they have, and as new economic problems arise, they must develop new tools to address them. This essay will break down the key tools the Fed uses, when they were developed, and how they function, followed by an exploration of how the Brand Currency System can replace or complement these mechanisms for a more innovative approach to economic management.
Federal Reserve Tools: A Historical Overview
1. Manipulating Interest Rates: The Federal Funds Rate
When Developed: The Federal Funds Rate has been a critical part of U.S. monetary policy since the creation of the Federal Reserve in 1913. However, it became more prominent in the 1950s and 1960s as the Fed's primary tool for controlling inflation and regulating economic growth.
How It Works: The Federal Funds Rate is the interest rate banks charge each other for overnight loans. By raising or lowering this rate, the Fed can control the cost of borrowing across the economy. Lowering the rate encourages borrowing, boosts spending, and stimulates growth, while raising it has the opposite effect—it cools down inflation and limits spending.
2. Open Market Operations (OMO)
When Developed: Open Market Operations were officially formalized as a tool in 1923, but the practice of using government securities to regulate liquidity in the banking system dates back to the early 1900s.
How It Works: In open market operations, the Fed buys or sells government bonds. When it buys bonds, it injects liquidity into the system, lowering interest rates and increasing the money supply. When it sells bonds, it reduces liquidity, raising rates and pulling money out of circulation.
Historical Use: OMO became especially important after World War II when the Fed sought to manage inflation in a growing post-war economy.
3. Discount Rate
When Developed: The discount rate has been a tool since the Federal Reserve’s inception in 1913.
How It Works: This is the interest rate at which commercial banks can borrow money directly from the Federal Reserve. By lowering the discount rate, the Fed encourages banks to borrow more, which increases the money supply. Conversely, raising the rate discourages borrowing and reduces the money supply.
4. Reserve Requirements
When Developed: Reserve requirements have been in place since the founding of the Federal Reserve, but they were adjusted significantly after the 2008 financial crisis under the BASEL III regulations.
How It Works: Reserve requirements refer to the amount of money commercial banks must hold in reserve relative to their deposits. By increasing the reserve requirements, the Fed can reduce the amount of money available for banks to lend, decreasing the money supply. Lowering it increases lending and the money supply.
5. Quantitative Easing (QE)
When Developed: Introduced in the wake of the 2008 financial crisis, quantitative easing was an unconventional tool designed to stimulate the economy when interest rates were already near zero.
How It Works: QE involves the Fed buying long-term securities, such as Treasury bonds and mortgage-backed securities, to inject liquidity into the market. By doing so, the Fed lowers long-term interest rates, increases the money supply, and encourages investment and spending.
The Limitations of These Tools
While these tools have been effective in managing economic crises, they can often be described as broad "radiation treatments"—they affect the entire economy but do not always address specific underlying issues. For example, raising interest rates to combat inflation can have widespread consequences, slowing down borrowing and spending across all sectors, even those not directly contributing to inflation.
Moreover, tools like quantitative easing have faced criticism for exacerbating income inequality, as they primarily benefit those who hold assets like stocks and bonds.
The Brand Currency System: A More Surgical Approach
This is where the Brand Currency System comes in, offering a more targeted, precise approach to managing the economy. Instead of relying on broad measures like interest rates and bond purchases, the Brand Currency System introduces coupons that are tied directly to transactions. These coupons would act as microeconomic tools to regulate specific parts of the economy without requiring broad-based interventions that might have unintended side effects.
By attaching digital coupons to every sale, individuals are empowered to rate and engage with businesses directly. These ratings and transactions can be used to create real-time data on economic activity, allowing central banks to identify specific areas of the economy that are underperforming or need support. Unlike traditional monetary policy, which often relies on outdated or generalized data, this system would provide a continuous flow of information that reflects the actual state of the economy.
Additionally, this system would focus on value creation, where an individual’s contribution to the economy is more than just their ability to consume. Instead, their transaction network—family, community, and professional connections—are integrated into a collective system that amplifies their economic power. In this way, the Brand Currency System creates a more predictable, stable, and dynamic economic framework.
Conclusion: Redefining the Future of Central Banking
The most important lesson is that central banks, including the Federal Reserve, must constantly evolve. Their current tools, though effective in certain situations, are limited in their scope and impact. By adopting systems like the Brand Currency System, central banks can move beyond interest rate adjustments and quantitative easing and embrace a more nuanced, data-driven approach to economic management.
The world needs a system that recognizes the power of individual transactions, prioritizes value creation, and promotes fairness in the economy. The Brand Currency System offers that future—a future where central banks can move from reactive to proactive, from radiation treatments to precise, targeted interventions that support the economy's long-term health.
This system will be the next evolution in
central banking, where the power truly rests in the hands of the people.