
“After investigating hundreds of these operations, I’ve learned one thing: scammers don’t need smarter victims. They need governments, banks and technology companies that are slower than they are.”
For the last few years, I have watched an extraordinary industry grow around stealing money from ordinary people.
I have sat through the Zoom presentations, infiltrated the Telegram and WhatsApp groups, interviewed victims, challenged promoters, examined corporate records and worked alongside investigators following cryptocurrency across the blockchain. Some operations collapsed while I was investigating them. Others rebranded and carried on. Some attracted regulatory action, while a handful eventually ended with people facing criminal charges.
And still they keep coming.
That is why a new 37-page Mid-Year Scam and Cybercrime Brief from the Singapore Police Force caught my attention. Not because Singapore has somehow defeated scammers — it hasn’t — but because its latest figures suggest something many of us desperately need to see: the numbers can actually move in the right direction.
During the first half of 2026, Singapore recorded 16,821 scam cases, down 14.4% from the same period in 2025. Reported losses fell 17.9%, from S$500.2 million to S$410.6 million. Cases involving losses of S$100,000 or more also fell by almost a quarter.
Those numbers matter to me because I sometimes wonder whether we’re actually winning anything.
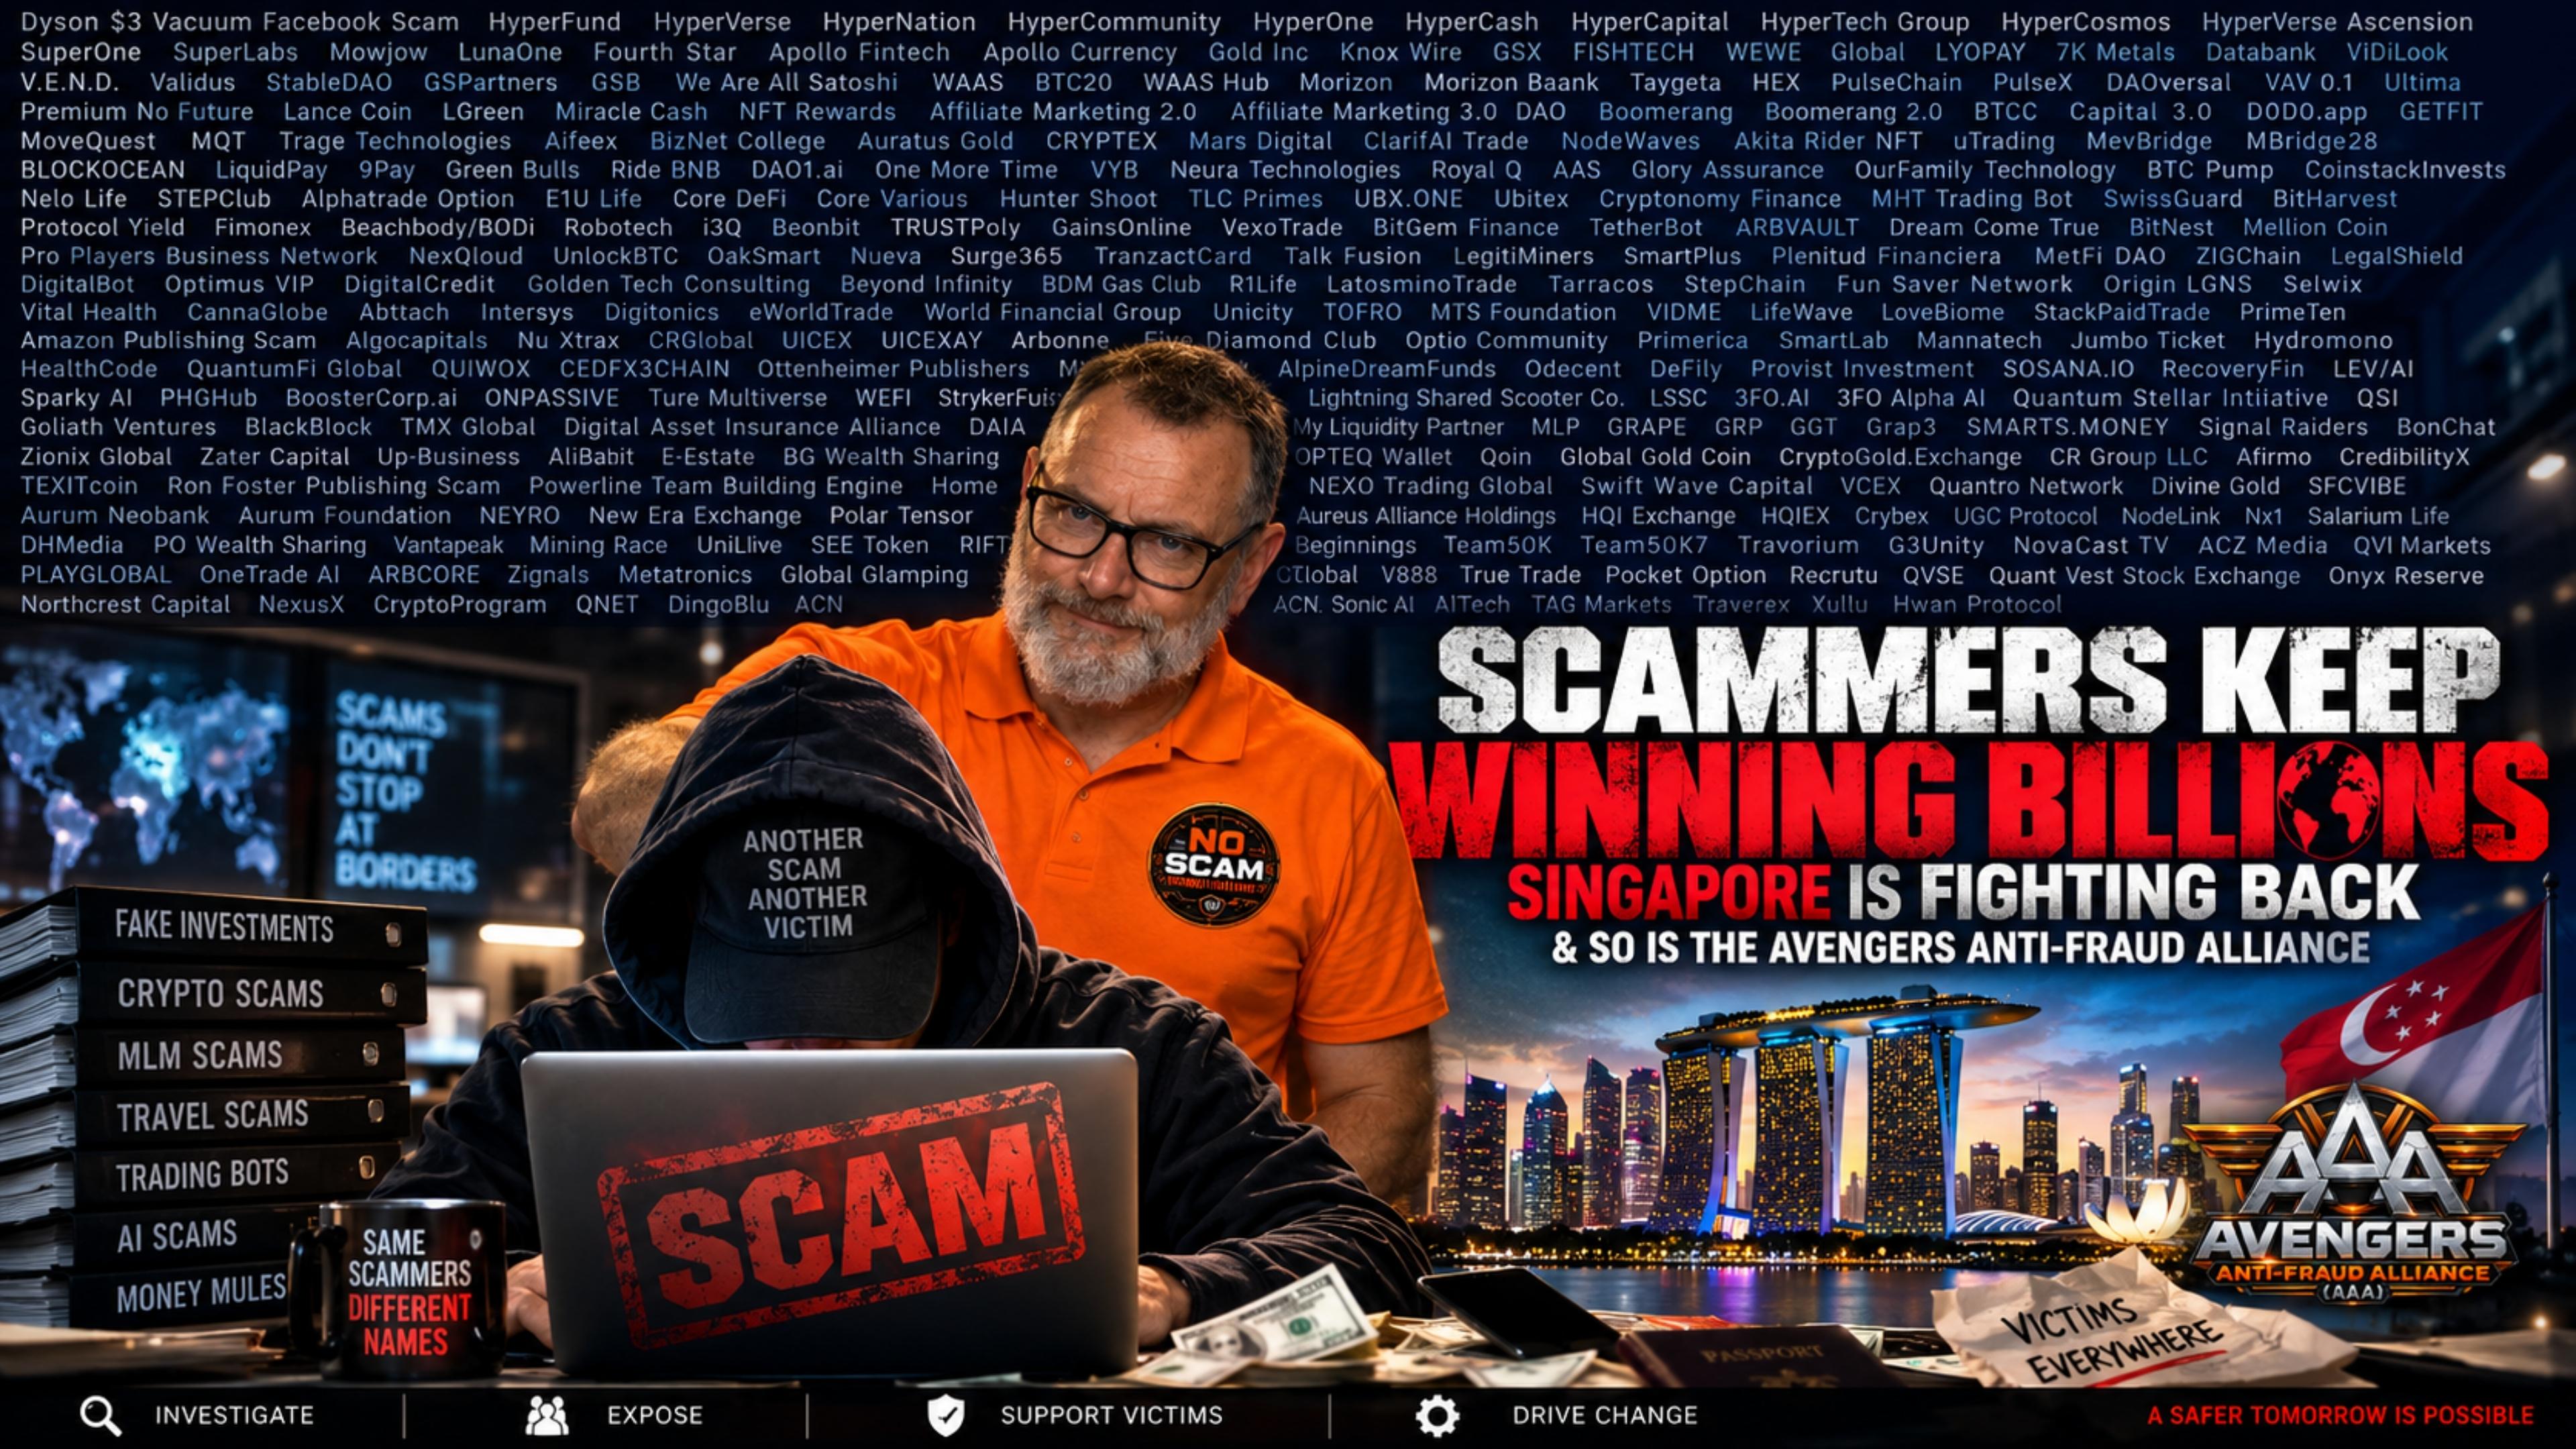
Behind my investigations is now a staggering list of companies, investment platforms, cryptocurrency projects, MLM opportunities and alleged fraud operations that I have researched and written about. Some of those names will be instantly recognisable to victims. Others disappeared almost as quickly as they arrived. I intend to publish that entire list in this article, not to declare that every name on it has been legally proven to be a scam, but to demonstrate the scale of what independent investigators are confronting.
Singapore’s results raise a much bigger question. If one country can disrupt tens of thousands of scam websites, phone lines and online accounts while simultaneously reducing reported losses, perhaps we need to stop treating fraud as something victims are simply expected to protect themselves from.
Maybe the real question isn’t why people keep falling for scams. Maybe it’s why we keep allowing scammers to reach them in the first place.
Singapore Is Actually Moving The Numbers
What impressed me about Singapore wasn’t simply that scam losses had fallen. Governments publish warnings about scams every day. Police issue media releases, banks tell customers to be careful, and social-media companies remind us that suspicious advertisements should be reported. Singapore appears to be doing something much more aggressive: attacking the infrastructure scammers depend on before another victim sends money.
During the first six months of 2026, Singapore Police disrupted approximately 47,500 scam-related mobile lines, 37,500 WhatsApp lines, 31,600 online monikers and 52,200 malicious websites. More than 2,900 suspected money mules and scammers were investigated, with at least 470 charged.
Those aren’t awareness-campaign statistics. They are disruption statistics.
Singapore’s Anti-Scam Centre also reported freezing or recovering more than S$97.7 million connected with scam losses, including over S$8 million in cryptocurrency. Importantly, the report explains that money described as “recovered” includes funds that have been frozen and does not necessarily mean that money has already been returned to victims. The Centre also estimates that proactive intervention prevented at least another S$127.1 million in potential losses.
This is where I think the Singapore story becomes particularly interesting. Its authorities aren’t relying on one solution. They are targeting websites and phone lines, working with financial institutions, sharing intelligence, pursuing money mules, disrupting cryptocurrency flows and putting pressure on the technology companies whose platforms scammers use to find their victims.
The results don’t prove that every one of those measures caused the decline, and Singapore certainly hasn’t eliminated the problem. S$410.6 million was still lost to scams in only six months. That’s an enormous amount of money.
But when scam cases fall 14.4%, overall losses fall 17.9%, and the number of people losing S$100,000 or more falls 24.5%, while authorities are simultaneously dismantling tens of thousands of pieces of scam infrastructure, I think it deserves our attention.
Because after years of watching scammers adapt faster than the systems designed to stop them, Singapore is giving us something considerably more useful than another warning about suspicious links.
It is giving us measurable results.
The Scams I Keep Seeing
When I reached the section of Singapore’s report dealing with investment scams, the methods being described were immediately familiar. Investment scams caused S$169.8 million in losses during the first half of 2026, making them Singapore’s largest scam category by money lost. There were 2,256 reported cases, with an average loss of more than S$75,000 per case.
But it was the mechanics behind those numbers that interested me.
Singapore Police describe victims being approached through advertisements, social media, messaging applications and investment chat groups. Inside those groups are supposed investment experts or “mentors”, accompanied by other members posting about their successful trades and profits. Victims are then directed towards websites or applications showing apparently successful investments. Sometimes they are even allowed to withdraw a small amount of money early in the process, reinforcing the belief that the investment is genuine.
I have seen this pattern repeatedly in my own investigations.
The names change. The websites change. Sometimes it is cryptocurrency, sometimes artificial intelligence, forex trading, automated bots, gold, staking, nodes or some supposedly revolutionary financial technology. But underneath the marketing, the psychological machinery can be remarkably similar: establish credibility, manufacture social proof, show the victim apparent profits, encourage larger deposits and keep the money moving.
Then comes the moment I have heard about from victims far too many times.
They try to withdraw.
Suddenly there is a problem. The account needs verification. A tax must be paid. Funds need to be “unfrozen”. There is a security deposit, compliance fee or some other invented obstacle standing between the victim and the balance displayed on their screen. Singapore Police specifically warn about this progression, including demands for additional “fees” or “taxes” before withdrawals can supposedly be processed.
This is why I don’t believe we can understand modern investment fraud by looking only at the final bank transfer. By the time someone sends S$50,000, US$100,000 or their retirement savings, the scammer may have spent weeks or months constructing an environment designed to make that decision appear perfectly rational.
And when I started looking back through our own investigation archive, I realised just how many times I had watched variations of that same story unfold.
The Investigations Keep Piling Up
When I went back through my own archive, the scale of what we have been dealing with became difficult to ignore. Over the last few years I have investigated, documented or written about hundreds of companies, investment platforms, MLM opportunities, cryptocurrency projects, trading schemes and alleged fraud operations.
I need to be very clear about what inclusion on this list means. It does not mean every company named below has been legally determined to be a scam. Some collapsed. Some rebranded. Some attracted regulator warnings or enforcement action. Some became the subject of civil or criminal proceedings. Others remain active and strongly dispute criticism directed at them.
This is the record of what crossed my desk and became serious enough for me to investigate.
Dyson $3 Vacuum Facebook Scam, HyperFund, HyperVerse, HyperNation, HyperCommunity, HyperOne, HyperCash, HyperCapital, HyperTech Group, HyperCosmos, HyperVerse Ascension, SuperOne, SuperLabs, Mowjow, LunaOne, Fourth Star, Apollo Fintech, Apollo Currency, Gold Inc, Knox Wire, GSX, FISHTECH, WEWE Global, LYOPAY, 7K Metals, Databank, ViDiLook, V.E.N.D., Validus, StableDAO, GSPartners, GSB, We Are All Satoshi, WAAS, BTC20, WAAS Hub, Morizon, Morizon Baank, Taygeta, HEX, PulseChain, PulseX, DAOversal, VAV 0.1, Ultima, Premium No Future, Lance Coin, LGreen, Miracle Cash, NFT Rewards, Affiliate Marketing 2.0, Affiliate Marketing 3.0 DAO, Boomerang, Boomerang 2.0, BTCC, Capital 3.0, D0D0.app, GETFIT, MoveQuest, MQT, Trage Technologies, Aifeex, BizNet College, Auratus Gold, CRYPTEX, Mars Digital, ClarifAI Trade, NodeWaves, Akita Rider NFT, uTrading, MevBridge, MBridge28, BLOCKOCEAN, LquidPay, 9Pay, Green Bulls, Ride BNB, DAO1.ai, One More Time, VYB, Neura Technologies, Royal Q, AAS, Glory Assurance, OurFamily Technology, BTC Pump, CoinstackInvests, Nelo Life, STEPClub, Alphatrade Option, E1U Life, Core DeFi, Core Various, Hunter Shoot, TLC Primes, UBX.ONE, Ubitex, Cryptonomy Finance, MHT Trading Bot, SwissGuard, BitHarvest, Protocol Yield, Fimonex, Beachbody/BODi, Robotech, i3Q, Beonbit, TRUSTPoly, GainsOnline, VexoTrade, BitGem Finance, TetherBot, ARBVAULT, Dream Come True, BitNest, Mellion Coin, Pro Players Business Network, NexQloud, UnlockBTC, OakSmart, Nueva, Surge365, TranzactCard, Talk Fusion, LegitiMiners, SmartPlus, Plenitud Financiera, MetFi DAO, ZIGChain, LegalShield, DigitalBot, Optimus VIP, DigitalCredit, Golden Tech Consulting, Beyond Infinity, BDM Gas Club, R1Life, LatosminoTrade, Tarracos, StepChain, Fun Saver Network, Origin LGNS, Selwix, Vital Health, CannaGlobe, Abtach, Intersys, Digitonics, eWorldTrade, World Financial Group, Unicity, TOFRO, MTS Foundation, VIDME, LifeWave, LoveBiome, StackPaidTrade, PrimeTen, Amazon Publishing Scam, Algocapitals, Nu Xtrax, CRGlobal, UICEX, UICEXAY, Arbonne, Five Diamond Club, Optio Community, Primerica, SmartLab, Mannatech, Jumbo Ticket, Hydromono, HealthCode, QuantumFi Global, QUIWOX, CEDFX3CHAIN, Ottenheimer Publishers, Modern Living, AlpineDreamFunds, Odecent, DeFily, Provist Investment, SOSANA.IO, RecoveryFin, LEV/AI, Sparky AI, PHGHub, BoosterCorp.ai, and ONPASSIVE
Why People Still Fall For Them
One statistic in Singapore’s report cuts through a lot of the nonsense I hear about scam victims. In the first half of 2026, 80.8% of reported scam cases involved victims transferring the money themselves. The scammers generally didn’t need to hack into a bank account and steal it. They persuaded the victim to press the button.
That distinction matters because it explains so much of what I have witnessed during my investigations. These operations are often designed to make sending money feel like a sensible decision. There may be a professional website, a polished presentation, testimonials, screenshots of successful withdrawals, supposed trading results and a Telegram or WhatsApp group filled with people celebrating their profits. Sometimes the introduction comes from somebody the victim already knows and trusts.
By the time the money moves, the deception has already done its job.
This is also why I get frustrated when scam victims are dismissed as stupid, greedy or elderly. Singapore’s figures show that 64.4% of scam victims were under the age of 50. Younger people were certainly not immune. What did change dramatically with age was the financial damage. Victims aged 65 and above suffered an average loss of S$42,347, the highest of any age group.
I have spoken with intelligent, successful people who lost extraordinary amounts of money. I’ve also watched promoters exploit something far more powerful than ignorance: trust. Trust in a friend. Trust in somebody displaying wealth. Trust in a charismatic leader. Trust in a supposedly successful trading platform. Trust in a company that appears to have offices, lawyers, executives, technology and thousands of happy members.
The better the illusion, the less the victim feels like they are taking a reckless gamble.
That creates another problem. If governments concentrate primarily on educating people to recognise scams, scammers only need to become better at looking legitimate. Artificial intelligence, cloned websites, impersonation, fabricated testimonials and increasingly sophisticated online advertising make that easier, not harder.
Education matters. I have spent years doing it myself. But there comes a point where telling people to “do your own research” starts shifting responsibility away from the enormous systems that make these operations possible.
If four out of five scam cases involve victims willingly sending the money, the real battle is happening before the transfer is ever made.
Ture Multiverse, WEFI, StrykerFusion, Lightweb, Lightning Shared Scooter Co., LSSC, 3FO.AI, 3FO Alpha AI, Quantum Stellar Initiative, QSI, Goliath Ventures, BlackBlock, TMX Global, Digital Asset Insurance Alliance, DAIA, XRP AI Bot, My Liquidity Partner, MLP, GRAPE, GRP, GGT, Grap3, SMARTS.MONEY, Signal Raiders, BonChat, Zionix Global, Zater Capital, Up-Business, AliBarbit, E-Estate, BG Wealth Sharing, DSJEX, OPTEQ Wallet, Qoin, Global Gold Coin, CryptoGold.Exchange, CR Group LLC, Afirmo, CredibilityX, TEXITcoin, Ron Foster Publishing Scam, Powerline Team Building Engine, Home Business Academy, NEXO Trading Global, Swift Wave Capital, VCEX, Quantro Network, Divine Gold, SFCVIBE, Aurum Neobank, Aurum Foundation, NEYRO, New Era Exchange, Polar Tensor, Aureus Alliance Holdings, HQI Exchange, HQIEX, Crybex, UGC Protocol, NodeLink, Nx1, Salarium Life, DHMedia, PO Wealth Sharing, Vantapeak, Mining Race, UniLive, SEE Token, RIFT Protocol, 8 New Beginnings, Team50K, Team50K7, Travorium, G3Unity, NovaCast TV, ACZ Media, QVI Markets, PLAYGLOBAL, OneTrade AI, ARBCORE, Zignals, Metatronics, Global Glamping, Predixa, ONET Global, V888, True Trade, Pocket Option, Recrutu, QVSE, Quant Vest Stock Exchange, Onyx Reserve, Northcrest Capital, NexusX, CryptoProgram, QNET, DingoBlu, ACN, Sonic AI, AITech, TAG Markets, Traverex, Xullu and Hwan Protocol.
Seeing those names together tells a story that individual investigations never quite capture.
Many of these operations had completely different branding, products and personalities. One might claim to be an artificial-intelligence trading system, another a cryptocurrency ecosystem, another a travel club, another a gold opportunity, another a decentralised finance platform. Yet again and again I found myself asking the same questions: Where is the money coming from? Who controls it? What is actually being sold? Who gets paid when someone new joins? Can the claimed profits be independently verified? What happens when people try to withdraw?
That is the part of scam prevention that statistics alone struggle to show. Behind every new name is another marketing campaign, another presentation, another group of promoters and another audience being told they have discovered something before everybody else.
The branding changes far faster than the behaviour does.
Stop Putting All The Responsibility On Victims
If scammers were operating entirely in the shadows, this would be a very different fight. But they aren’t. They need infrastructure. They need websites, advertisements, social-media accounts, messaging applications, mobile numbers, bank accounts, cryptocurrency wallets and somewhere to find their next victim.
Singapore’s figures make that particularly difficult to ignore. In the first half of 2026, 89% of scam cases involved an online platform as the first point of contact. Meta’s Facebook, WhatsApp and Instagram alone accounted for 34.1% of all scam cases.
That looks very familiar from where I sit.
I have joined the WhatsApp groups. I have watched the Telegram channels fill with supposed success stories. I have seen questionable investment advertisements promoted through social media and watched promoters use Zoom presentations to recruit people into opportunities most viewers would never have discovered otherwise. By the time investigators like us find them, thousands of people can already have been exposed to the marketing.
Singapore appears to have recognised that telling the public to be more careful isn’t enough. Its authorities have issued directions involving Apple, Google and Meta, introduced measures restricting facilities used by scammers, expanded information sharing and developed systems intended to identify and disrupt scam activity earlier. The country has also introduced Codes of Practice for designated online services, with proposed enforcement powers that can include penalties of up to S$10 million for non-compliance under its Online Criminal Harms framework.
That changes the conversation.
Instead of asking only, “Why did the victim click on that advertisement?”, we should also be asking why the advertisement was there, who was paid to display it, what checks were performed before it was approved, how quickly it disappeared after being reported and whether the same advertiser simply opened another account.
The same questions apply further down the chain. What happens when a bank identifies suspicious payments? How quickly can a telecommunications provider disable numbers being used repeatedly for fraud? How easily can criminals open replacement accounts? How quickly can money be frozen once a victim realises what has happened?
Singapore is increasingly treating those organisations as participants in the solution rather than spectators watching the crime happen. Its 2026 report describes measures involving financial institutions, telecommunications companies, online platforms and government agencies, including increased data sharing and intervention intended to stop suspicious transactions before the money disappears.
I still believe people need to learn the warning signs. That’s one of the reasons I publish these investigations. But after documenting hundreds of questionable operations, I don’t accept that the person sitting at home should carry almost the entire burden of defeating a sophisticated international fraud industry.
Scammers are using infrastructure owned and controlled by some of the most powerful organisations in the world. Those organisations need to be part of stopping them.
Stop Putting All The Responsibility On Victims
If scammers were operating entirely in the shadows, this would be a very different fight. But they aren’t. They need infrastructure. They need websites, advertisements, social-media accounts, messaging applications, mobile numbers, bank accounts, cryptocurrency wallets and somewhere to find their next victim.
Singapore’s figures make that particularly difficult to ignore. In the first half of 2026, 89% of scam cases involved an online platform as the first point of contact. Meta’s Facebook, WhatsApp and Instagram alone accounted for 34.1% of all scam cases.
That looks very familiar from where I sit.
I have joined the WhatsApp groups. I have watched the Telegram channels fill with supposed success stories. I have seen questionable investment advertisements promoted through social media and watched promoters use Zoom presentations to recruit people into opportunities most viewers would never have discovered otherwise. By the time investigators like us find them, thousands of people can already have been exposed to the marketing.
Singapore appears to have recognised that telling the public to be more careful isn’t enough. Its authorities have issued directions involving Apple, Google and Meta, introduced measures restricting facilities used by scammers, expanded information sharing and developed systems intended to identify and disrupt scam activity earlier. The country has also introduced Codes of Practice for designated online services, with proposed enforcement powers that can include penalties of up to S$10 million for non-compliance under its Online Criminal Harms framework.
That changes the conversation.
Instead of asking only, “Why did the victim click on that advertisement?”, we should also be asking why the advertisement was there, who was paid to display it, what checks were performed before it was approved, how quickly it disappeared after being reported and whether the same advertiser simply opened another account.
The same questions apply further down the chain. What happens when a bank identifies suspicious payments? How quickly can a telecommunications provider disable numbers being used repeatedly for fraud? How easily can criminals open replacement accounts? How quickly can money be frozen once a victim realises what has happened?
Singapore is increasingly treating those organisations as participants in the solution rather than spectators watching the crime happen. Its 2026 report describes measures involving financial institutions, telecommunications companies, online platforms and government agencies, including increased data sharing and intervention intended to stop suspicious transactions before the money disappears.
I still believe people need to learn the warning signs. That’s one of the reasons I publish these investigations. But after documenting hundreds of questionable operations, I don’t accept that the person sitting at home should carry almost the entire burden of defeating a sophisticated international fraud industry.
Scammers are using infrastructure owned and controlled by some of the most powerful organisations in the world. Those organisations need to be part of stopping them.
Are We Doing Enough?
Singapore made me look closer at what is happening elsewhere, because it would be unfair to suggest other governments are simply sitting back and watching. New Zealand, Australia and the United States are all taking action against scams. The harder question is whether those efforts are producing results quickly enough — and whether we are measuring those results in a way the public can actually understand.
Here in New Zealand, the Government launched the Anti-Scam Alliance in 2025, bringing together government agencies, banks, telecommunications companies, digital platforms and consumer organisations. Its 2026 work programme includes better information sharing, stronger disruption tools, expansion of Confirmation of Payee and a review of the telecommunications Scam Prevention Code. The scale of the problem is substantial: official figures put gross reported fraud losses at more than NZ$265 million over the 12 months to October 2025.
Those are positive developments. But after reading Singapore’s report, I found myself wanting a different set of numbers.
How many scam websites did we disrupt? How many fraudulent advertisements were removed? How many scam phone numbers were disabled? How many mule accounts were identified? How many scammers and facilitators were prosecuted? How much money was frozen before it disappeared overseas? And, most importantly, are New Zealanders actually losing less money because of what we’re doing?
Singapore can tell us that it disrupted 52,200 malicious websites, 47,500 scam-related mobile lines and 37,500 WhatsApp lines in six months. It investigated more than 2,900 suspected scammers and money mules and charged at least 470. Its Anti-Scam Centre froze or recovered more than S$97.7 million and estimates proactive intervention prevented at least another S$127.1 million in potential losses.
Australia demonstrates why this needs to be measured continuously. Combined reported scam losses fell sharply in 2024, dropping 25.9% to A$2 billion. But in 2025 they climbed again to A$2.18 billion, an increase of 7.8%. That doesn’t mean Australia’s efforts failed. It shows how quickly scammers adapt and why one good year cannot be treated as victory.
The United States provides an even more sobering comparison. The FBI reported more than US$20 billion in losses from internet crime in 2025, a 26% increase from 2024. Investment fraud alone accounted for approximately US$8.65 billion.
These countries are different sizes, their reporting systems aren’t identical, and I wouldn’t pretend the figures can simply be placed beside each other as though they were measuring precisely the same thing. But the direction of travel matters.
Singapore has given us something against which governments can be judged: not how many warnings they publish, but how much criminal infrastructure they disrupt, how much money they stop from disappearing and whether fewer people are being robbed.
After years of investigating this industry, that’s the standard I want to see everywhere.
From Independent Investigations To An Anti-Fraud Alliance
For years, much of this work has been reactive. Somebody sends me a company name, a victim reaches out, a suspicious presentation lands in my inbox, or one of our investigators spots something that doesn’t add up. I start digging, other researchers contribute what they find, victims begin talking and eventually an investigation starts taking shape.
That approach has produced an extraordinary amount of evidence, but the list earlier in this article demonstrates the problem. There are simply too many operations for one investigator — or even a small network of investigators — to follow properly.
Over time, something else has happened. People with different skills have started finding each other. Blockchain investigators, researchers, victims, whistleblowers, content creators and people who simply refuse to watch scammers destroy lives without doing something about it have contributed to investigations in different ways.
That network is now becoming something more organised.
The Avenger Network has co-founded the Avengers Anti-Fraud Alliance, a new community we are building to bring those people together. It is still under development, and I’m not going to pretend we have everything figured out. What we do have is years of investigations behind us, an enormous body of research and a growing group of people who understand that fighting scams requires cooperation.
Membership is currently free, and people can join us at avengers.dehek.com.
The timing feels particularly appropriate after reading Singapore’s report. One of the strongest lessons I took from it wasn’t a particular statistic or piece of legislation. It was that isolated efforts aren’t enough. Police need information from banks. Banks need intelligence from other institutions. Telecommunications providers need to shut down infrastructure. Technology companies need to remove criminal accounts and advertisements. Investigators need victims to come forward, and victims need somewhere they can be heard.
Our Alliance obviously doesn’t have the powers of a government, and we shouldn’t pretend that it does. We can’t order a bank to freeze an account or force a technology company to remove an advertisement.
But we can investigate. We can connect information that would otherwise remain scattered. We can expose promoters and operations publicly. We can help victims understand what happened to them. We can provide evidence to journalists, platforms, regulators and law enforcement. And, perhaps most importantly, we can make it harder for the same people to quietly move from one operation to the next without somebody recognising them.
After hundreds of investigations, I don’t want to build another group that simply talks about scams.
I want to build a network that helps expose them.
What Would Actually Make A Difference?
After reading Singapore’s report and looking back through years of my own investigations, I don’t believe there is one magic solution to scams. Shut down a website and another can appear. Freeze a bank account and criminals move to cryptocurrency. Remove an advertisement and another account can buy the next one. Arrest the person collecting the money and somebody further up the chain may still be sitting safely in another country.
What Singapore demonstrates is that you don’t need to eliminate scams completely to make a measurable difference. You need to make every stage harder: harder to advertise, harder to contact victims, harder to move money, harder to recruit money mules, harder to hide behind disposable accounts and harder to simply start again when one operation is exposed.
That requires something I have become increasingly convinced is missing from the way many countries approach fraud: accountability for everybody in the chain.
Victims have responsibilities. So do promoters. So do banks, cryptocurrency exchanges, telecommunications companies, payment processors, advertising networks and social-media platforms. Governments and regulators have responsibilities as well. Singapore’s own report describes this as a whole-of-society effort involving individuals, businesses, financial institutions, marketplaces and telecommunications providers.
But responsibility without measurement doesn’t tell us very much.
I want governments to tell us how many scam websites they disrupted, how many accounts they froze, how many fraudulent advertisements they stopped, how many money mules they prosecuted and how much stolen money they prevented from leaving the country. I want technology companies to tell us how quickly they respond when investigators report obvious fraud. I want banks and cryptocurrency businesses to demonstrate what happens when the warning signs are sitting directly in front of them.
Most importantly, I want to know whether fewer people are losing money.
Singapore still has a serious scam problem. More than S$410 million disappearing in six months is hardly a victory parade. But cases are falling, losses are falling, high-value losses are falling and authorities can point to tens of thousands of pieces of scam infrastructure they have disrupted.
That gives the rest of us something worth examining.
After hundreds of investigations, I know we will never educate every person before a scammer reaches them. There will always be somebody facing financial pressure, somebody looking for an opportunity, somebody trusting a friend, somebody persuaded by an impressive presentation and somebody who doesn’t discover my investigation until the money has already gone.
So perhaps we have been asking the wrong question.
Instead of constantly asking why another victim didn’t recognise the scam, maybe we should start asking why the scammer was able to advertise to them, contact them, collect their money and move it away in the first place.
Because if Singapore’s numbers tell us anything, it is that scam losses are not simply something society has to accept.
They can be reduced.
And now that we know that, every government, bank, telecommunications company and technology platform should have to answer a much harder question:
What are you doing to prove that you are reducing them?
Disclaimer: How This Investigation Was Conducted
This investigation relies entirely on OSINT — Open Source Intelligence — meaning every claim made here is based on publicly available records, archived web pages, corporate filings, domain data, social media activity, and open blockchain transactions. No private data, hacking, or unlawful access methods were used. OSINT is a powerful and ethical tool for exposing scams without violating privacy laws or overstepping legal boundaries.
About the Author
I’m DANNY DE HEK, a New Zealand–based YouTuber, investigative journalist, and OSINT researcher. I name and shame individuals promoting or marketing fraudulent schemes through my YOUTUBE CHANNEL. Every video I produce exposes the people behind scams, Ponzi schemes, and MLM frauds — holding them accountable in public.
My PODCAST is an extension of that work. It’s distributed across 18 major platforms — including Apple Podcasts, Spotify, Amazon Music, YouTube, and iHeartRadio — so when scammers try to hide, my content follows them everywhere. If you prefer listening to my investigations instead of watching, you’ll find them on every major podcast service.
You can BOOK ME for private consultations or SPEAKING ENGAGEMENTS, where I share first-hand experience from years of exposing large-scale fraud and helping victims recover.
“Stop losing your future to financial parasites. Subscribe. Expose. Protect.”
My work exposing crypto fraud has been featured in:
Coffeezilla 2026): Featured in the investigation exposing the alleged $328M Goliath Ventures Ponzi scheme
Bloomberg Documentary (2025): A 20-minute exposé on Ponzi schemes and crypto card fraud
News.com.au (2025): Profiled as one of the leading scam-busters in Australasia
OpIndia (2025): Cited for uncovering Pakistani software houses linked to drug trafficking, visa scams, and global financial fraud
The Press / Stuff.co.nz (2023): Successfully defeated $3.85M gag lawsuit; court ruled it was a vexatious attempt to silence whistleblowing
The Guardian Australia (2023): National warning on crypto MLMs affecting Aussie families
ABC News Australia (2023): Investigation into Blockchain Global and its collapse
The New York Times (2022): A full two-page feature on dismantling HyperVerse and its global network
Radio New Zealand (2022): “The Kiwi YouTuber Taking Down Crypto Scammers From His Christchurch Home”
Otago Daily Times (2022): A profile on my investigative work and the impact of crypto fraud in New Zealand