
The Market Says Alcohol Is Dying. But Is That Really the Whole Story?
Diageo, the world's largest spirits company, recently delivered some very bad news:
Sales have declined.
The company plans to spend US$1.2 billion restructuring the business.
Thousands of jobs could be cut.
Dividend policy is being changed.
Yet the stock price went up.
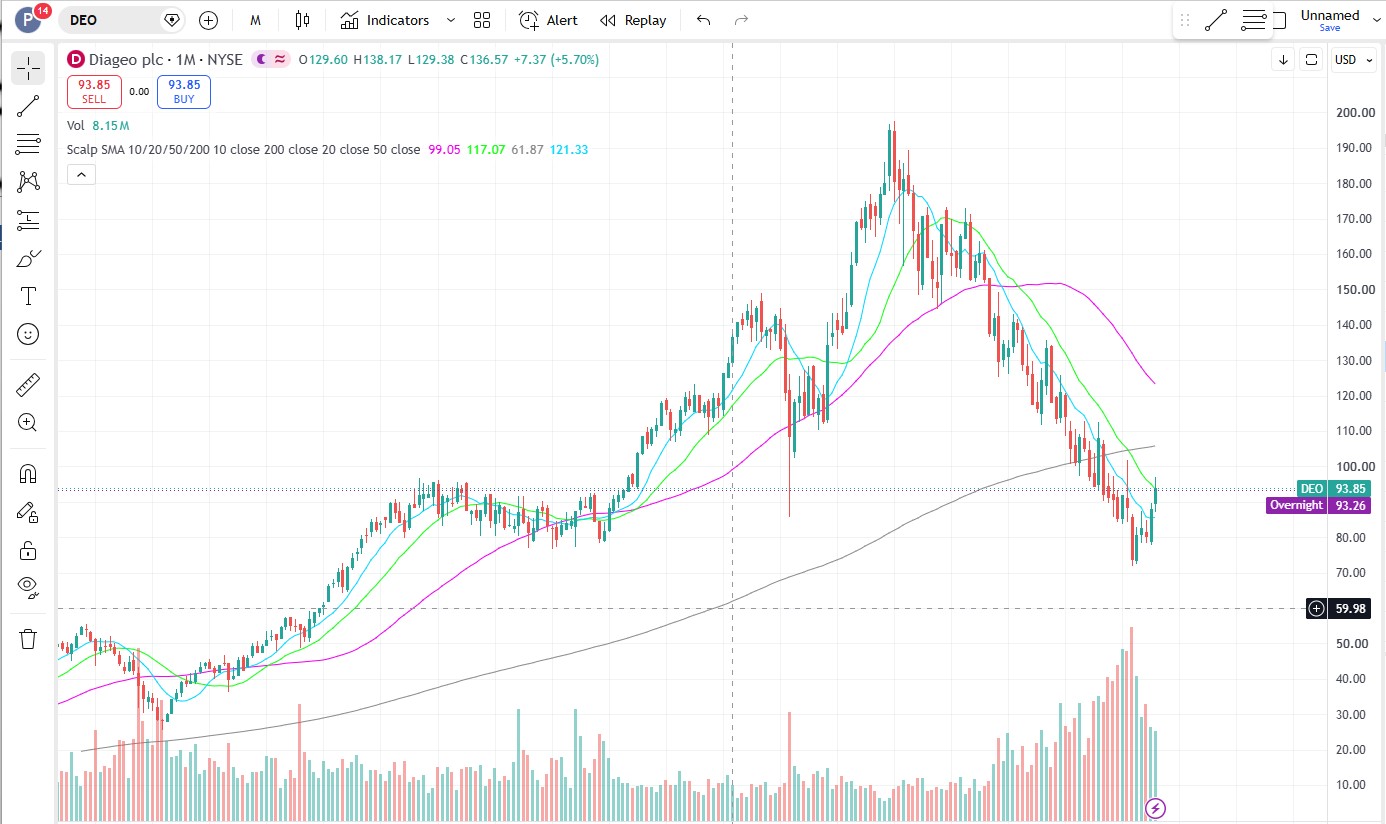 This chart shows the monthly share price of Diageo (the world largest spirit company) from 2007 to August 2026.
That tells us something important:
The market may already have priced in much of the bad news.
But there is another question investors should ask:
Is the global alcohol industry really in structural decline — or is the decline mainly happening in mature Western markets?
And even if alcohol consumption does decline over the long term, there is another important question:
Can a declining industry still produce good investment returns?
History says yes.
The US Alcohol Story Is Clearly Changing
The original bear case against alcohol is real.
In the US:
The percentage of adults who drink has fallen from 67% in 2022 to 54%.
Younger consumers, particularly Gen Z, are drinking less.
Health and fitness are becoming more important.
GLP-1 drugs may further reduce alcohol consumption.
These are not simply temporary problems.
The US is behaving like a mature market where alcohol consumption has reached a ceiling and is now moving lower.
That is a serious structural challenge for companies heavily exposed to the US and other developed markets.
But Southeast Asia Is Different
This is where the story becomes much more interesting.
Southeast Asia is not one homogeneous alcohol market.
The region is at different stages of the alcohol-consumption cycle.
Emerging markets
Vietnam, Cambodia and Laos
These markets have experienced substantial increases in alcohol consumption over the past two decades.
For example:
Vietnam: 3.88L → 11.54L
Cambodia: 0.80L → 6.37L
Laos: 8.63L → 11.48L
The underlying driver is straightforward:
As incomes rise, consumers often spend more on branded consumer products — including alcohol.
More mature markets
Singapore, Thailand and the Philippines
These markets are much closer to the mature-market stage.
Consumption has been relatively stable or slightly declining:
Singapore: 2.12L → 2.00L
Thailand: 8.30L → 7.86L
Philippines: 5.85L → 6.01L
This is also where the sober-curious trend is beginning to appear among younger, wealthier urban consumers.
Structurally low-consumption markets
Malaysia, Indonesia and Brunei
These markets remain structurally low because of religious and cultural factors.
So investors should not make the mistake of treating Southeast Asia as one single growth market.
The opportunity is concentrated in particular countries and consumer segments.
Southeast Asia Is Not Yet at America's Stage
This is probably the most important insight.
The US is asking:
"How do we sell alcohol to consumers who are drinking less?"
Many emerging Southeast Asian markets are still asking:
"Which brands will consumers buy as their incomes rise?"
That is a completely different investment environment.
Recent IWSR data also points to Southeast Asia as one of the brighter areas for alcohol, with Vietnam, Thailand and the Philippines each recording 2% volume growth in 2024, while China declined 5%.
The growth drivers include:
Rising affluence
Tourism
Cocktail culture
Premiumisation
Expanding consumer spending
So the global alcohol story is becoming increasingly fragmented.
The Regional Map Is Being Redrawn
And this is where Carlsberg Malaysia becomes particularly interesting.
On 6 July 2026, Carlsberg Group announced a strategic partnership with Japan's Sapporo Breweries.
Sapporo will invest US$643 million, approximately RM2.62 billion, for a 25% stake in a new joint venture.
The JV will combine Carlsberg's existing businesses across:
🇲🇾 Malaysia
🇸🇬 Singapore
🇭🇰 Hong Kong
🇻🇳 Vietnam
🇰🇭 Cambodia
🇱🇦 Laos
Carlsberg will retain 75% ownership and full operational control.
The transaction also gives the new JV perpetual exclusive rights to produce and distribute Sapporo Premium Beer across these markets.
This is strategically important.
Why?
Because a company that was previously viewed mainly as a Malaysian beer business is now sitting inside a much broader regional platform.
Why Sapporo Matters
This is not simply about selling more beer.
Sapporo brings a premium Japanese brand into Carlsberg's existing distribution network.
That creates an interesting combination:
Carlsberg's regional distribution + Sapporo's premium positioning
And Sapporo has an ambitious target: it wants sales of Sapporo Premium Beer in the target markets to reach around 10 times 2025 levels by 2035.
If that happens, the growth opportunity could be considerably larger than simply increasing volumes of existing Carlsberg brands.
The story becomes:
More consumers → higher incomes → premiumisation → stronger branded beer consumption.
But Don't Get Too Excited Too Quickly
Carlsberg Malaysia itself has said that there will be no change to day-to-day operations, customer relationships or existing commercial arrangements as a result of the announcement.
So investors should not interpret the transaction as:
"Carlsberg Malaysia earnings will suddenly explode."
That is not what has been announced.
The more interesting question is:
How much of the future regional growth will ultimately flow through to the listed Malaysian company?
That requires careful analysis of:
The JV structure.
Carlsberg Malaysia's ownership.
Earnings consolidation.
Dividend flows.
Transfer pricing.
Licensing arrangements.
Regional capital allocation.
Future financial disclosures.
The opportunity may be real, but the economics still need to be understood.
We Have Seen This Movie Before: Tobacco
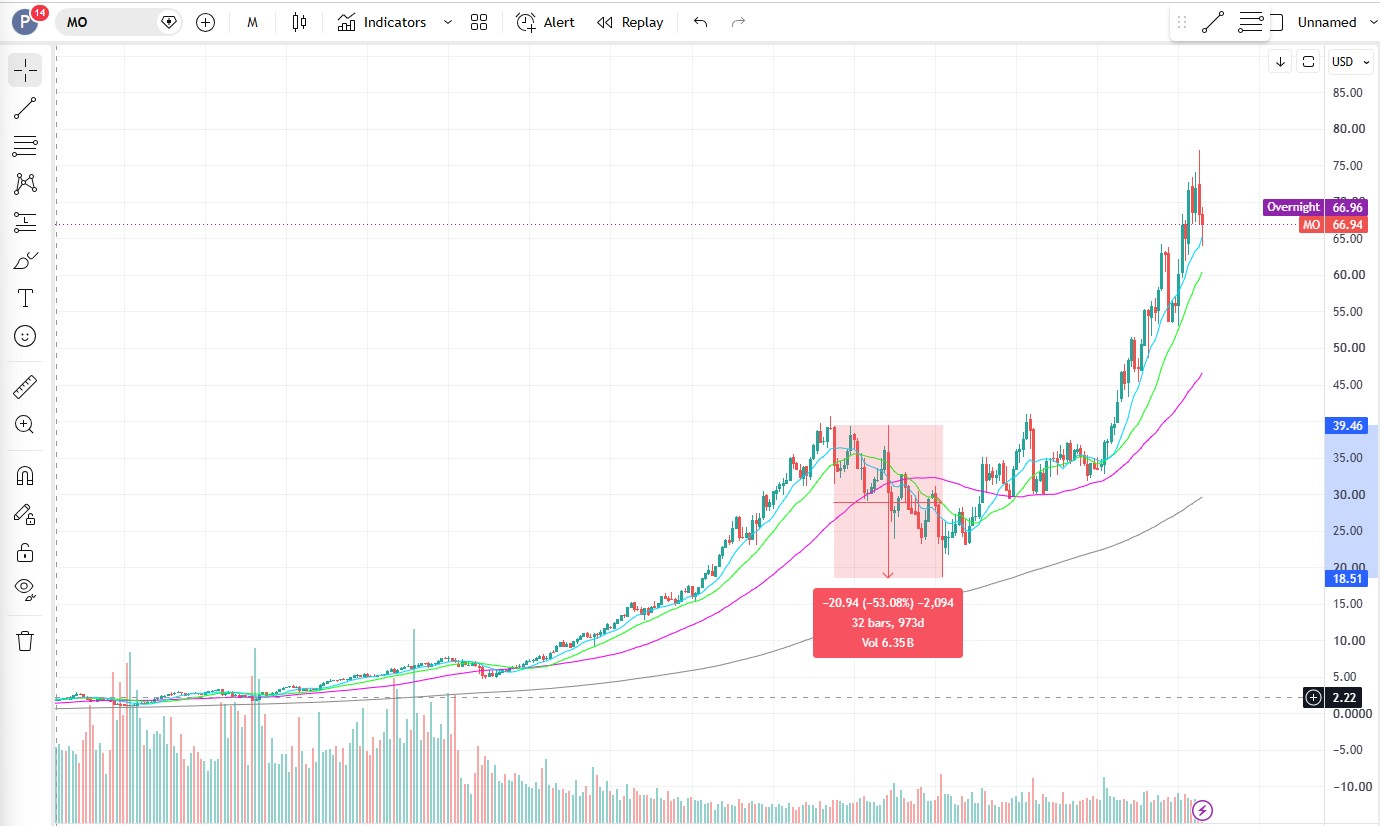
This chart shows the monthly share price of Altria Group (the maker of Marlboro cigarettes) from 1998 to August 2026. It suffered a crash of ~53% in July 2017 - Mar 2020; before recovering and made a new all-time high now.
Now we come to the most important historical lesson.
There is an industry that spent decades in documented, undeniable volume decline.
That industry was tobacco.
For decades, tobacco faced:
Falling smoking rates.
Advertising restrictions.
Higher taxes.
Regulation.
Litigation.
Health campaigns.
Increasing public opposition.
The product itself was increasingly viewed as harmful.
And yet, tobacco companies produced extraordinary long-term shareholder returns.
The original newsletter highlights Altria's remarkable historical total return over many decades.
The important lesson is not:
"Alcohol will become the next tobacco."
That would be far too simplistic.
The real lesson is:
A declining industry can still be an excellent investment if the economics of the remaining business are exceptionally strong and the valuation is low enough.
Why Did Tobacco Work?
The answer comes down to a few powerful economic characteristics.
1. Pricing power
Even as volumes fell, tobacco companies could raise prices.
A business does not necessarily need volume growth if it can increase revenue per customer.
2. Powerful brands
Consumers who remain loyal to a brand can be extremely valuable.
When the customer base becomes smaller but more loyal, companies can still generate substantial cash flow.
3. Distribution advantages
The major tobacco companies already controlled enormous distribution networks.
New competitors could not easily replicate them.
The same principle exists in spirits and beer.
Walk into a good bar and look at the premium shelves.
A relatively small number of global companies control a huge number of famous brands.
4. Cash generation
Declining industries often require less capital investment than high-growth industries.
If management returns that cash through:
Dividends
Share buybacks
Debt reduction
then shareholders can still generate attractive returns.
5. Valuation
This may be the most important factor.
A declining business bought at 20x earnings can be a terrible investment.
The same business bought at 8–10x earnings, with strong cash flow and pricing power, can potentially be very attractive.
The price you pay matters enormously.
The Lesson for Alcohol
This is exactly why the Diageo situation deserves attention.
The question is not:
"Will alcohol consumption grow forever?"
It probably won't.
The better question is:
"Can the strongest alcohol companies continue generating strong cash flow even if volumes decline?"
If the answer is yes, then the investment opportunity depends heavily on valuation.
That is the tobacco lesson.
But There Is One Major Difference
We should not blindly extrapolate tobacco's history to alcohol.
Tobacco had an unusual economic structure:
Highly addictive product.
Extremely strong customer loyalty.
Limited substitution for existing smokers.
Powerful pricing ability.
Very high margins.
Enormous cash generation.
Alcohol is different.
Consumers have many more alternatives:
Beer
Spirits
Wine
Cocktails
Non-alcoholic drinks
Functional beverages
Social activities without alcohol
And alcohol does not have the same level of physical dependence as nicotine.
So:
Tobacco is a useful framework — not a guarantee.
Now We Have Two Very Different Alcohol Investment Stories
This brings us back to Diageo vs Carlsberg Malaysia.
🥃 Diageo — The Contrarian Turnaround
The thesis:
Extremely depressed valuation.
Strong global brands.
Huge distribution network.
Potential management turnaround.
Emerging-market growth could offset mature-market weakness.
Market may have priced in excessive pessimism.
But the risks:
US and Western alcohol consumption is declining.
Gen Z is drinking less.
GLP-1 drugs could accelerate the trend.
Turnaround execution could take years.
This is primarily a turnaround + valuation thesis.
🍺 Carlsberg Malaysia — The Southeast Asia Growth Play
The thesis is different.
Potential exposure to:
Malaysia
Singapore
Vietnam
Cambodia
Laos
Hong Kong
through the broader Carlsberg regional structure.
And now there is:
Sapporo + Carlsberg distribution + Southeast Asian growth
Potential drivers include:
Rising incomes.
Tourism.
Premiumisation.
Growing beer culture.
Sapporo's premium Japanese positioning.
Regional scale.
This is primarily a Southeast Asian consumer-growth + premiumisation thesis.
Which Is More Attractive?
That depends on what type of investor you are.
If you are looking for:
Deep value + turnaround
→ Diageo deserves investigation.
If you are looking for:
Southeast Asian consumer growth + regional beer exposure
→ Carlsberg Malaysia deserves investigation.
But neither conclusion means:
"Buy the stock."
That is where investors need to slow down.
The Valuation Still Matters
A great story does not automatically make a great investment.
For Diageo, investigate:
P/E
Free cash flow
Debt
Dividend sustainability
Brand strength
Regional earnings mix
Turnaround progress
For Carlsberg Malaysia, investigate:
Current valuation
Dividend yield
Earnings growth
Market share
Excise duties
JV economics
How much regional growth reaches the listed company
Sapporo contribution
Minority shareholder economics
buymeacoffee.com/deepvaluecontrarian/deep-dive-stock-analysis-klse-027-issue
The Carlsberg-Sapporo deal is strategically interesting, but investors should not assume the entire US$643 million transaction directly translates into value for Carlsberg Malaysia shareholders.
That needs to be worked out from the corporate structure and future disclosures.
The Sober-Curious Trend Is Still Coming
There is another side to the story.
Singapore and Bangkok could become important leading indicators.
If younger Southeast Asian consumers eventually begin behaving more like their Western counterparts:
Drinking less.
Prioritising fitness.
Choosing non-alcoholic alternatives.
Going out less.
Becoming more health-conscious.
then the current Southeast Asian growth story could eventually slow.
But today, that appears to be a developing trend rather than the dominant regional story.
The question is:
How long does Southeast Asia remain in the rising-consumption phase before reaching maturity?
That is something investors should watch.
The Global Alcohol Industry Is Splitting Into Two Stories
🇺🇸 US / Western markets
Mature → declining
Lower consumption.
Health-conscious consumers.
Gen Z drinking less.
GLP-1 pressure.
Non-alcoholic alternatives.
🇸🇬 Singapore / 🇹🇭 Thailand
Mature → stabilising
Slower growth.
Sober-curious behaviour emerging.
Urban consumers increasingly health-conscious.
🇻🇳 Vietnam / 🇰🇭 Cambodia / 🇱🇦 Laos
Emerging → growing
Rising incomes.
Urbanisation.
Tourism.
Premiumisation.
Expanding middle class.
🇲🇾 Malaysia / 🇮🇩 Indonesia / 🇧🇳 Brunei
Structurally low
Cultural and religious factors limit the addressable alcohol market.
The Bigger Investment Lesson
There are actually three separate questions investors should ask.
Question 1: Is the industry growing?
Not necessarily.
Question 2: Can individual companies still grow?
Yes — particularly through premiumisation, market share gains and emerging markets.
Question 3: Can a declining industry still produce good investment returns?
Absolutely.
That is what the tobacco history teaches us.
The winning formula is potentially:
Strong brands + pricing power + distribution moat + high cash generation + disciplined capital allocation + low valuation
That is much more important than simply asking whether industry volumes are rising.
Bottom Line
The global alcohol industry is not simply "dying."
It is splitting geographically and structurally.
The West may be entering the:
"Drink less" phase.
Parts of Southeast Asia are still in the:
"Drink more as incomes rise" phase.
And eventually, those emerging markets may also reach maturity.
The tobacco industry teaches us something even more important:
A declining industry does not automatically make a bad investment.
What matters is whether the remaining companies have:
pricing power + strong brands + distribution advantages + cash generation + sensible capital allocation + an attractive valuation.
That gives investors two very different opportunities to investigate today:
🥃 Diageo
Contrarian value + turnaround + global brands
🍺 Carlsberg Malaysia
Southeast Asian growth + premiumisation + regional Carlsberg-Sapporo platform
Neither is a recommendation.
Do your own due diligence.
The most important question is not:
"Is alcohol growing?"
It is:
"Where is alcohol still growing, where is it declining, which companies have the strongest competitive advantages, and what price am I paying for those future cash flows?"
That is the question that separates a good story from a good investment.
Until next time,
Ewen, The Deep Value Strategist
P.S. Looking for exposure to Penang Industrial Real Estate?
I advise high-net-worth individuals on acquiring industrial assets. Reply 'INDUSTRIAL' to see if we are a fit.
Welcome to visit our You tube channel : https://www.youtube.com/@DeepValueContrarian
Follow me on Facebook : https://www.facebook.com/Ask.Ewen/
Simplified Confidentiality Notice
This document is only for you. It’s private, confidential, and you are licensed to use it as a single subscriber only.
You cannot share it. Do not forward, copy, quote large sections of it, or distribute any part of this report, especially the specific investment recommendations.
If you share it, your subscription will be cancelled immediately. The company reserves the right to monitor electronic usage to ensure compliance. If you received this by mistake, please contact the administrators.
Disclaimer: The content of this newsletter is for general informational and reference purposes only, serving as a source for investment ideas, and does not constitute personal investment advice tailored to your individual financial situation or risk tolerance. All investments involve risk, and past performance is never a guarantee of future results; therefore, you are solely responsible for conducting your own thorough due diligence and must consult with a licensed investment or tax professional before making any investment decision.