
We'll talk about a new stock today, a small cap of $3B I discovered some days ago and dug enough to convince me there was something there: $SPT. The company seems to be really well positionned for the actual narratives (not AI though), and I think it has a big opportunity in the marketing/social media space where it operates.
Let's dig it.
[Sector]
Social medias. A crazy business born two decades ago which grew like only a few thought possible. And it's apparently not ready to stop as $SPT's team estimates their niche market to be around $120B by 2025.
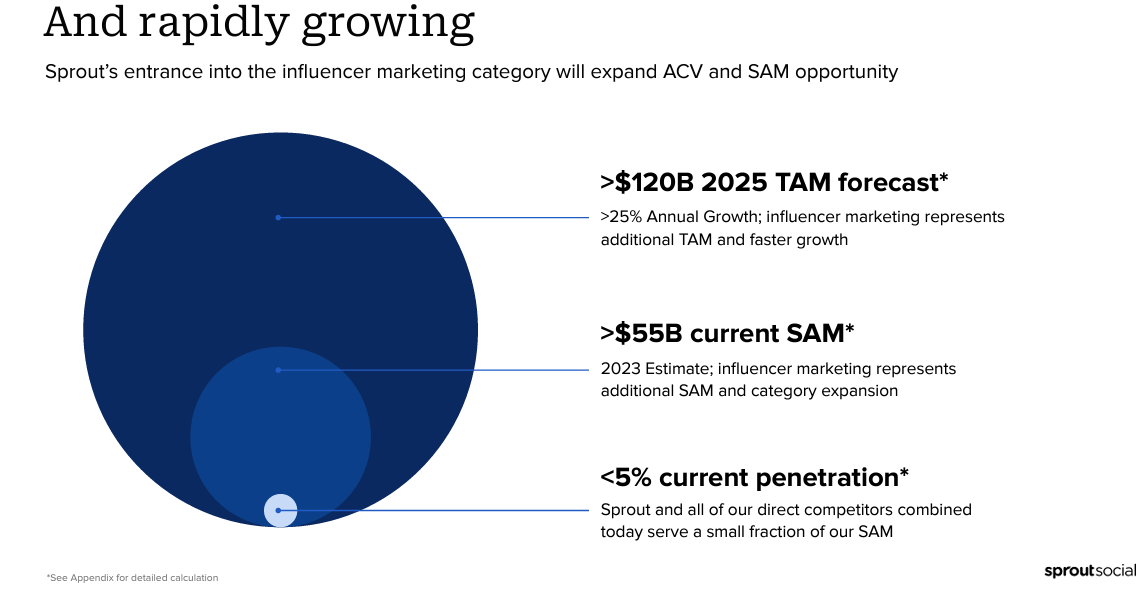
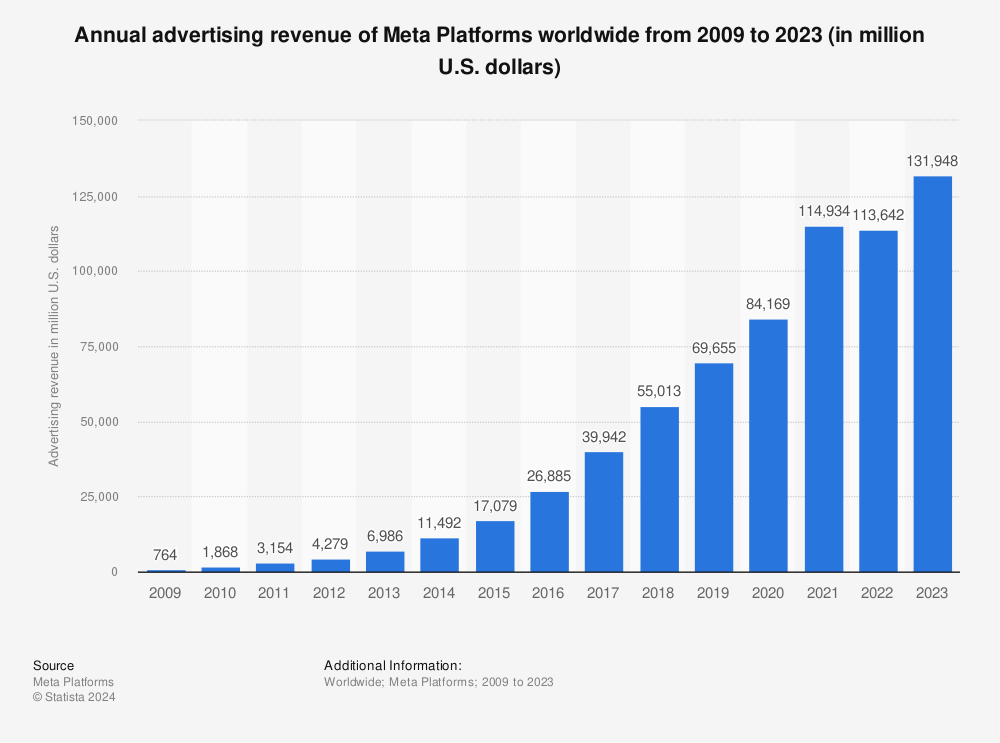
Lot of space, and I don't think the numbers to be that crazy. We just need to look at $META or $GOOG's revenues, for example, cumulating $420B together. Sprout estimates its own market to be less than 30% of the revenues of those two giants, not unreachable to my opinion.
[Business]
A pretty simple one, exactly as I like it. Which in their case will also be an issue, but we'll talk about it in the risks later on. Social media became a must-use tool for every company as it is where they target their consumers nowadays. We all saw ads on Facebook, Instagram, TikTok & X, and we know how well they can convert users. You just have to follow $META's earnings to see how demanded their advertising space is.
But companies have a problem, they have to be present everywhere, non-stop, and monitor everything - and god knows there are a lot of platforms to spend time on nowadays.
Enter $SPT, a centralized social media management platform. The concept is very simple, connect all your accounts and manage them all directly in one web app, from posts to private messages passing through data analysis & AI tools.
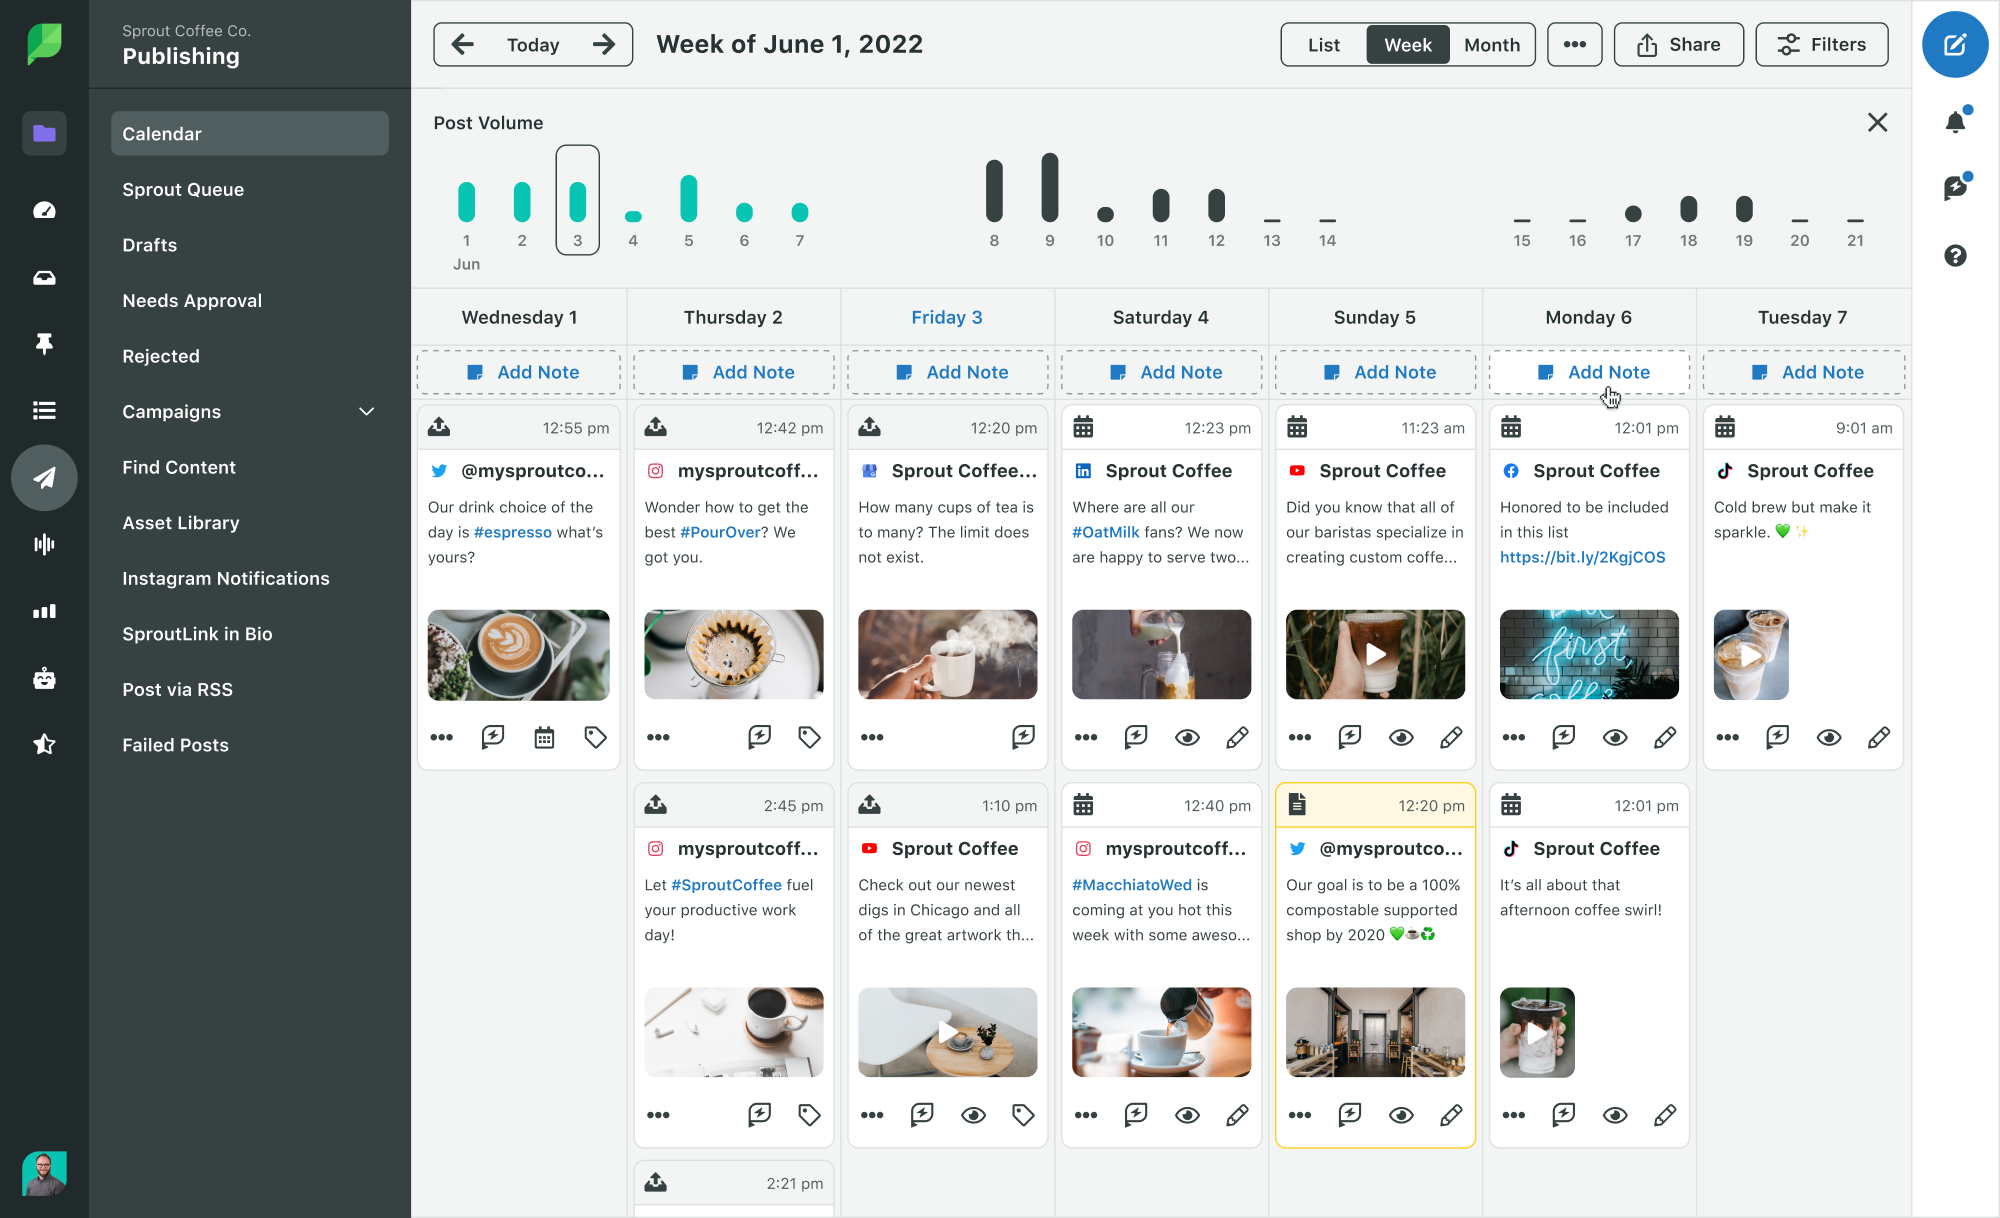
Simple & efficient.
Probably the dream for every community manager which now ends up having everything he needs on one platform. Add to it some team management functions, reviews, planning, some AI tools like automatic translations or data analysis about engagement and live tendencies and you're up with a pretty powerful tool helping you to engage easily with the highest efficiency.
It's complexe to detail all of their features but here's a sum up from $SPT's docs.
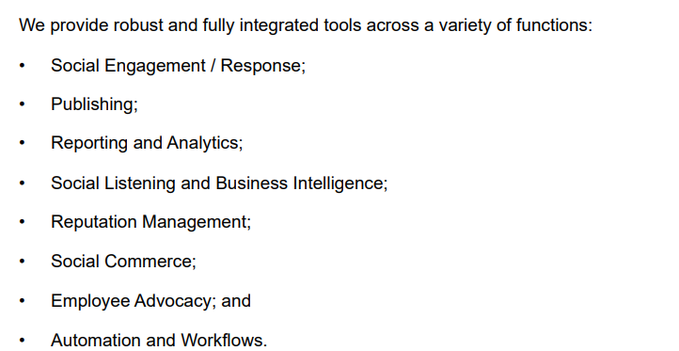
I'll let you try yourself as they have a free version, I did it and it does seem pretty powerful. A strong advantage against those who don't use equivalents. They said it best:
"The alternative is irrelevance"
And they're sadly entirely right... There's today no alternatives to advertise on social networks so it's adapt or die. And those doing it with the best tools will reach the most potential clients.
[How do they make money?]
We're with something simple once again: subscription per user & function. It's that easy.
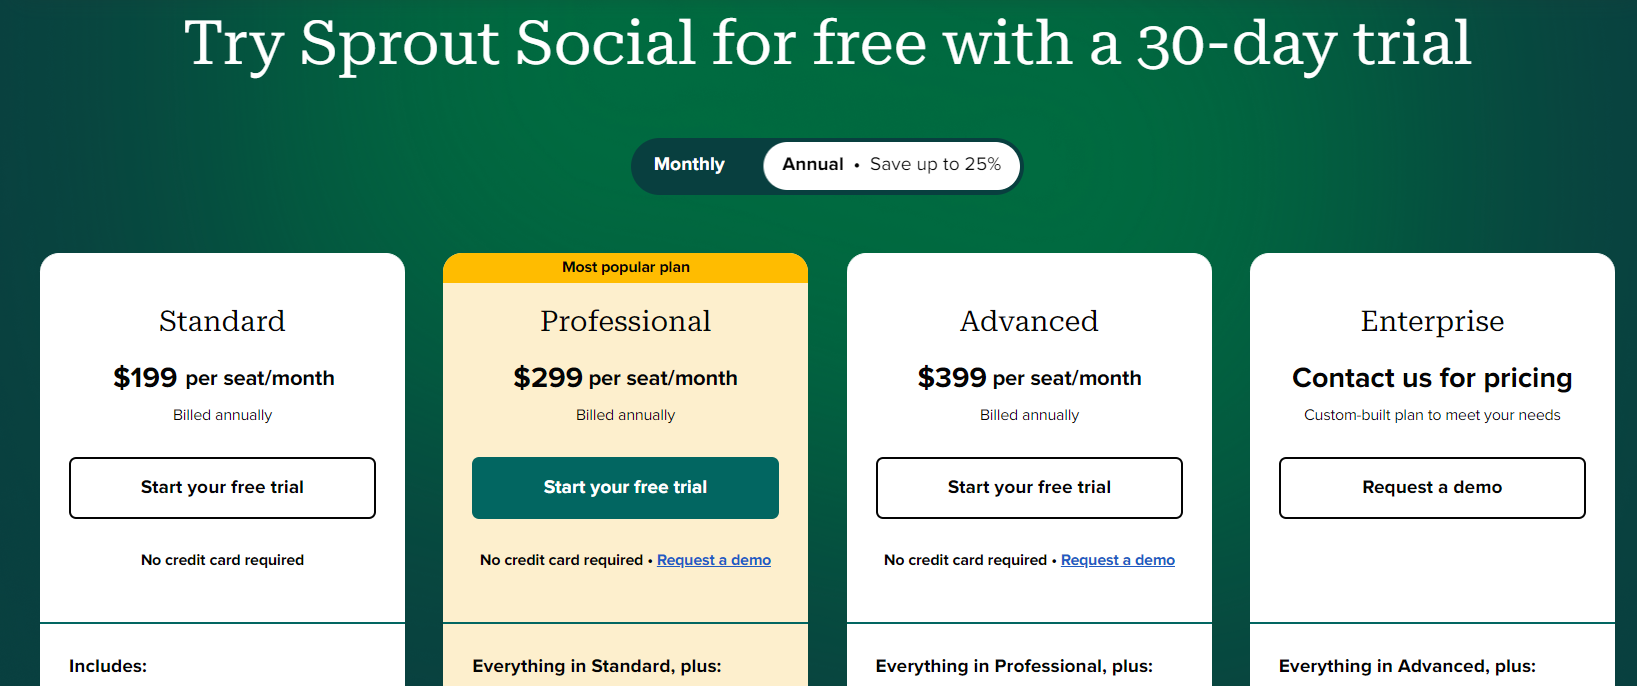
The go-to-market strategy is as simple and very standard for software comapny. A free demo where you can access the basic tools and contact the team to test the more complexe ones. You'll then need to pass on a paid subscription. Classic.
[Risks]
We're talking about software using different social networks APIs to connect themselves and give a feeling of simplicity to their users who'll be able to manage everything from one web app. The idea is great, but it's a bit limited and brings lots of risks.
Competition. Again, simple APIs connections so what differentiates one service from its competition? Hard to say, better interface, better pricing, simplicity...
Pricing seems to be the biggest factor which means most companies will probably have to fight each other, reducing margins.
Barriers. It kinda goes with competition, bit differently. Nothing prevents new players to come as the only requirement is to develop a nice software - except potential relationship with the social networks owners. And developping a good app isn't that easy, but still.
But there's something even more scary. What prevents app owners to develop their own internal tool, which could do the same? We know $META owns most of the important social networks, what if they were to propose an in-house tool to manage every account in your $META apps?
It wouldn't destroy their business entirely as there are more social networks. But it would damage it, very much. Although $META never expressed interest to do so, maintaining API is easier for them, easy money.
APIs owners. APIs are controlled by the company which posts the app, meaning they can cut, add or modify everything to their wish, reducing $SPT's offering in the meantime.
Once more, they probably have no interests in doing so as those APIs and data are sold to those companies, hence a very easy revenue stream for $META etc. Easier to just sell those than to develop more products.
Those are lots of risks but the tougher one for me is the lack of differentiation between those companies and the possibility that their subscription price is the only thing they can use to distinguish themselves from competition.
[The company]
Time to look into Sprout directly, their finances and business. I like to talk about Sprout as the crazy kid, the "home run or nothing kid" of companies, growth or nothing, take it all or go home.
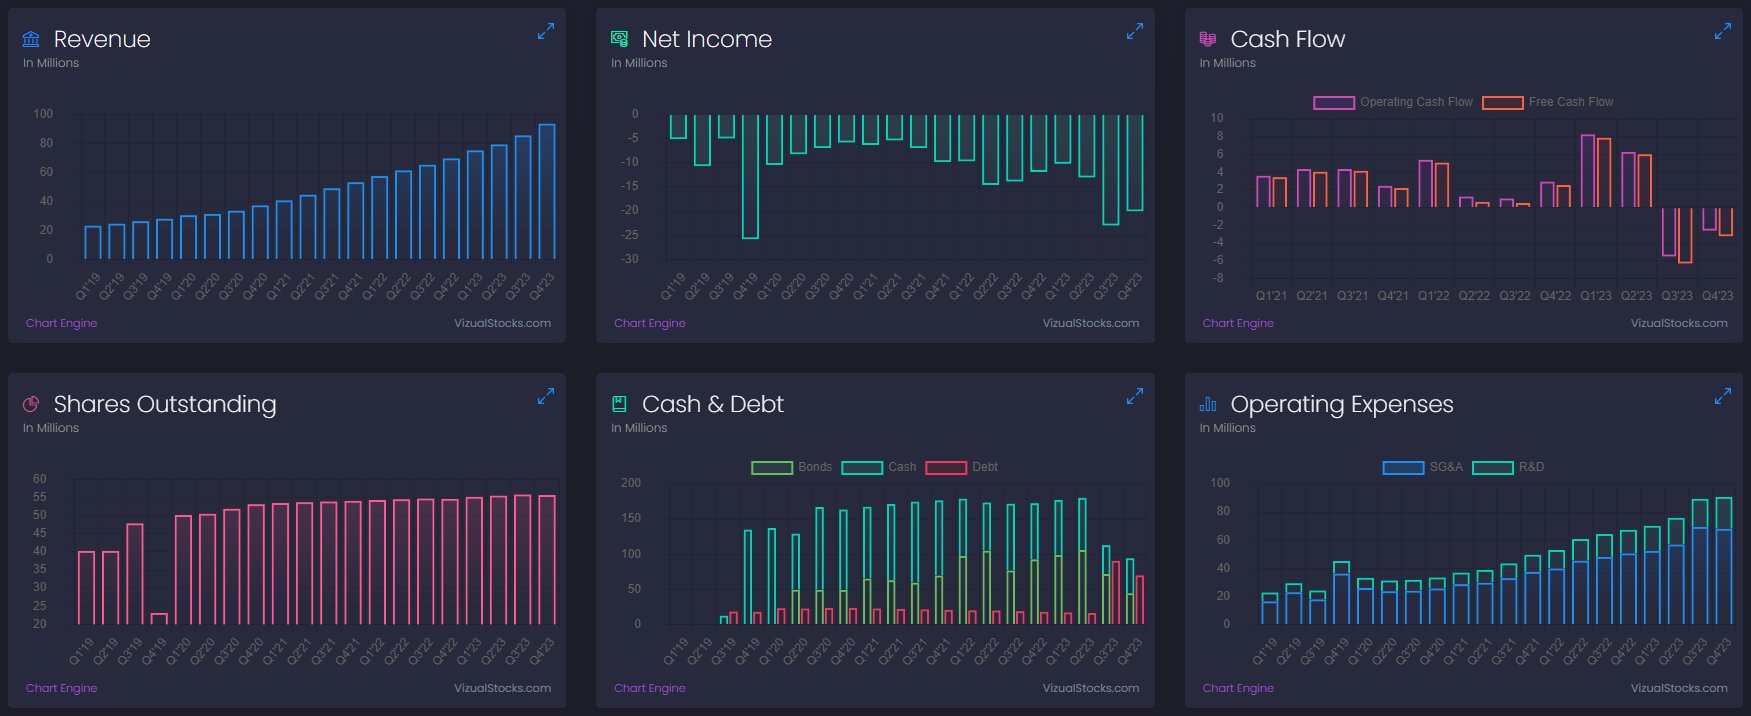
The data isn't that self-explanatory so we'll take a look around each of one by one. The company went public in December 2019 and has around 55.6M shares today.
Revenues. Let's start with the revenues which show pretty strong & impressive growth with FY-23 at $333.6M with a 5Y CAGR of 33.46%. Very, very strong and that is the most attractive data of the company.
Net income. Now it's pretty obvious that we're not with a profitable company here for good reasons, they're really focused on growth more than anything else and it shows on their expenses with R&D and marketing being 75% of their expenses.
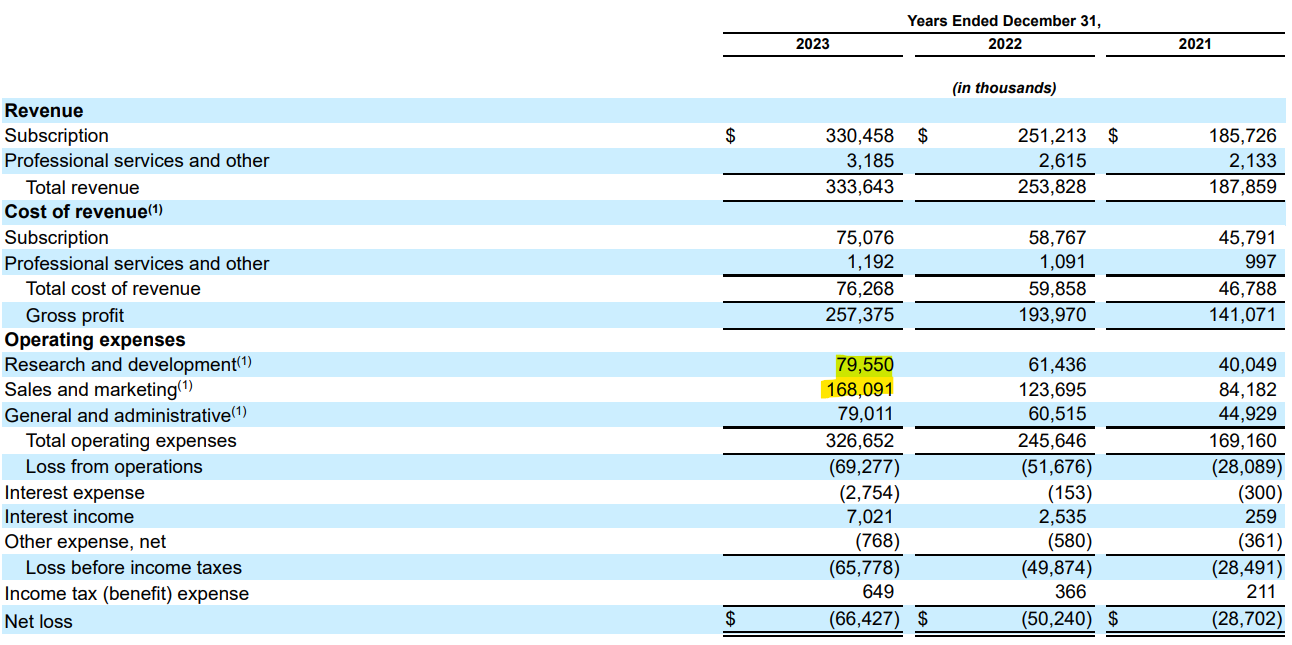
Take those away and you'll have a very profitable company with more than 75% gross margin, proper software margins.
You cannot of course suppress them entirely but those will be diminished once the company reaches a market penetration management will judge sufficient. What is important for today is that those expenses are translated into growth and that's not entirely the case yet as FY-22 expenses aren't entirely translated into FY-23 revenues.
As of today, the company spent $2.3 to bring $1 back, but that's considering 100% of those expenses which isn't really honest.
Another point is that the company is also guiding us through their objectives, we'll talk about them later.
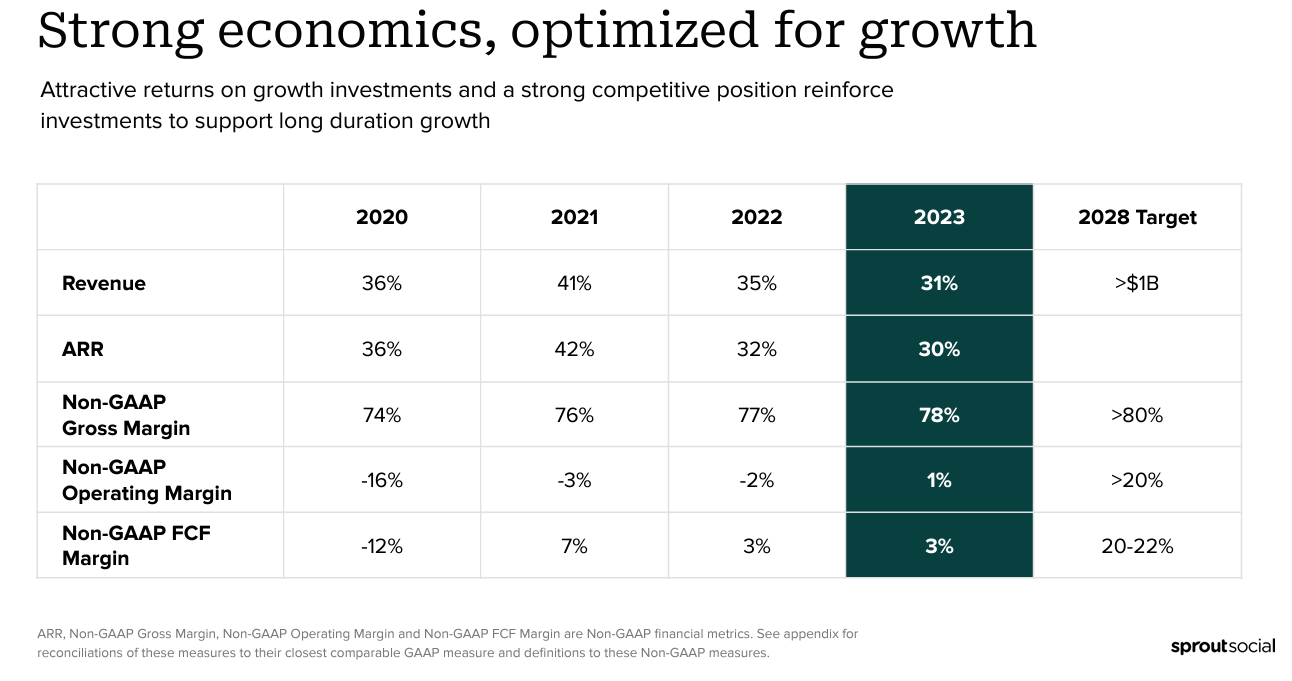
Simple math, reaching $1B in 2028 is achievable with a 31.5% CAGR. So they're on track if it all goes according to the plan. Agains, more on this later.
Cash flow & cash. Now to the FCF first which was always positive thanks to the share programs, that is how the company financed itself through the years, something which pleases me.
But we see that cash pocket dropping in 2023, along with the FCF while debt rose. That is due to two acquisitions the company has done this year.
- Tagger Media, an influencer marketing platform whose goal is to put in relation brands with influencers, giving a new arrow to Sprout's bow.
- Repustate, a data/AI company which Sprout now uses with its in-house product. I love a clean balance sheet, but I also love a growth company which uses its cash & debt leverage to grow faster, broader, and develop new products.
Business. In terms of clients, the company is also doing well.
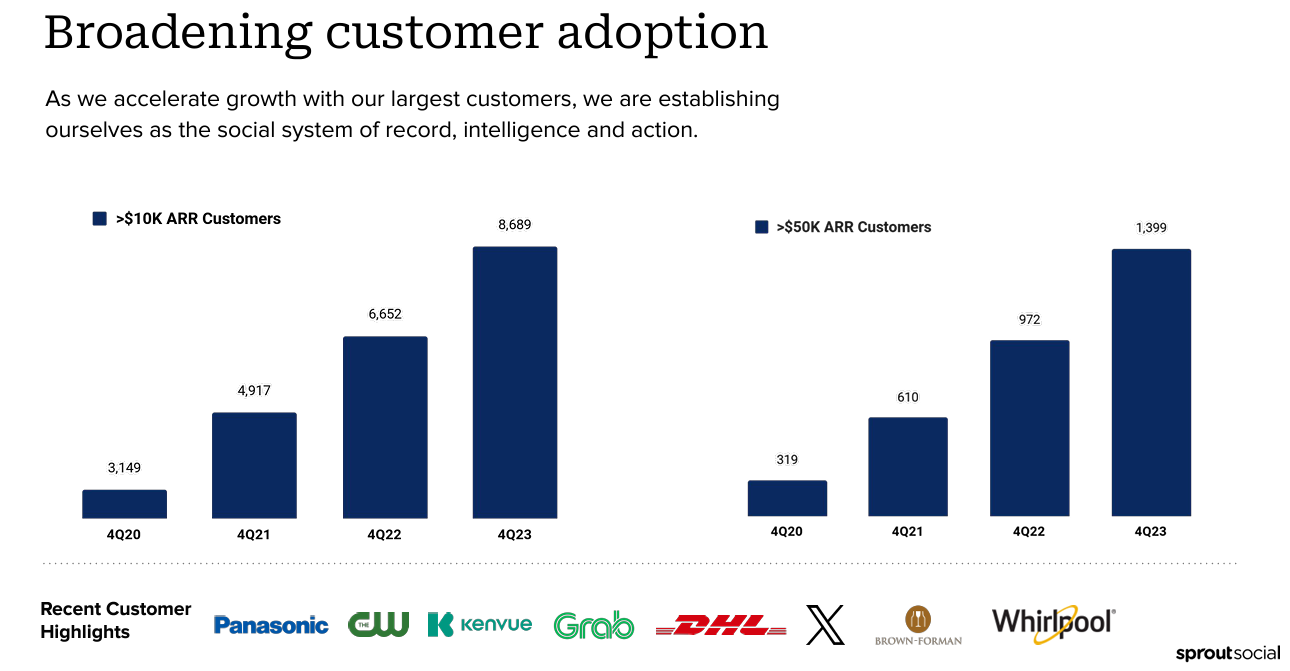
The data is self-explanatory although a bit strange as it shows clear growth while the 10-K shows that the company actually lost clients in FY-23 compared to FY-22.
I'll take the difference as the clients lost were not part of Pareto's 20%. If so, that's a good thing.
[Opportunity]
We're pretty far now on this post but this will be the last section, where I'll detail what I expect from $SPT going forward, acknowledging that those are only simplistic assumptions to have a rough idea. We cannot perfectly anticipate things, a broad idea of the potential is enough for me.
Some rough assumptions first.
1. The shares outstanding are staying flat over the next years. No emission, no buybacks.
2. The PER and P/S are calculated with the actual market capitalisation of the company, I'm trying to know how many years of growth I'd be buying at the actual price.
3. For information, I based myself on the software industry 10Y average PER and P/S to run my price estimations which stands at x48.6 and x7.7 as of today. The bull case use higher ratios due to stronger growth - which are still acceptable with the actual market.
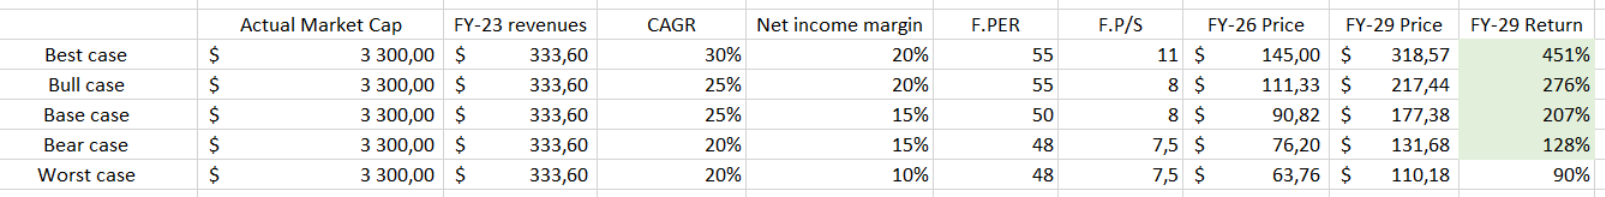
To give more clarity, it's interesting to know that the company itself guided to a low-end revenue of $425.3M for its FY-24 - being a 28% growth YoY - with profitability of $0.22 per share - roughly $12M of net revenues or 3% net margins.
Useless to say that the bear case is here only because it has to be but it isn't what I nor the company itself is expecting. The potential for it FY-26 is more likely around the bull case, although the net margin might not be at 20% in 2026 already but if growth is still above 25%, it shouldn't be a proble.
Strong potential.
[Conclusion]
Pretty long but I hope complete enough for you to have a good start to understand the company and do your own, deeper research on the product if you're interested.
I like a lot on this stock & company, my only concern is the competition and potential pricing war around their products which could change the thesis over time, but we're not there yet and we have to acknowledge the power and necessity of such tools for brands which rely on advertising. All of them.
The financial growth Sprout is fueling is very convincing. I'm now long on the company and will accumulate around $55 and under. It is meant to be a multi-year holding as long as things unfold nicely, meaning revenue gowth stays strong.