
Savers are Facing a Mighty Sword of Interest Rate Cuts, Again
Here's what you might do to duck under the blade.
Nov 03, 2025
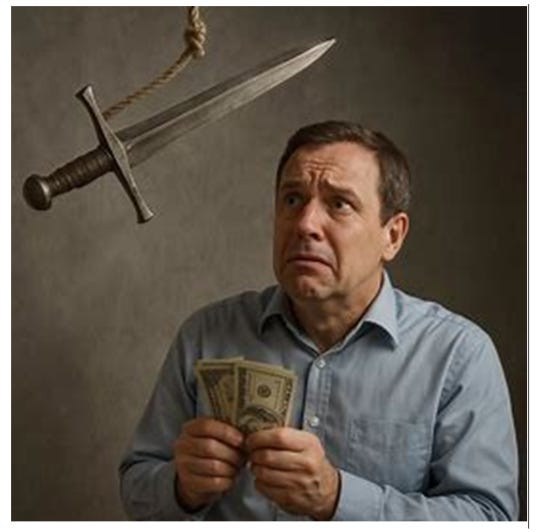
Remember just a few years back, when interest rates kept plunging and banks paid you next-to-nothing on your hard-earned deposits? Don’t look now, but we appear to be on that precipice once again. When the Federal Reserve meets next week, it’s almost a given that the Fed Chair, Jerome Powell, will cut the federal funds rate again by another .25%. And in the final meeting of the year, after that, another .25% cut is expected.
A safe way to hedge against this coming risk to your income
Imagine you’re the hero in a cartoon: you’re chilling in your savings castle, high-yield savings account by your side, when suddenly above your head dangles the ominous sword of Federal Reserve (the Fed) and its mighty rate-cut ax. The Fed is very likely to cut the federal funds rate by one-quarter of a percentage point (25 basis points) at its next meeting. That means the interest you get on your saved cash could start being trimmed. Meanwhile, on the other side of the castle your friendly dragon — call him “Old Age” — whispers that your Social Security benefits are only getting a 2.8 % boost in 2026. That’s not terrible, but when inflation is breathing down your neck, 2.8 % feels like a nibble on the tail rather than a fiery roar.
So our hero (that’s you) is stuck between the sword (rates falling) and the dragon (benefits growing slowly). What to do? Well, the good news is: you can make a smart move to try to get ahead of the curve.
Here’s the suggestion: take some of your free cash (the money you don’t need right away) that’s sitting in a high-yield savings account (maybe yielding 4% or something) and shift a portion of it into a longer-dated Certificate of Deposit (CD) — say for 9 months to a year. By doing this you can lock in a fixed rate today. If the Fed cuts rates and everything else drops, you’re sort of insulated because your rate is locked. It’s like putting on armor while the sword is swinging.
Retirement: One Dividend at a Time is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.
Why this is smart:
CDs are FDIC-insured (so your money is safe up to the limits).
If you pick a term like 9–12 months, you’re not stuck for five years; you’re making a short-to-medium term bet.
You lock in a rate now rather than seeing your high-yield savings account slowly slide downward when the Fed cuts.
It gives your portfolio a more stable anchor in this uncertain time.
Let’s pick two example banks:
Barclays Bank US: They currently list “Select CDs” with rates up to about 4.30% APY. Barclays Banking+1
First Foundation Bank (now merging with FirstSun Capital): They list online CD products, for example a 4-month CD at about 4.00% APY. openaccount.firstfoundationinc.com+1
Okay, so maybe it’s not exactly 4.50% or more everywhere, but it’s in the ballpark of 4% or slightly higher which is pretty decent given the circumstances.
Here are some tips if you go this route:
Make sure you’re comfortable not needing that cash for the term of the CD — if you break it early there may be a penalty.
Keep some cash liquid (emergency fund) in a high-yield savings account (so you’re not locked out of everything).
Check the bank’s conditions: minimum deposit, any restrictions, FDIC-insurance limits.
Think of it as one piece of your portfolio: you’re not putting all your cash into one CD, just a portion to get some stability.
As the CD matures (say in 9–12 months), you can reassess: if rates have dropped, great — you locked in a good rate for the past several months; if rates stayed high (less likely), you can reinvest or ladder.
In short: yes, the sword of rate cuts is swinging, and yes, benefits are only creeping up slowly (hello 2.8%!). That means if you sit still you might get squeezed.
created with Bing Image Creator
But by taking a small proactive step — shifting some free cash into a decent-yield CD now — you can batten down the hatches, lock in a better rate while you can, and give your portfolio a steadier base. Think of it as building a mini-fortress in your portfolio castle.
Here are some recent FDIC-insured CD rate offers that could help you lock in something in the ~4.2 %-4.5 % ballpark (or as close as one can currently find) for short-term (~9 months to 1 year) money. As always, check each bank’s details (minimum deposit, term, early withdrawal penalty, etc.). Because of the looming cut by the Federal Reserve, these may move lower — so using them sooner rather than later may make sense.
If you use my special referral link when you open a CD with Marcus by Goldman and you can receive an extra .25% (4.10%+.25%= 4.35%)
If you use my special referral link you can receive an extra .25% (4.10%+.25%= 4.35%)
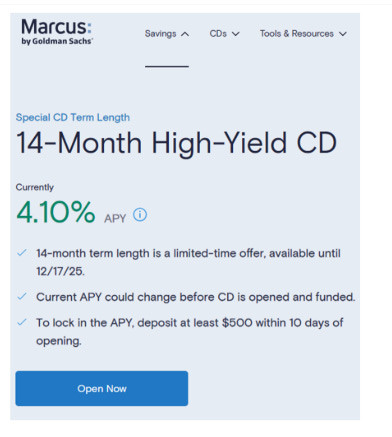
source: Marucs by Goldman
✔- Other Current CD Offers
At a recent snapshot (Oct. 26, 2025), one bank offered 4.34% APY for a 6-month CD from Climate First Bank (minimum deposit ~$500). The Motley Fool
In the same update: a 9-month CD from OMB Bank paying ~4.15% APY (term: 9 months, min ~$1,000) The Motley Fool
A summary of “Best One-Year CD Rates” shows that 1-year APYs around 4.10% to 4.25% are available from good online banks. finder.com+1
A listing from earlier in the year (April 2025) showed some short-term CDs (6–10 months) paying 4.50%+ APY in some cases. The Motley Fool
Notes & Things to Watch
“Short-term” here means roughly 6 to 12 months. Many currently available offers are slightly lower (4.10–4.34%) on the terms listed. The higher 4.50%+ offers may require very specific banks/terms and may vanish quickly.
Make sure:
The bank is indeed FDIC insured (so your deposit up to $250,000 is protected).
The term (9–12 months) matches your comfort level (you are comfortable leaving the money locked).
Understand early withdrawal penalties (if you break the CD you might lose interest or part of principal).
Minimum deposit requirement and whether the offer is restricted (e.g., only online, new customers, etc.).
Because the Fed is expected to cut rates, savings yields and CD offers may drift downward — meaning locking in soon gives you “rate insurance” to some extent.
Here are a few more sources with current rate offerings for you to consider:
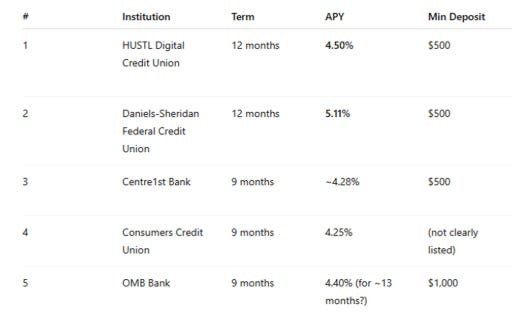
source: table by author
So sharpen your financial sword (not the big one) and duck under the main blade. Your future self (and maybe your older self) will thank you.
Retirement: One Dividend at a Time is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.
Best,
the author
George Schneider, M.A.
Founder and publisher
Retirement: One Dividend At A Time
Disclaimer: This article is intended to provide information to interested parties. As I have no knowledge of individual investor circumstances, goals, and/or portfolio concentration or diversification, readers are expected to complete their own due diligence before purchasing any stocks mentioned or recommended.
Disclosure: I am long all RODAT Portfolio names. The Portfolio continues to build dividend income with reliable, dependable equities which have long histories of increasing the dividend.
Copyright ©2025, George Schneider, M.A.