
 # BINKY DISPATCH™ — Into CPI: Swept Both Ways, Ghosts Overnight
Oct 13, 2026 · @BinkyGTTT
BINKY OF KY™ | Independent market research and education
Edition: Tuesday, October 13 New York close → Wednesday, October 14 Asia open and the September CPI
Posture: Respect the sweeps. Let the print speak first, then let the tape tell you whether it believed it.
> My read: Tuesday was a day of breakouts and breakdowns that never got follow-through. NQ swept the overnight low at the open, faded all morning, refused to make a lower low, leaned on a lid all afternoon, and never cleared it.
Then the evening session ran the same movie twice more: a wash into the Asia low on the Saudi headlines, and a poke over the Asia high that got sold. We head into CPI with both edges of the overnight range already tested, the long end of the curve sitting near 5.2% on the 10-year, the banks telling us rates are starting to bite, and a few ghosts walking the halls overseas....
## 🎪 The tape: three sweeps and a lid
The cash Nasdaq 100 finished down 0.31% and was red the whole session. The S&P 500 finished flat. The Dow lost 0.35% and the Russell 2000 lost 0.40%. Those numbers make it sound like a quiet day. The NQ tape was anything but.
The morning. The overnight low was 30,606.75. The open swept it to around 30,590 and turned hard, a 160-point reversal bar. By mid-morning the short side looked clean again, with a run of lower highs on the 15-minute and a pullback into the 30,700–30,720 shelf. The 15-minute close under 30,700 came late morning, and the retest of the overnight low never did. Price stalled near 30,640 right as Europe closed at 11:30.
The afternoon. The lows kept climbing: 30,590, then 30,640, then 30,688. Each push down covered less ground than the one before. The sellers were getting tired (or appeared to be). The longs weren't getting paid either. The tape kept printing breakouts, and setups for breakouts, that never followed through. Into the close it leaned on the flat top at 30,808–30,815 and never cleared it.
The evening. The first push through that lid came after the reopen, around 18:40, and it didn't hold. Price slid back under within half an hour, then washed out to the Asia low at 30,744.50 right around the Houthi-Aramco headlines. From there it ripped to 30,837.75 in about forty minutes, poked to around 30,850 near 20:40, got sold, and flushed to about 30,805 by 20:48.
That's sweep-and-reverse three times in about twelve hours. The fast timeframes rolled over at the top of the Asia range; the middle timeframes haven't followed yet. I'm treating that disagreement as information, not noise.
The Carnival loves a rerun. Every false start costs a little time, a little patience and a little conviction. Theta Gangsta calls it Tuesday.
## 🏦 The banks: the desks got paid, the lenders sent a warning
Four of the big five reported Tuesday. Profits were strong across the board. The commentary was the part worth reading twice.
| Bank | What came in | What stood out | Stock on the day |
| --- | --- | --- | --- |
| Goldman Sachs | EPS $17.01 vs. about $13.65 expected; revenue $18.68B vs. about $17.03B | Equities revenue $6.44B, up 72%; record advisory; but the investment banking backlog slipped from Q2 | Higher |
| JPMorgan Chase | Net income $15.3B, a rare miss on EPS and revenue | Fixed income trading down 4%, its first decline in more than two years; equities up 49%; deal activity slowed in late September as rates sold off | Roughly flat |
| Citigroup | Profit up about 40% from a year ago, ahead of estimates | Investment banking and wealth up; card profits flat | Down about 0.7% |
| Wells Fargo | Profit $5.95B, $1.87 a share, ahead of estimates | Steady climb since the asset cap came off | Down, 1.5%–3% depending on the hour |
Here's the part that matters for Wednesday. Jamie Dimon said the economy is still running on strong business investment, then listed what's shifting underneath it: fiscal deficits, persistent inflation, high asset prices and rising rates. He added that stress could come from overseas. JPMorgan's CFO called the consumer healthy, mostly because the labor market is, and warned that aggressive tightening would likely raise unemployment and weaken credit. He also flagged energy costs and higher rates straining some commercial and real estate borrowers.
Read that next to the trading lines. Equities desks had a monster quarter. Fixed income at the biggest bank in the country went backwards, and deals paused when the long end sold off in September. When the bond market moves, the dealmakers stop and wait. That's the transmission line from the 30-year yield into the real economy, and the banks just described it in their own words.
Morgan Stanley reports Wednesday around 7:30 ET, an hour before CPI.
## 👻 The overnight ghosts
### 🛢️ War and oil: the loudest Ghosts in the house
Houthi missiles hit Aramco's headquarters in Dhahran on Tuesday. The fire is out; the damage isn't clear yet. That came after strikes on Riyadh's airport over the weekend that killed at least 13 people, and after Saudi-led strikes on an oil site in Sanaa. Several major airlines have suspended flights to Saudi Arabia.
Bigger than that: Axios reports Netanyahu and Trump discussed a major joint operation against Iran's military and nuclear targets before Israel votes on October 27 and the U.S. votes on November 3. The White House calls the reports false and says there will be no attack before the midterms. Trump also said Tuesday that a decision on Iran is coming "very soon." Qatari mediators are still waiting on Iran's answer to the latest U.S. offer.
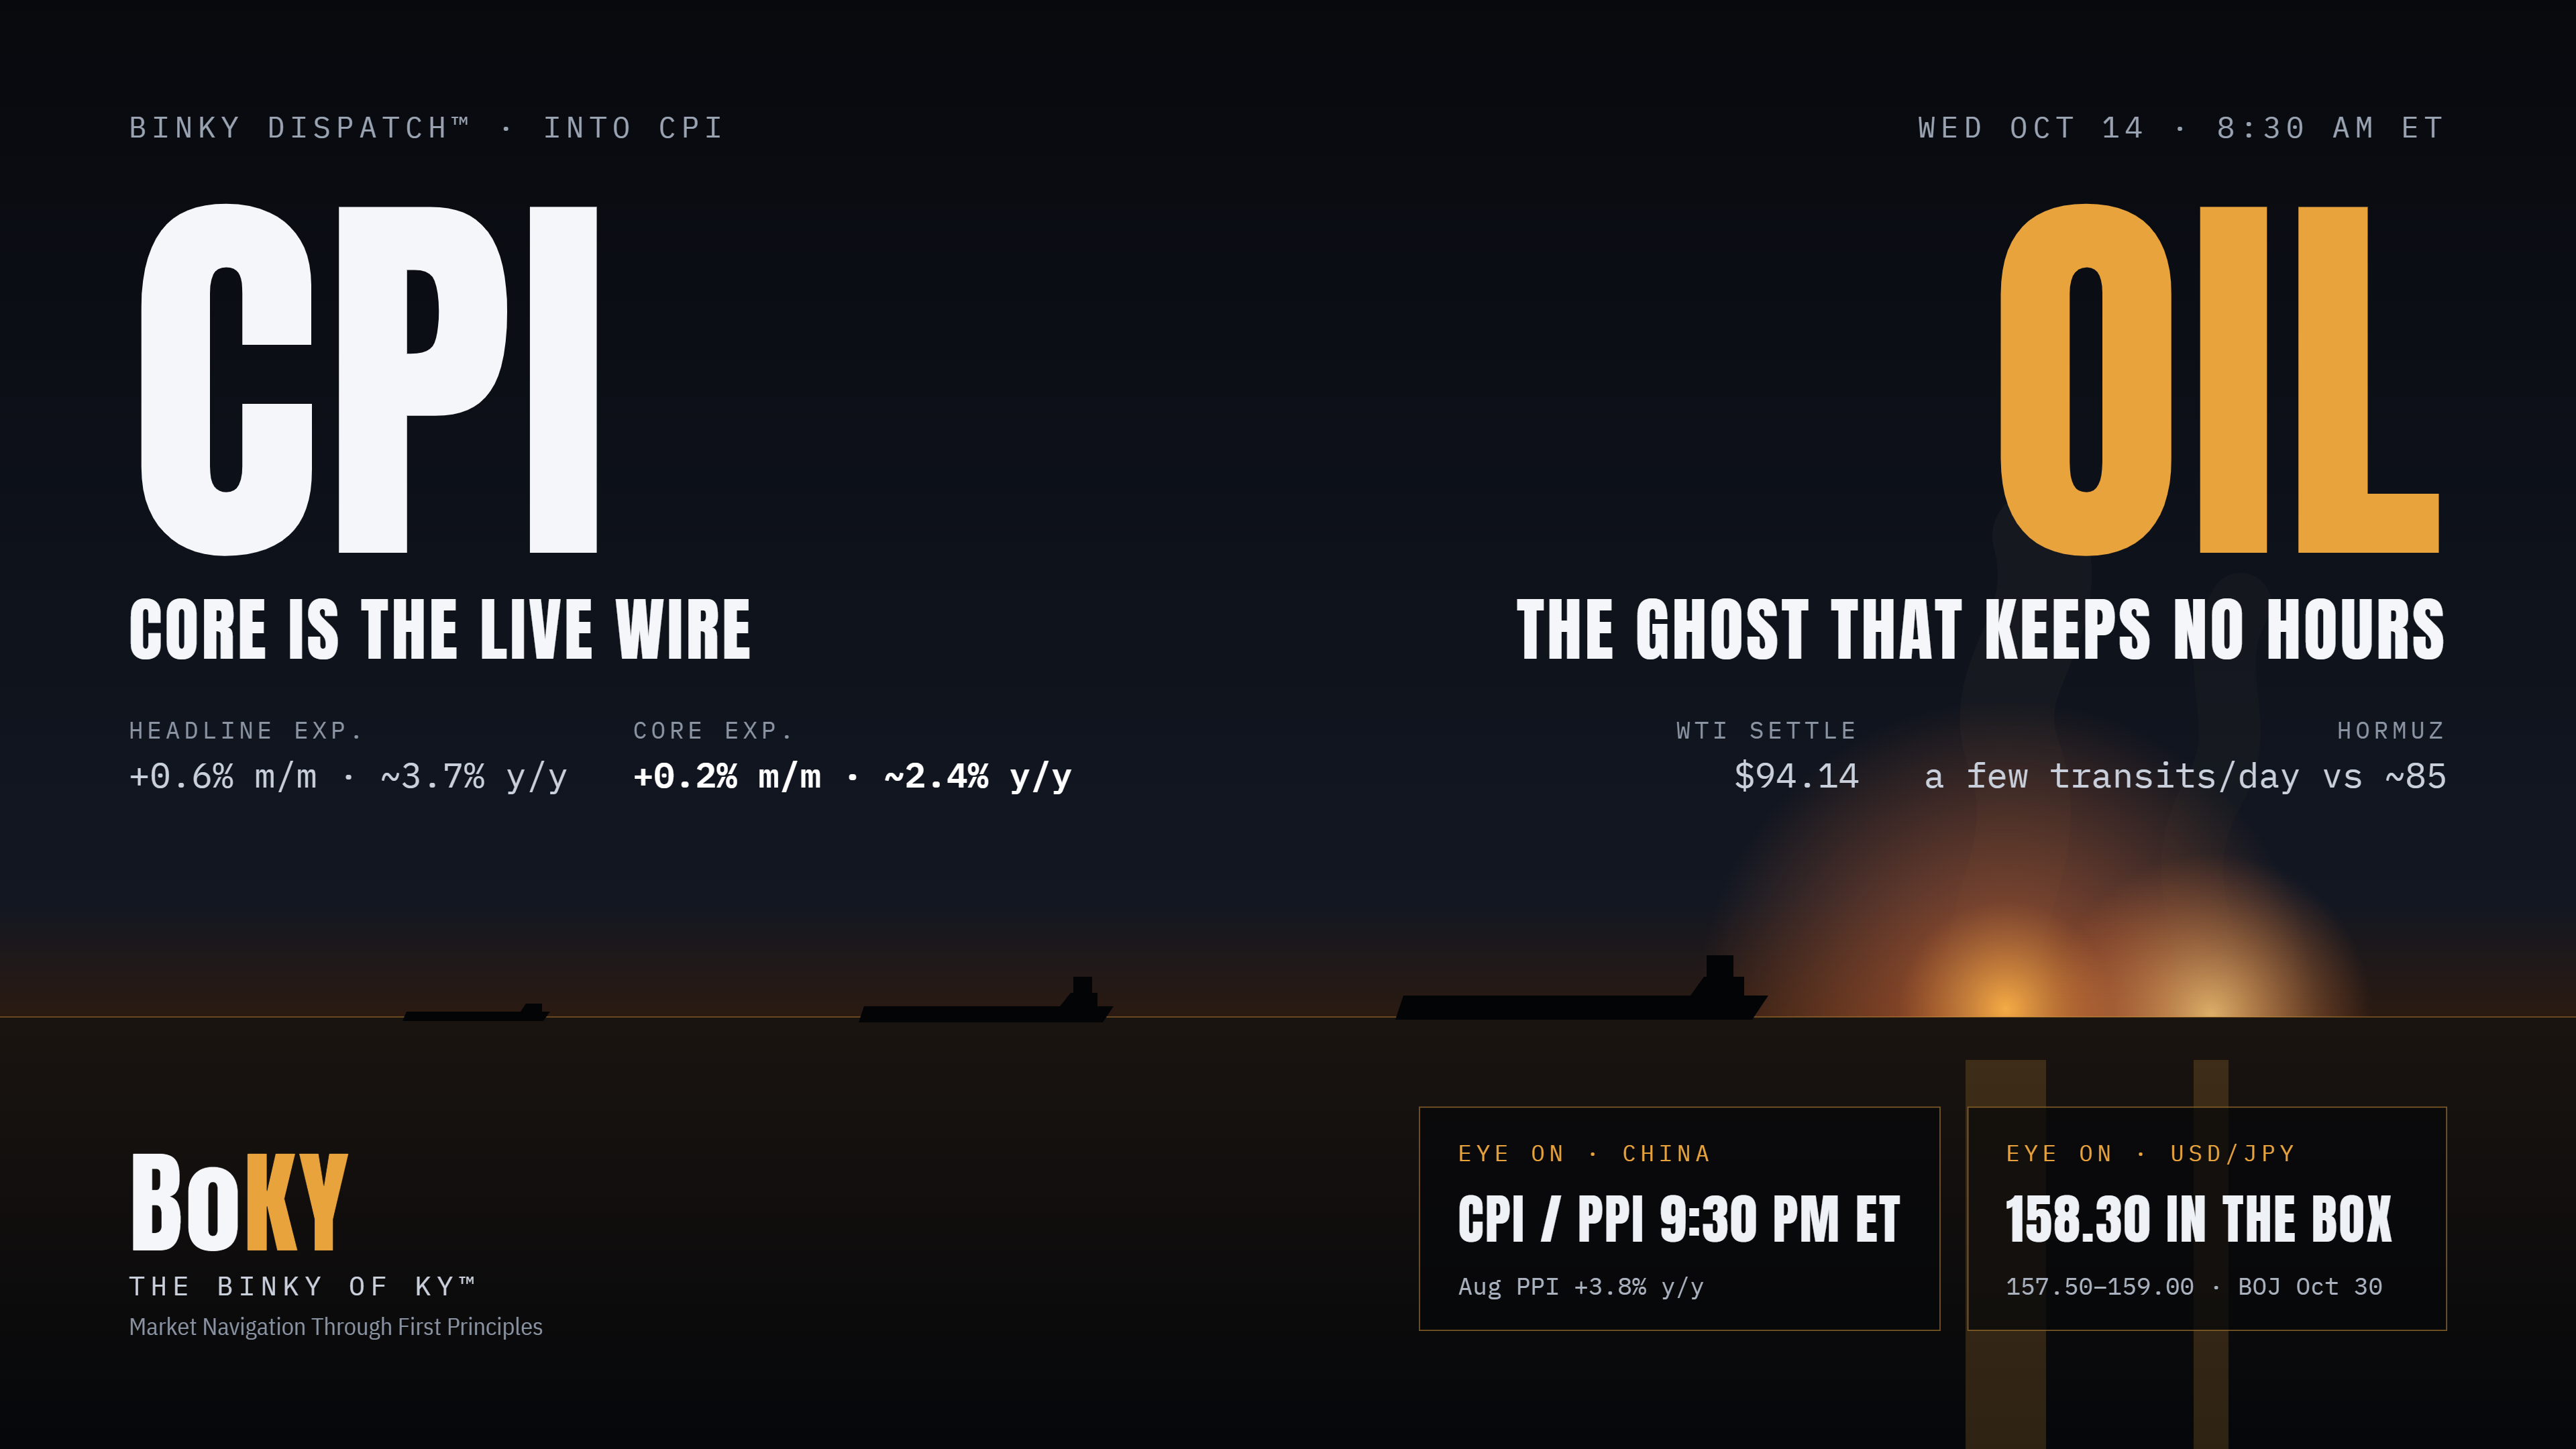
Meanwhile Hormuz is barely moving. Early October saw a handful of transits a day against a pre-crisis baseline of about 85, and roughly nine ships were struck in the first week of the month. WTI settled at $94.14 Tuesday and was bid near $95 in the evening. Brent was around $104 late last week.
Oil is the fastest route back into inflation, policy and the long end. It's also the one ghost that doesn't keep office hours.
### 🇯🇵 Japan: the BOJ blinks, the MOF is in the room
The Bank of Japan took its rate to 1.25% on September 18. Bloomberg reports officials now lean toward skipping a second straight hike on October 30 and keeping December open; swaps price about a 10% chance for October and close to 90% by December. USD/JPY has lived inside roughly 157.50–159.00 since October 5 and sat near 158.30 Tuesday.
Here's the wrinkle. Finance Minister Katayama and Treasury Secretary Bessent are both in Bangkok for the IMF meetings through Saturday. The last time the two countries bought yen together was July 31, with USD/JPY near 164. A Bank of Japan survey out Tuesday showed households expecting prices to rise 11.8% over the next year. The rate gap between U.S. and Japanese 10-years is still about 2.2 points.
A BOJ that waits keeps the carry trade comfortable. An MOF that acts while its counterpart is in the same building is how a quiet box turns into a fast move....
### 🇨🇳 China: the data lands tonight
September CPI and PPI are due at 9:30 p.m. ET, with trade data to follow. In August, consumer prices ran 0.8% year over year and producer prices 3.8%, and exports were up 18.6% in yuan terms. China's factory-gate prices are rising again. That matters for anyone counting on imported goods to cool U.S. inflation.
## 📈 CPI: the headline is spoken for, core is the live wire
September CPI lands at 8:30 ET Wednesday.
| Measure | Expected m/m | Expected y/y | August |
| --- | --- | --- | --- |
| Headline | +0.6% | about 3.7% | +0.4% m/m, 3.4% y/y |
| Core | +0.2% | about 2.4% | +0.3% m/m, 2.4% y/y |
The Cleveland Fed's nowcast sits close to the Street at 0.53% headline and 0.20% core.
The headline jump is mostly gasoline. September averaged a record $4.33 a gallon, and everybody already knows it. The market will look straight through that to core, and to anything that shows energy leaking into the rest of the basket: airfares, shipping, transport services.
That matters more than usual because the Fed is already tightening. Fed funds sit at 3.75–4.00%. On Tuesday, Boston's Collins and New York's Williams both backed one more hike this year. Williams said he sees no need for another in 2027; Collins pointed at AI and data-center spending, tariffs and Middle East energy costs as reasons inflation could stick. A soft core gives them room to wait. A firm one pulls the hike forward and hands the long end a reason to reprice.
The long end is where this lands. The 10-year closed near 5.22% and the 30-year near 5.57%, both about 3 basis points lower on the day, while the 2-year was flat near 4.80%. That flattening was the bond market leaning toward patience. CPI decides whether it keeps leaning.
## 🧭 The map for Wednesday
NQ futures levels that matter: overhead, the 30,812–30,816 shelf that turned the last bounce away, then 30,826–30,836, then the swept high near 30,850, then the gap up toward Monday's 30,898.25 settle. Below, the 30,805 flush low, the Asia low at 30,744.50, and the 30,700 shelf.
### 🟢 State A: core comes in at 0.2%, headline in line
What it looks like: The print reads as an energy story and nothing more. The long end keeps Tuesday's rally. Hike pricing stays parked for later in the year.
What it means: NQ gets a shot at reclaiming the swept high near 30,850 and working into the gap toward 30,898.
What breaks it: Oil spiking on a hard headline overnight, or USD/JPY breaking out of its box.
### 🔴 State B: core at 0.3% or hotter
What it looks like: Hike pricing pulls forward. The 10-year and 30-year back up. The dollar firms and USD/JPY presses the top of its range.
What it means: The 30,744.50 Asia low and the 30,700 shelf come back into play. The bank warnings about rates biting become the trade.
What breaks it: The long end refusing to sell off on the number.
### 🟡 State C: a ghost shows up before the print
What it looks like: A Saudi, Iran or MOF headline hits during Asia or London, and oil or the yen moves first.
What it means: The overnight range becomes the tape that matters. CPI gets traded through whatever the headline already did.
What breaks it: A quiet Asia session with crude held under about $95.
## ⏱️ The clocks that matter (ET)
| When | What | What to watch |
| --- | --- | --- |
| Tue 9:30 p.m. | China September CPI and PPI; trade data to follow | Factory-gate prices still climbing |
| Overnight | Tokyo session; IMF meetings in Bangkok | USD/JPY leaving the 157.50–159.00 box, especially a fast drop |
| Overnight | Gulf headlines | Crude through about $95–96 while NQ fails under the Asia high |
| Wed \~3:00 a.m. | London core | First real test of Tuesday's long-end rally |
| Wed \~7:30 a.m. | Morgan Stanley earnings | Whether its desks match Goldman's or JPMorgan's story |
| Wed 8:30 a.m. | September CPI | Core m/m, and any energy leaking into services |
| Wed 9:30 a.m. | Cash open | Whether the first move after the print follows through or gets swept |
| Wed 2:00 p.m. | Fed Beige Book | Districts on prices, energy pass-through and hiring |
| Thu 8:30 a.m. | PPI and retail sales | The second inflation read and the consumer |
| Fri | Fed Chair Warsh speaks | How the chair frames the hike debate |
Further out: Israel votes October 27, the BOJ meets October 30, and the U.S. votes November 3.
## 🦶 Bottom line
Tuesday swept both ends of the book and paid almost nobody who chased. The banks told us the desks are printing money while higher rates start to lean on deals, borrowers and deposits. Overseas, the Gulf is on fire in places, Washington and Jerusalem are talking about a second round with Iran, and Japan's finance minister is sharing a building with our Treasury Secretary while the yen sits in a box.
Into that, the CPI print arrives with the headline already spoken for. Core is the number. The first move after it is the second number, because today taught us the first move doesn't always get paid.
When the triggers keep firing and the follow-through keeps not showing up, stop grading each trigger and start reading the sequence....
> Hedge the Sasquatch: Respect the sweep. Wait for the close. Keep a life preserver for the boat next door.
Questions, pushback, your own read of the overnight? Drop them in the replies or DM me. I read every one.
Buy my bots a bourbon. 🥃
## Sources
Traders in many timezones. Bloomberg (via FXStreet), Axios, Al Jazeera, World Oil, Fortune, 24/7 Wall St., Quartz, Investing.com, investingLive, Admiral Markets, Straits.live (IMF PortWatch data), GlobeNewswire.
---
BINKY OF KY™ — Market Navigation Through First Principles
Never Financial Advice. This is educational and informational research, not investment, legal, tax, or financial advice, or a recommendation to buy or sell any security. Markets involve substantial risk, including loss of principal. Verify data, use a written risk plan, and consult qualified professionals as appropriate. Past performance and historical patterns do not predict future results.