
Just spitballing with Gemini + GPT on FRMI - - no format just thrown together some thoughts... all eyes on Rick Perry landing a deal... will add and edit on the go
Fermi America (FRMI): The “Behind-the-Meter” AI Power Play
The Core Idea
Fermi America is not selling electricity.
They are selling time, certainty, and scale in an era where power — not GPUs — is the bottleneck for AI.
The company’s strategy is simple but extremely rare:
build massive, private, behind-the-meter power plants (gas → nuclear) directly next to hyperscale AI data centers, bypassing the public grid entirely.
In a world where grid interconnection now takes 5–8 years, Fermi’s value proposition is the ability to deliver gigawatt-scale power in months, not years
Hyperscalers need power and land, fermi lets them rent the land to use the power.. they’re the landlord
What “Behind-the-Meter” Actually Means
Fermi builds power on the same side of the meter as the data center:
On-site natural gas turbines today
On-site nuclear (AP1000s) later
Private wires, private cooling, private control
This completely bypasses ERCOT and the public utility grid.
Why it matters:
Hyperscalers are no longer power-constrained by capital — they’re constrained by interconnection queues, permitting delays, and transmission build-outs. Fermi collapses that entire timeline.
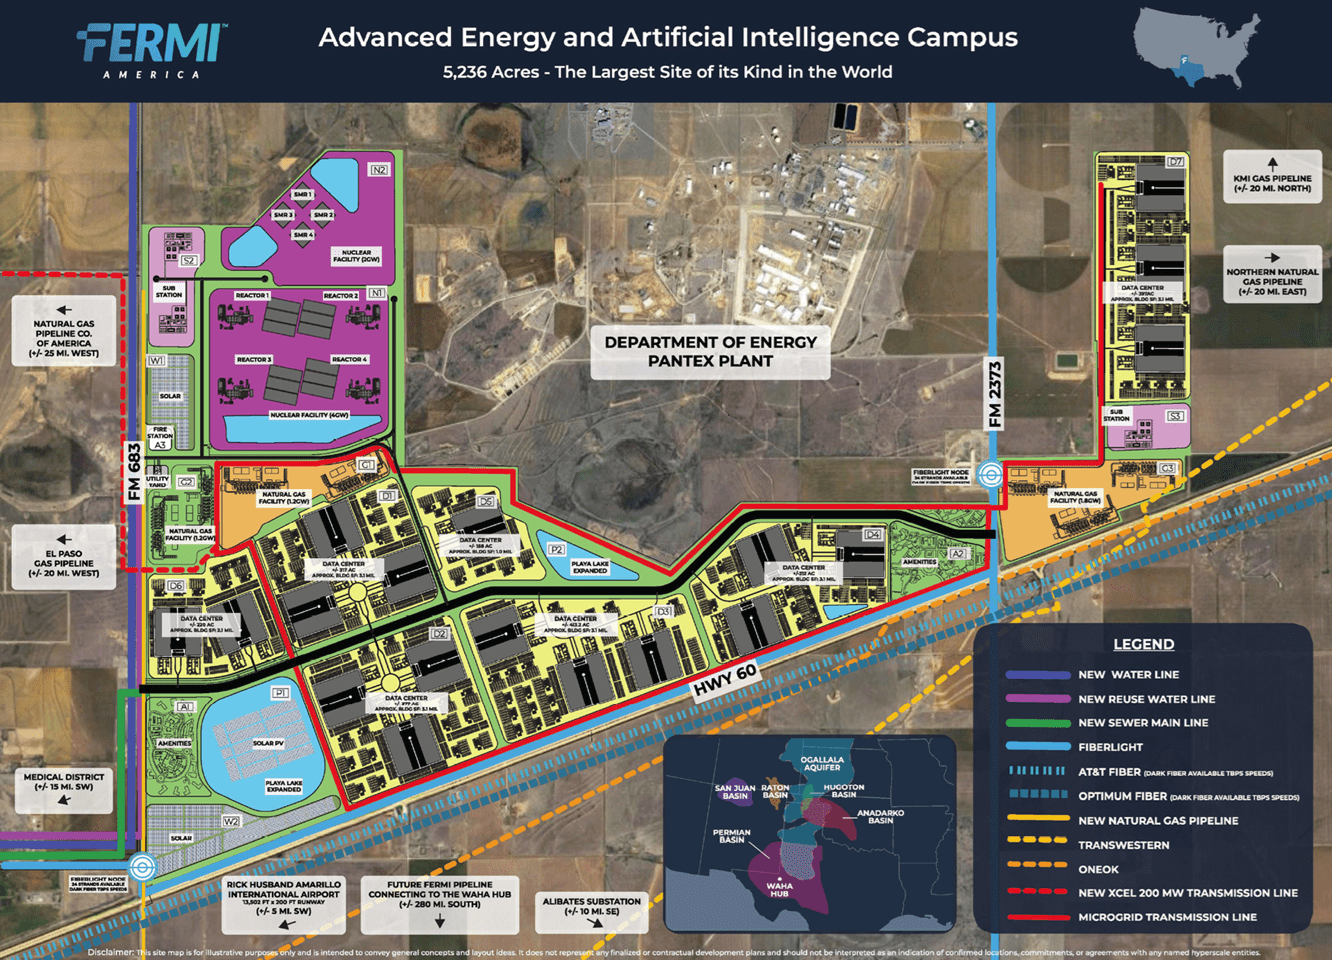
Project Matador: The Physical Asset
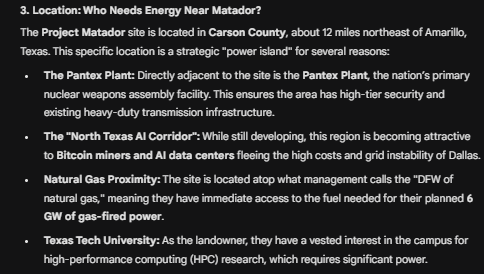
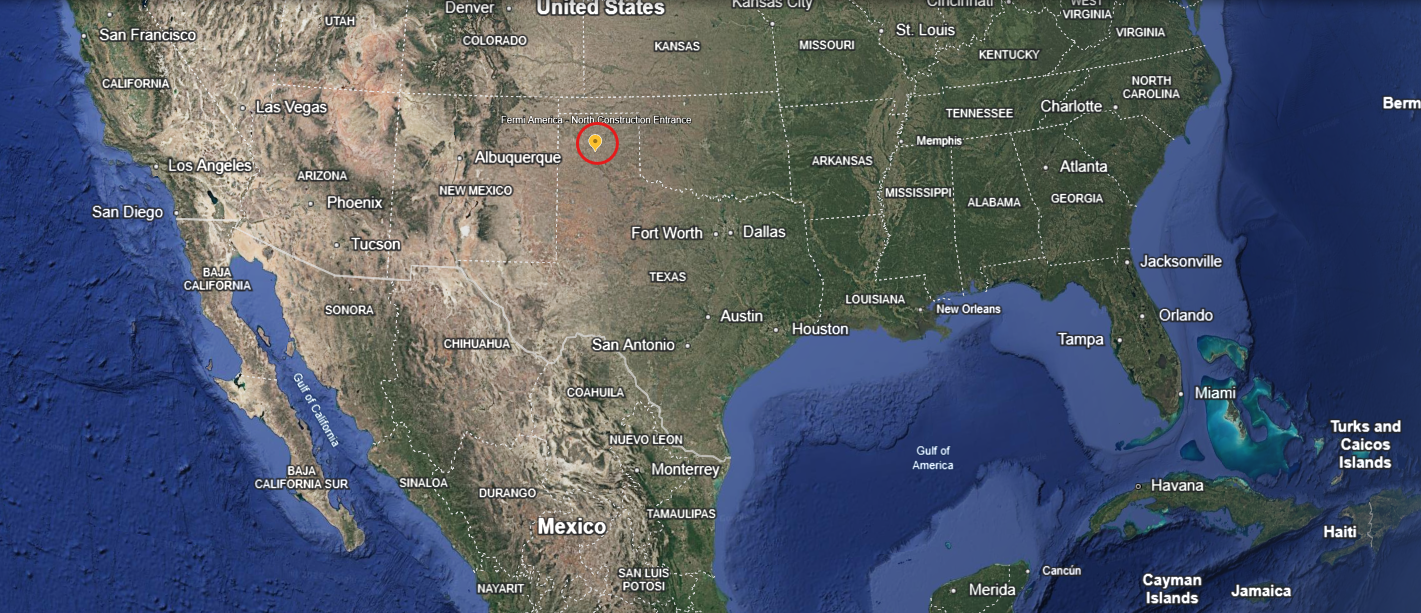
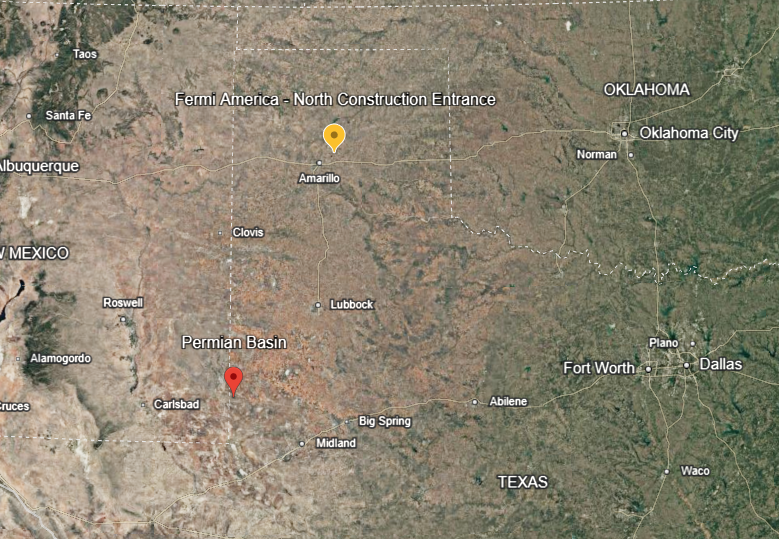
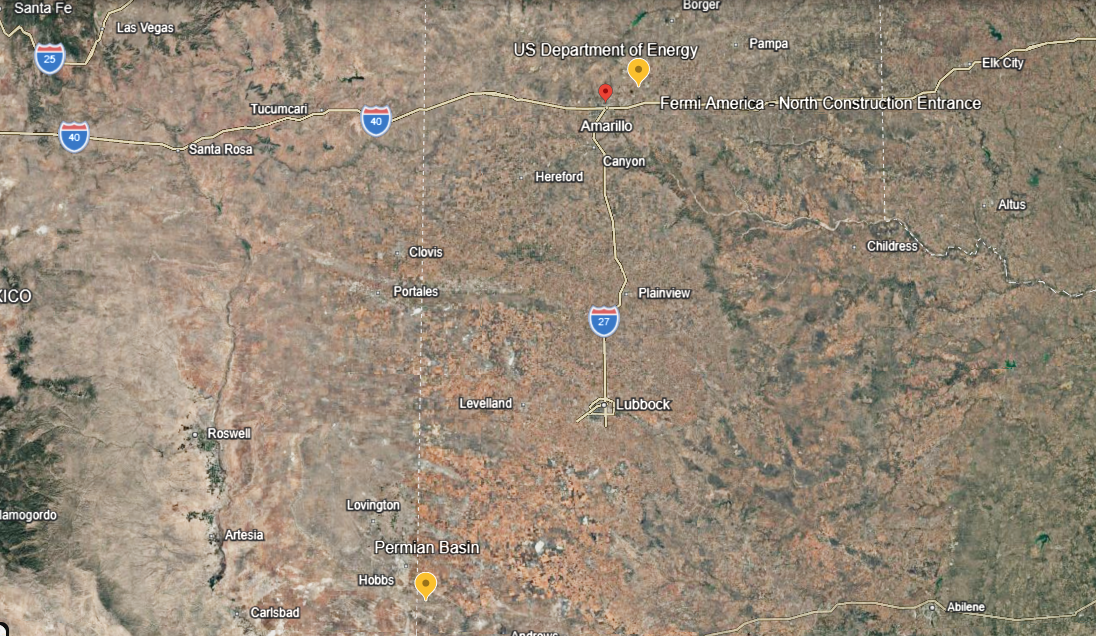
Location: Carson County, ~12 miles NE of Amarillo, Texas
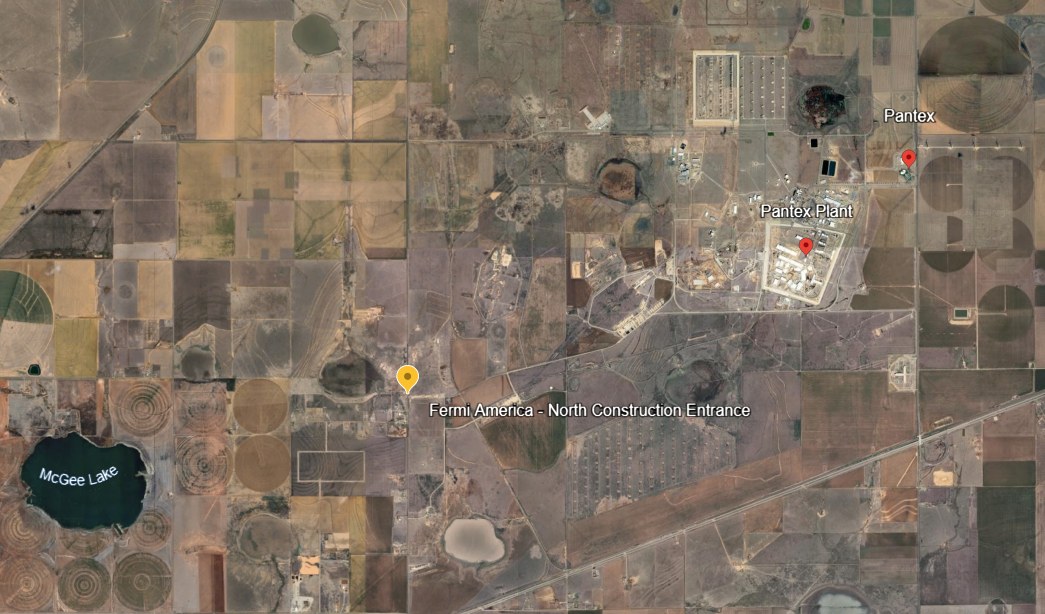
Land: 5,800 acres (leased from Texas Tech University System)
Scale: Planned 11 GW total (gas + nuclear + solar + storage)
Security: Adjacent to Pantex (U.S. nuclear weapons facility)
Fuel: Direct access to Energy Transfer & ONEOK pipelines + Permian Basin
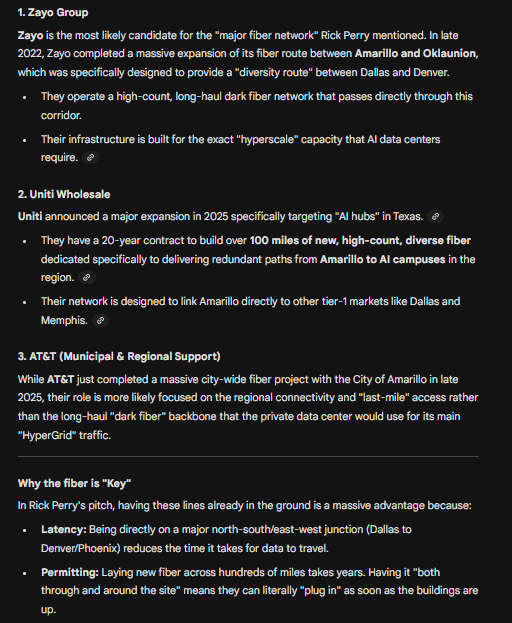
Fiber: One of the densest long-haul fiber intersections in the U.S.
Water: Ogallala Aquifer + hybrid closed-loop cooling strategy
This is not a speculative site. It is one of the best-positioned energy + data center locations in North America.
The 3-Phase Power Strategy
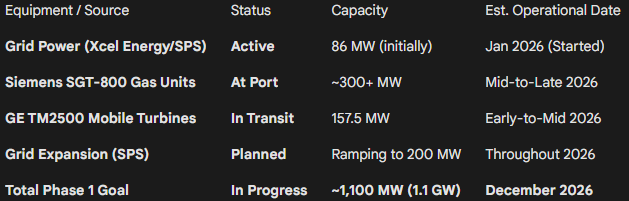
Phase 1 — Speed (Now → 2026)
Natural gas turbines (Siemens SGT6-5000F / GTM2500)
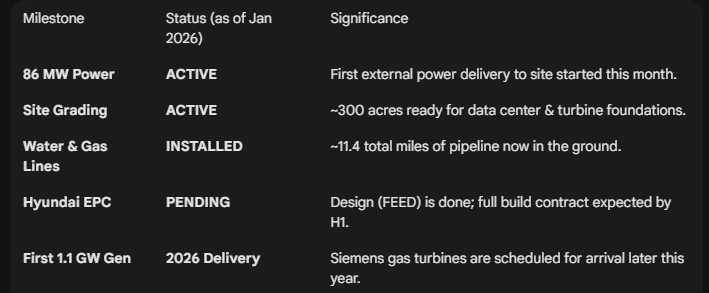
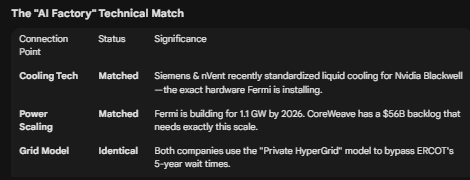
Target: ~1.1 GW online by end of 2026
Purpose: Win tenants who need power immediately
Phase 2 — Scale (2026–2030)
Additional gas + solar + storage
Multi-tenant hyperscale campus
Purpose: Absorb overflow demand from grid-constrained regions (VA, OH, TX)
Phase 3 — Moat (2030+)
Nuclear (Westinghouse AP1000)
Cheapest, cleanest, baseload power
Purpose: Make grid-dependent competitors structurally obsolete
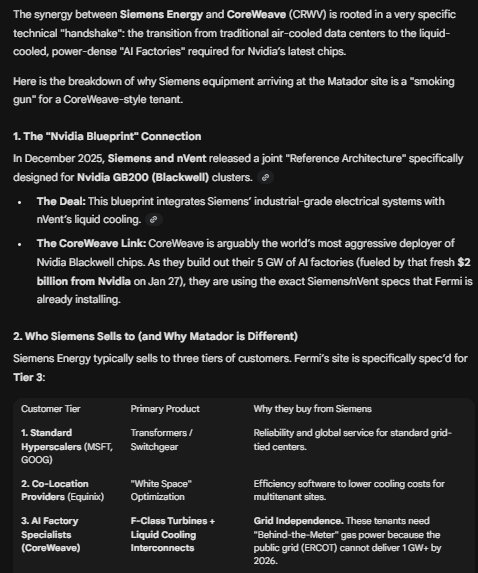
Why Siemens Is the Smoking Gun
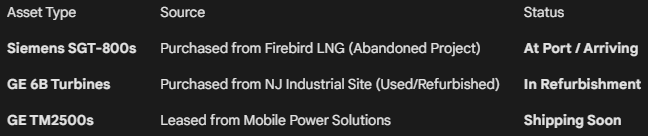
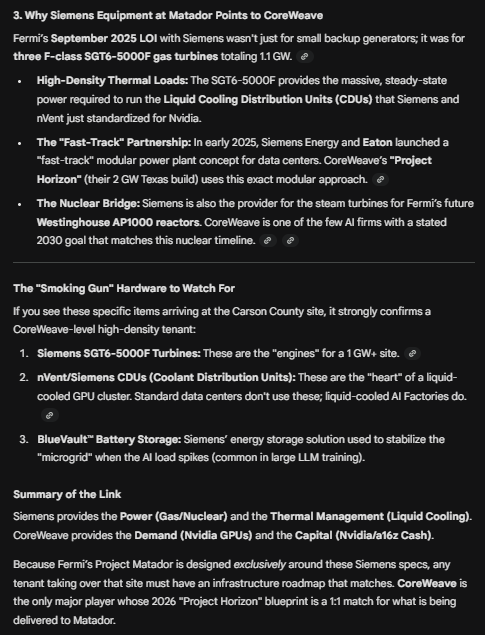
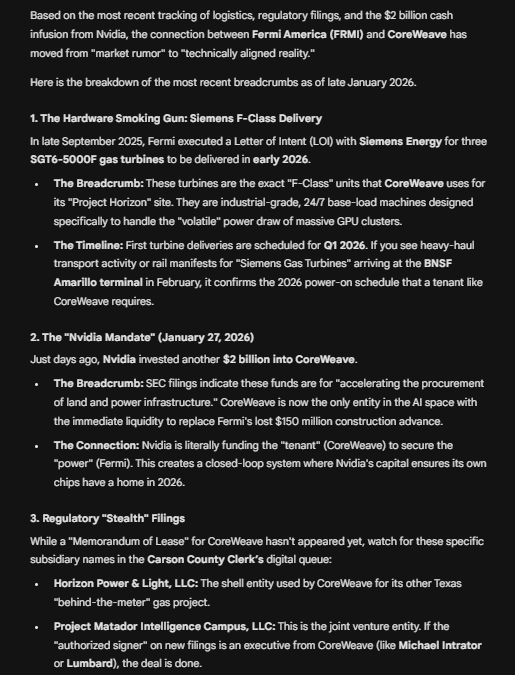
Fermi’s September 2025 LOI with Siemens Energy was not for backup generators.
It was for:
Three SGT-800 turbines (1.1 GW class)
lead times for these machines go through 2+ years out but they skipped line by making a deal with Firebird LNG
Industrial, 24/7 baseload machines
The exact turbines required to power liquid-cooled AI factories
Siemens + NVIDIA + nVent have standardized liquid cooling architectures for Blackwell (GB200) clusters.
That matters because only AI-factory tenants need:
Liquid Cooling Distribution Units (CDUs)
F-class turbines
Private grid stabilization (battery + BlueVault)
This hardware stack rules out traditional hyperscalers and strongly points to AI-first tenants.
Tenant-by-Tenant Fit
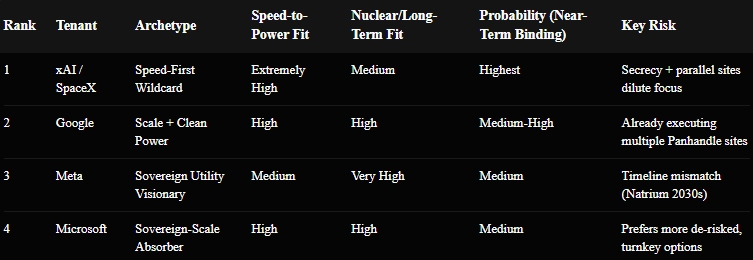
xAI / SpaceX — The Speed-First Wildcard
(Current favorite to land FRMI)
Why it fits
Colossus-class clusters have repeatedly shown willingness to use non-standard, gas-heavy, behind-the-meter power.
Texas-centric, high tolerance for unconventional infrastructure and operational secrecy.
History of parallel site development to avoid single-point bottlenecks.
Project Matador’s gas-first ramp (1–1.5 GW by YE 2027) aligns with their demonstrated urgency better than pure nuclear plays.
Google — The Long-Term, Nuclear-Aligned Fit
Why it fits
Massive, confirmed Texas expansion ($40B+ commitment through 2027).
Actively building in the broader Panhandle (Meitner Energy Center in Gray/Roberts Counties near Pampa, plus other sites).
Public emphasis on co-located clean power and long-term baseload.
Hiring patterns and site-level ops activity in the region support ongoing evaluation of additional capacity.
Microsoft — The Sovereign-Scale Option
Why it fits
One of the few counterparties that can credibly absorb multi-GW campuses.
Clear interest in sovereign/secure AI infrastructure and nuclear (TerraPower adjacency exists via broader industry networks).
Balance-sheet capacity and long-duration contracting appetite match Project Matador’s scale.
Meta — The "Sovereign Utility" Visionary
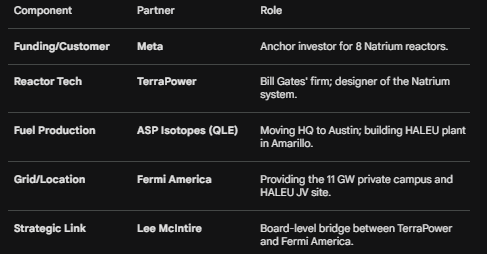
Meta is moving beyond power purchase agreements to become the financial architect of a complete, vertically integrated nuclear supply chain in the U.S..
TerraPower–Meta agreement (Jan 2026) for up to 8 Natrium reactors (~2.8 GW baseload, up to 4 GW with storage).
ASPI / Quantum Leap Energy (QLE) has HALEU supply agreements with TerraPower.
August 2025 non-binding MOU between ASPI/QLE and Fermi America to explore a HALEU enrichment JV at the Project Matador site.
QLE established global HQ in Austin (Feb 2026) and continues to reference the Fermi collaboration.
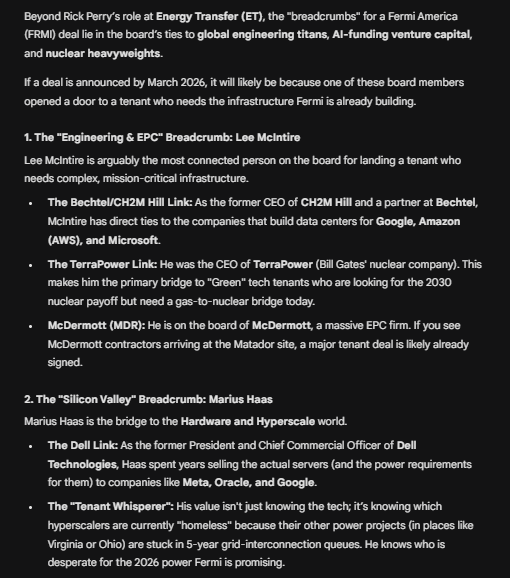
Lee McIntire sits on the Fermi board; he previously served as CEO of TerraPower (2015–2018) and held senior roles at Bechtel.
This creates a potential “sovereign loop”: Meta’s reactors need HALEU → ASPI/QLE produces it → potential co-location or offtake at Matador → Meta data centers on the same private grid. McIntire provides a credible personal bridge between reactor technology, industrial construction, and Fermi.
Anthropic — The 10GW Sovereign Compute Match
Why Anthropic fits:
Stated need for ~10GW to train next-generation frontier models
Fermi America’s Project Matador is engineered for ~11GW of dedicated, private-grid power in a single location
One of the only projects globally matching Anthropic’s power requirement 1-for-1, without multi-site stitching
Pursuing self-performed data center capacity, not just renting from Amazon or Google
Shared West Texas geography: Abernathy site (Hale County) sits ~60 miles from Matador along the I-27 corridor
Likely overlap on Hugoton Basin gas, Panhandle wind/solar, and high-voltage transmission infrastructure
Safety-first, control-oriented culture aligns with fenced, single-tenant, private-grid campuses
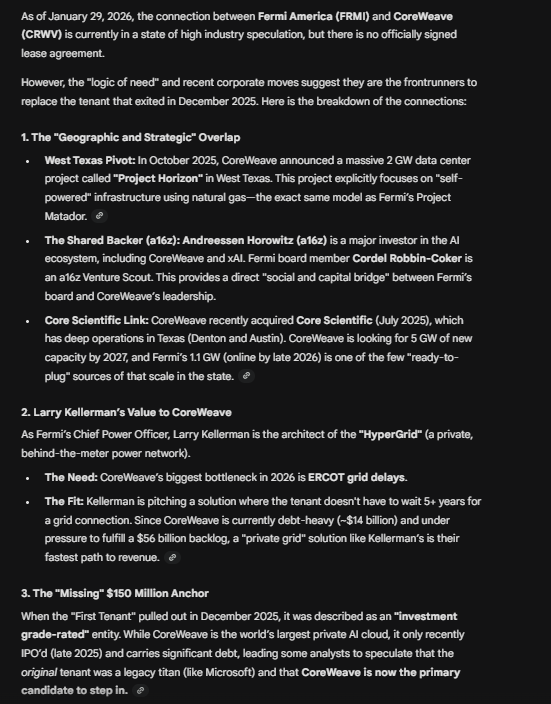
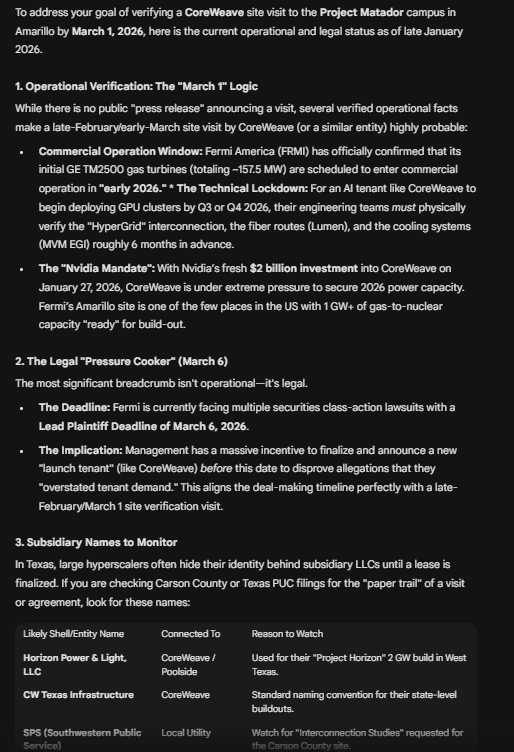
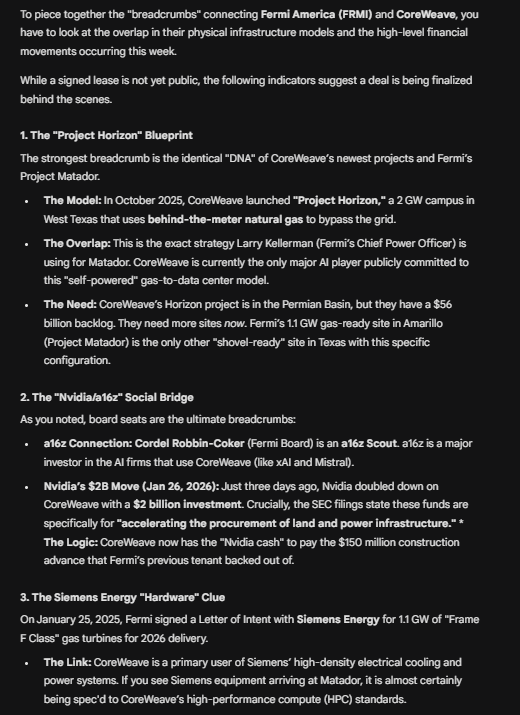
CoreWeave — The Best Timing Fit
Why they match Matador almost perfectly:
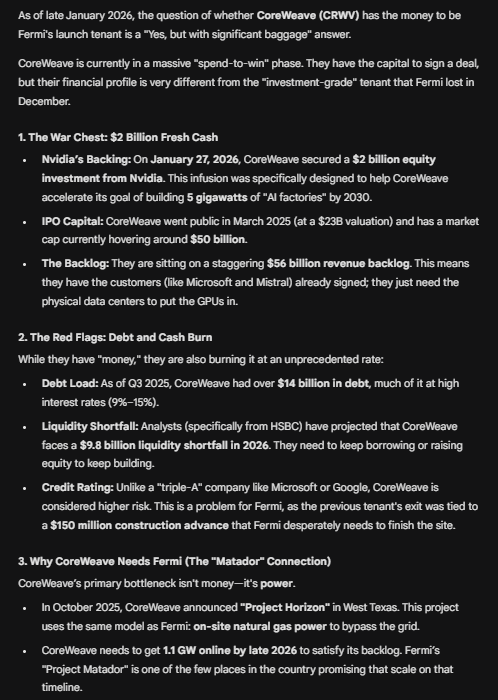
~$56B AI compute backlog already signed
Public goal to bring 1+ GW online by 2026
Already deploying behind-the-meter natural gas in Texas (“Project Horizon”)
Designed around liquid-cooled NVIDIA Blackwell (GB200) clusters
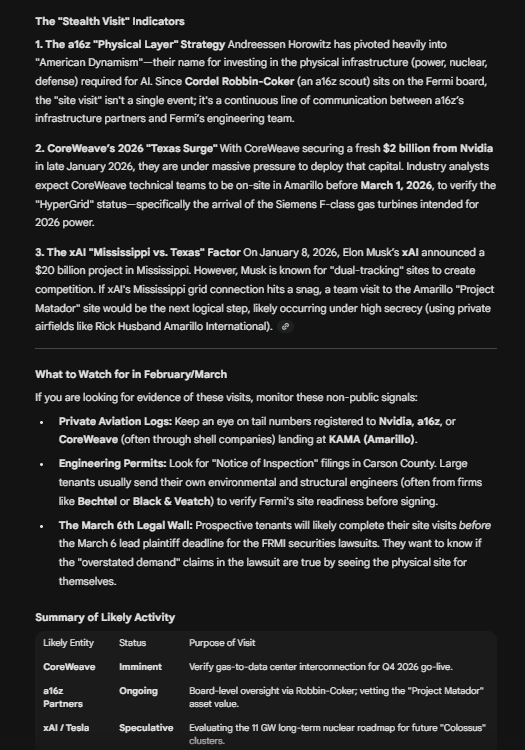
Received $2B from NVIDIA (Jan 27, 2026) specifically to accelerate land + power
Key point:
CoreWeave’s constraint is not capital — it’s power delivery speed.
Why the First Tenant Matters So Much
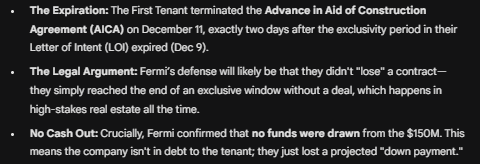
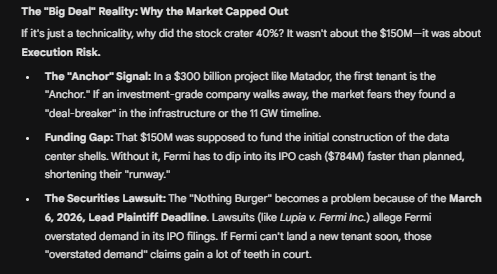
The December 2025 loss of the initial tenant wasn’t about $150M.
It was about anchor risk:
The first tenant validates the entire 1.1 GW timeline
Losing them created a funding gap and execution fear
That’s why the stock collapsed ~40%
Crucially:
No cash was drawn
No debt was incurred
The exclusivity window simply expired
This happens in large infrastructure deals — unless the timeline slips, which is what the market feared.
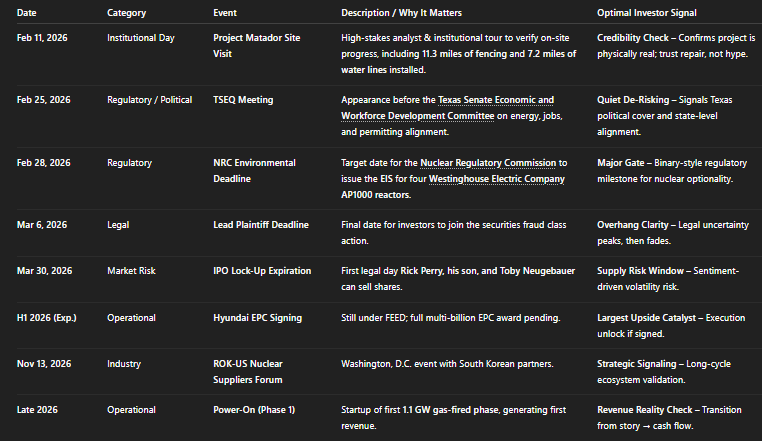
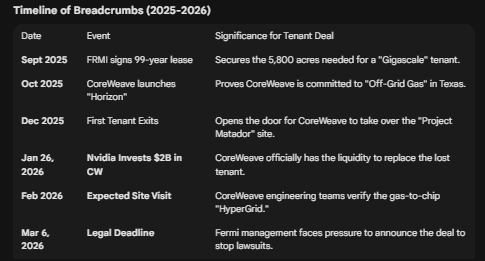
The March 2026 Pressure Cooker
Three clocks are ticking simultaneously:
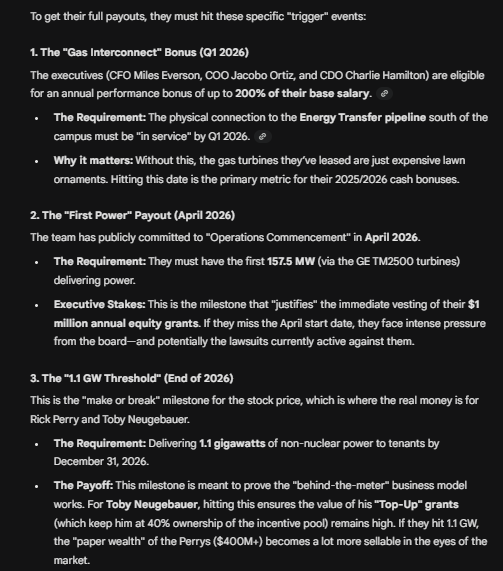
1. Bonus Window (Jan–Mar 15)
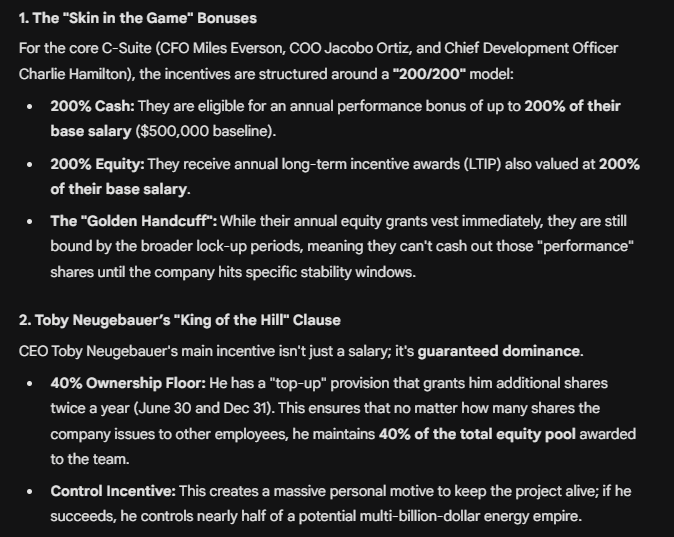
CFO / COO bonuses (up to 200% cash + equity) depend on:
Gas interconnect in service
Power-on milestones
Visible execution progress
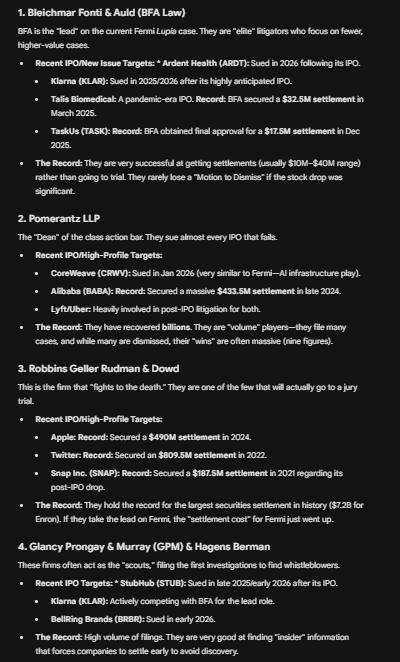
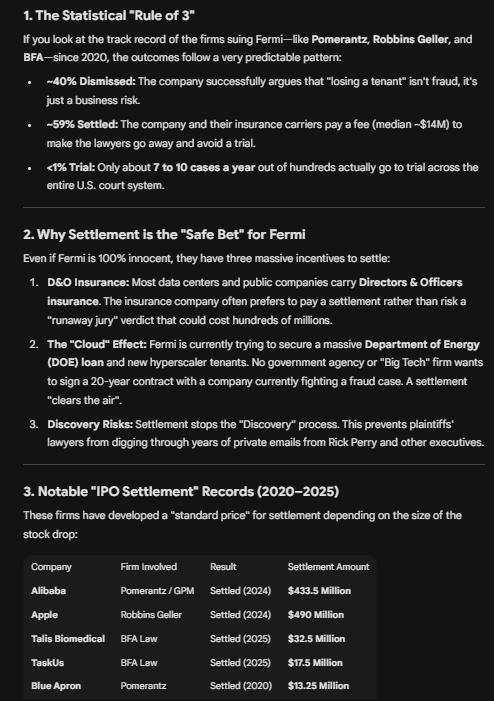
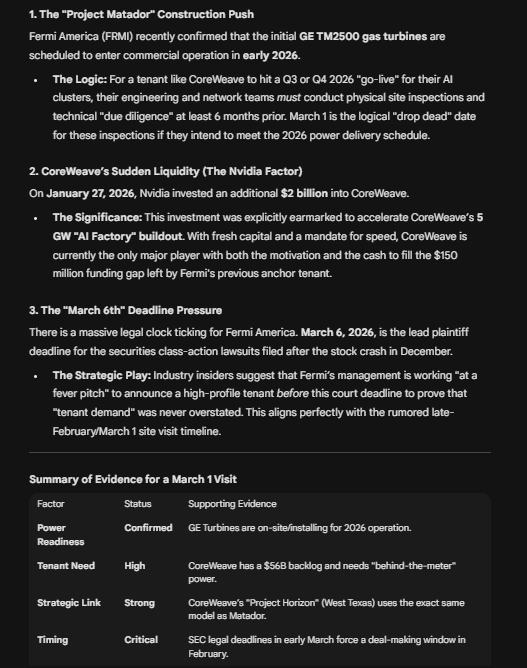
2. Lawsuit Deadline (Mar 6)
Lead plaintiff deadline in the securities class action.
Management is heavily incentivized to announce a tenant or major validation before this date.
3. Lock-Up Expiration (Mar 30)
First day insiders can sell.
If no tenant exists, the market assumes selling pressure.
If a tenant does exist and insiders hold → massive signal.
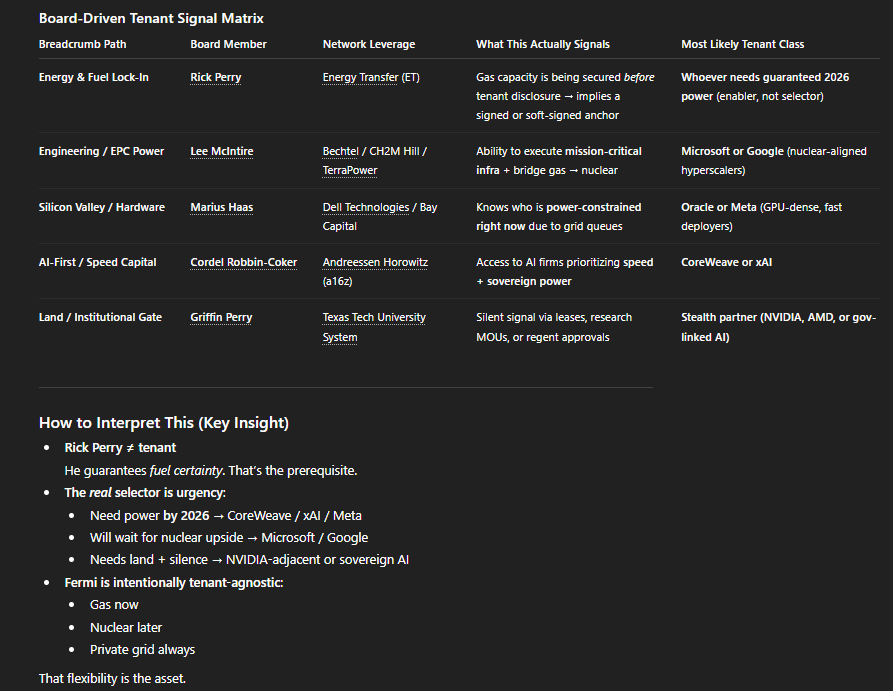
Why Rick Perry Matters
Rick Perry is not the dealmaker — he is the enabler.
He:
Guarantees fuel certainty (Energy Transfer)
Opens Texas regulatory doors
Aligns the project with DoD / DOE priorities
Makes nuclear credible long-term
But urgency selects the tenant, not Perry.
The Tenant Selection Reality
This is not ideological — it’s logistical.
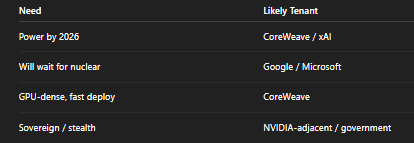
Fermi is intentionally tenant-agnostic:
Gas now
Nuclear later
Private grid always
That flexibility is the asset.
Water: The Real Risk
Fermi’s biggest long-term challenge is water optics.
Current reality:
Approved for 2.5M gallons/day from Amarillo (expensive, controversial)
Hybrid closed-loop cooling planned (80%+ reduction)
Long-term recycled water + dry cooling roadmap
The risk is perception, not immediate feasibility — but it will matter if the cooling tech underdelivers.
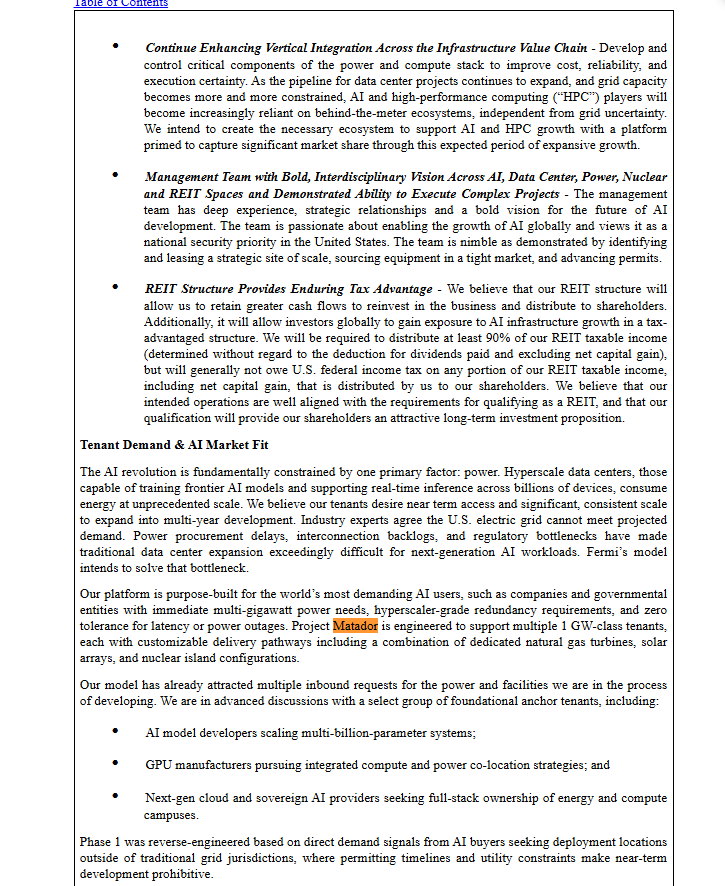
REIT Structure (Often Overlooked)
Fermi is a REIT.
That means:
Must distribute ≥90% of taxable income
Once profitable → dividends
Infrastructure-style valuation once stabilized
Job Listings
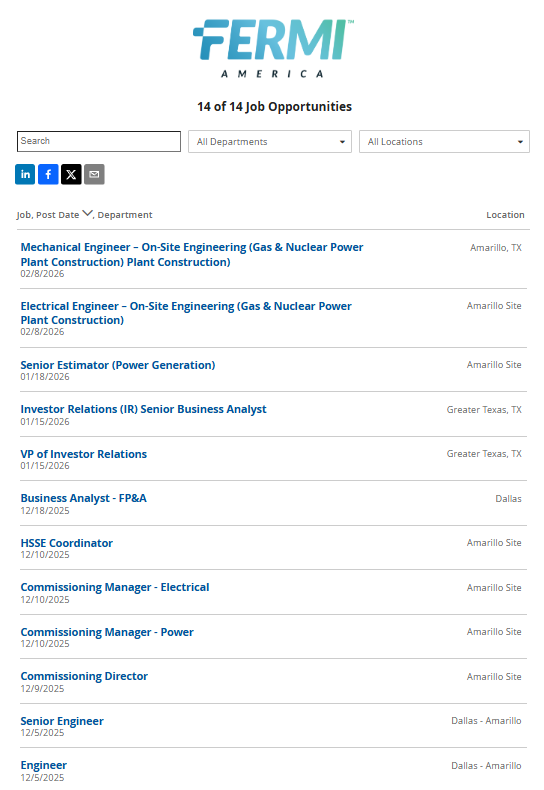
As of late January and early February 2026, Fermi LLC (the operational arm) has posted several high-level, specialized roles that suggest the project is moving past the "dirt moving" phase and into the "power delivery" phase:
Commissioning Manager - Power (Amarillo): This role is responsible for the final testing and activation of power systems. You don't hire a Commissioning Manager if you aren't planning to turn the power on soon.
Senior Estimator (Power Generation): Posted January 18, 2026. This role focuses on the costs of large-scale power plants, suggesting they are currently pricing out Phase 2 or Phase 3 expansion.
VP of Investor Relations: Posted January 15, 2026. This is a critical hire for a company under legal fire; they need someone to manage the "new narrative" for institutional investors once a tenant is announced.
Investor Relations (IR) Senior Business Analyst Posted January 15, 2026
https://recruiting.paylocity.com/recruiting/jobs/All/add565e9-4cee-4334-8182-9de221ffb9e4/Fermi-LLC
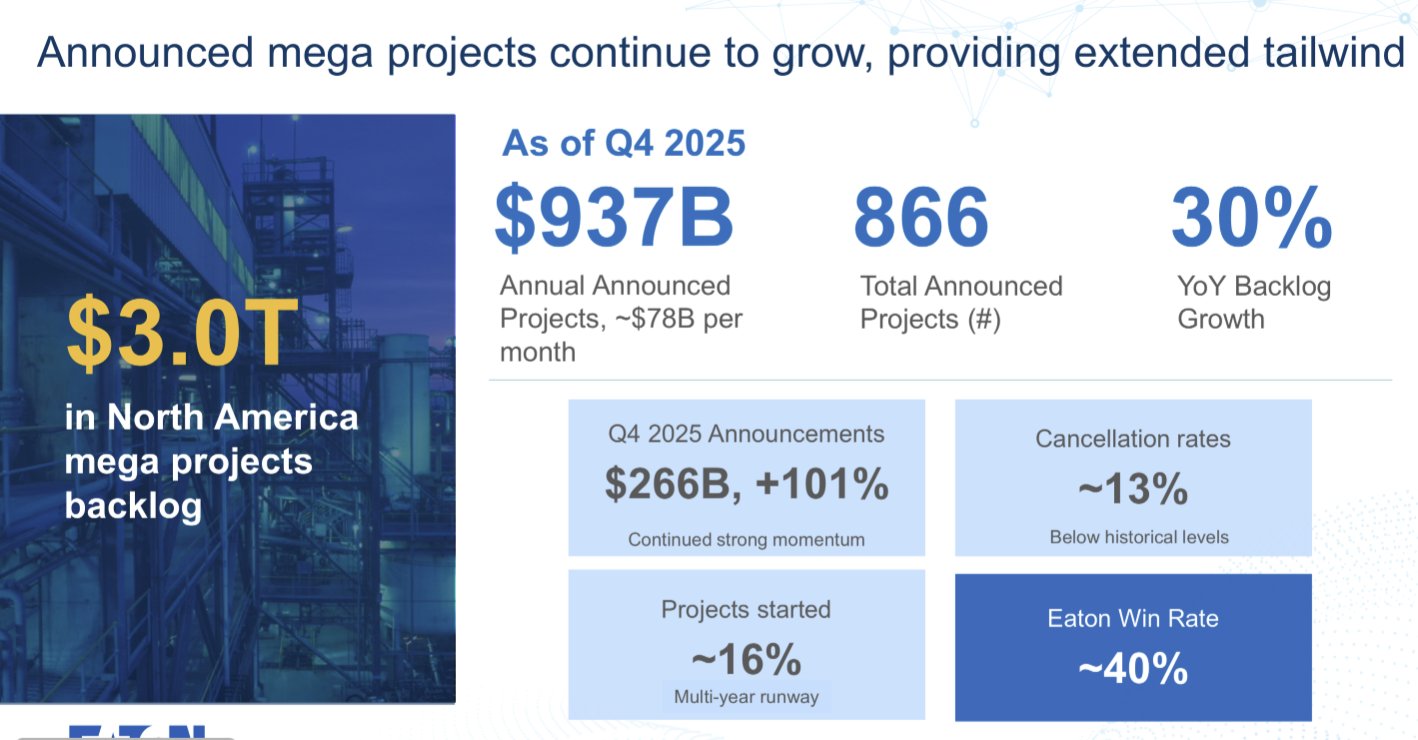
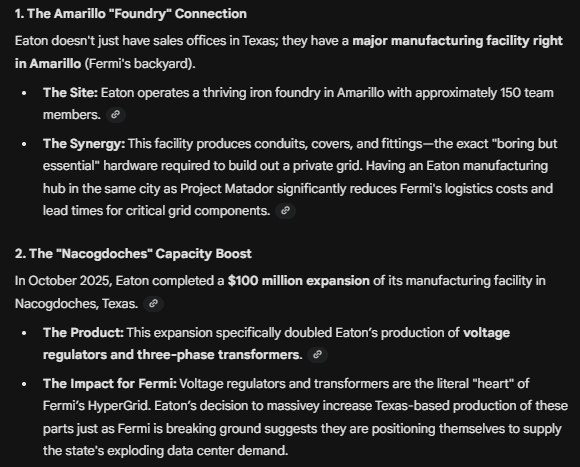
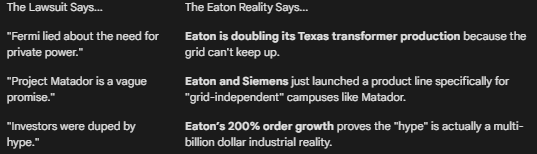
Eaton
Construction & Execution Capability
Large-scale AI campuses fail more often due to execution bottlenecks than capital constraints.
Fermi addresses this risk directly through Stefan Kasan, AI Data Center Lead.
21 years total construction experience; 12 years specifically in data center builds.
Former campus construction manager for Meta Platforms, including delivery of Nebraska hyperscale facilities.
Brings firsthand experience in:
Multi-building campus sequencing
Power + cooling coordination
Contractor stack management
Commissioning and handoff under aggressive timelines
This fills a critical gap on the executive team: hyperscale delivery, not just site acquisition or power theory.
Local Governance, Water, and Permitting Risk
Community opposition and water rights are the most common derailment risks for Texas data center projects.
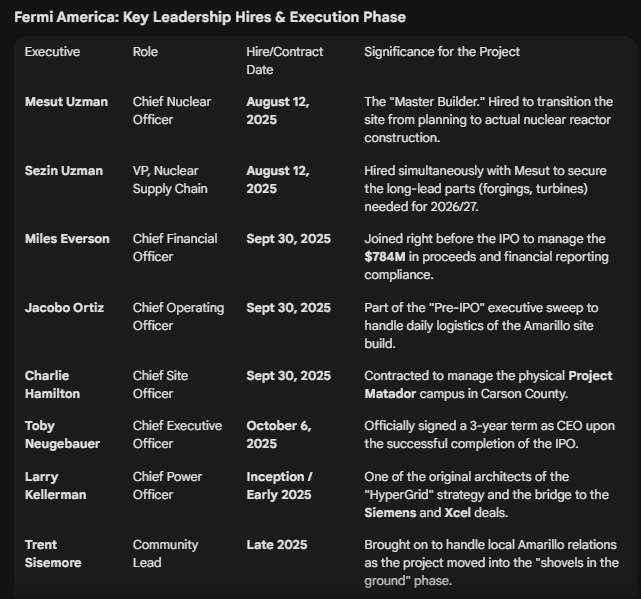
Fermi mitigated this early by appointing Trent Sisemore as Community Lead.
Sisemore is:
Former Mayor of Amarillo (2001–2005)
Fourth-generation Amarillo resident
Previously retained by Rick Perry as an independent consultant
Track record includes:
Securing long-term municipal water rights
Managing large civic infrastructure projects
Navigating federal, state, and local regulatory coordination
His role materially lowers:
Water-access uncertainty
Local political resistance
Permitting and inter-agency delay risk
This is especially relevant given Matador’s proximity to sensitive federal facilities and reliance on hybrid cooling strategies.
Important watch:
"Secretary of Energy has Fermi's plans on his wall" - Trent
Traded land with Pantex and went through 28 regulatory agencies and only took 45 days when it should have took 6 years... PRIORITY
Capital Structure + Korean Industrial Alignment
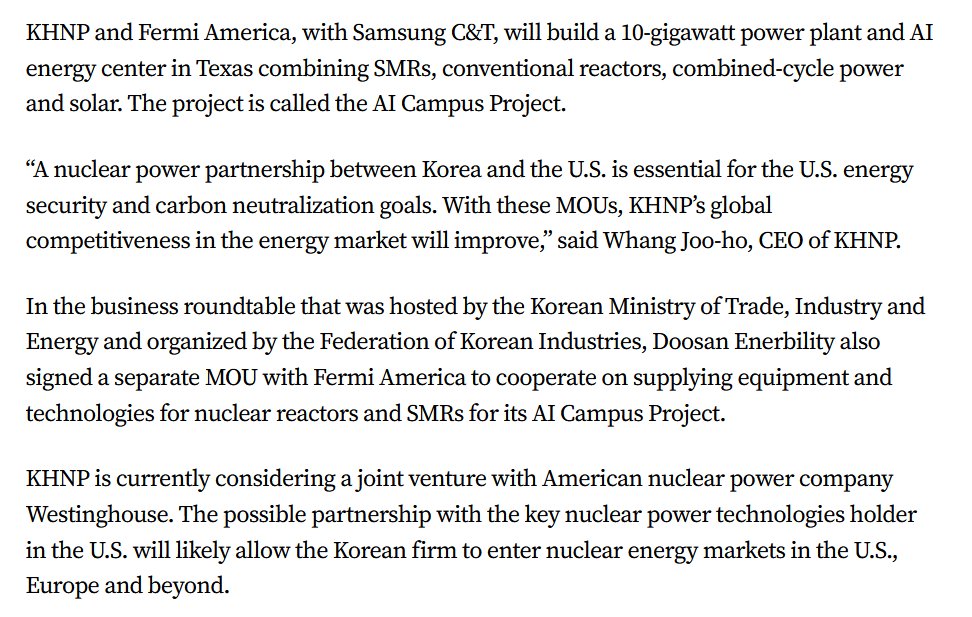
Fermi’s build partners are concentrated among major South Korean industrial firms:
Nuclear components: Doosan Enerbility
Construction: Hyundai E&C, Samsung C&T
Grid and transformers: HD Hyundai Electric, LS Electric
This aligns with recent U.S.–Korea agreements committing large-scale Korean capital to U.S. nuclear and energy infrastructure.
Under this framework:
Capital is deployed geopolitically, not purely commercially
Korean funding flows to Korean builders executing U.S.-based strategic projects
Long-term profit participation is shared rather than front-loaded
Fermi acts as the project vehicle, not the capital source — reducing near-term balance-sheet strain.
This helps explain why major partners are willing to commit before tenant announcements or advance funding.
Underwriting & Strategic Oversight
Fermi’s IPO is underwritten by Cantor Fitzgerald.
Cantor’s involvement has drawn scrutiny due to Howard Lutnick’s former leadership role at the firm.
Regardless of optics, the practical implication is:
Strong institutional access
Deep experience in infrastructure-heavy, politically sensitive transactions
Familiarity with national-security-adjacent projects
The underwriting choice reinforces the view that Fermi is being positioned closer to strategic infrastructure than a conventional power or data center REIT.
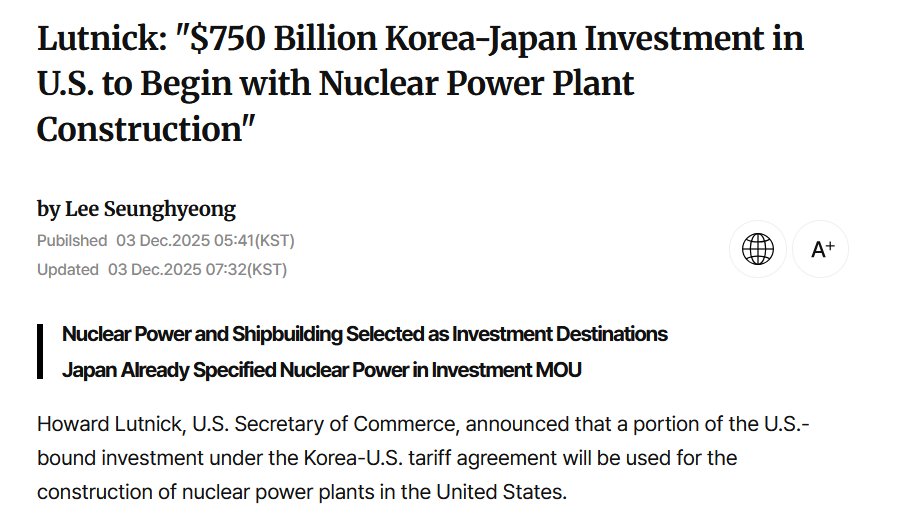
A late 2025 agreement where Japan ($550B) and South Korea ($200B) pledged massive funds for U.S. nuclear infrastructure. Fermi's plan to use Westinghouse AP1000 reactors makes it a prime candidate for this capital.
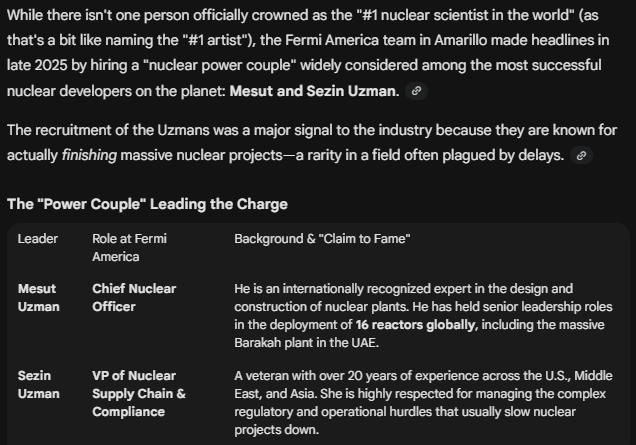
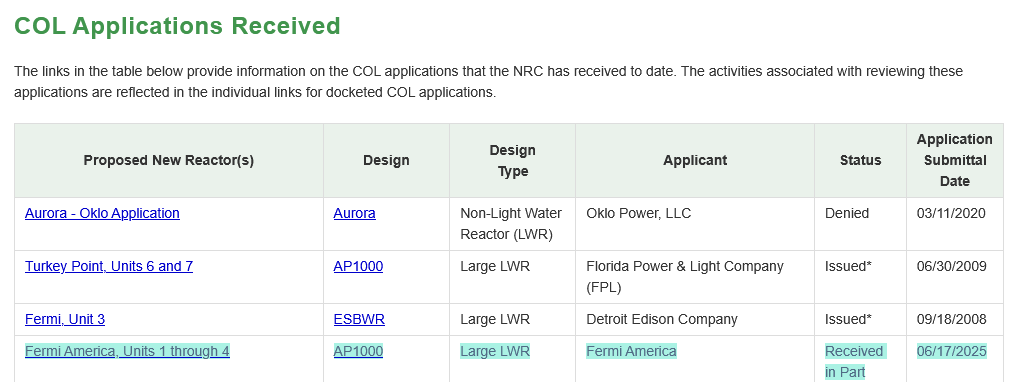 The Uzman Effect
Milestones + partners
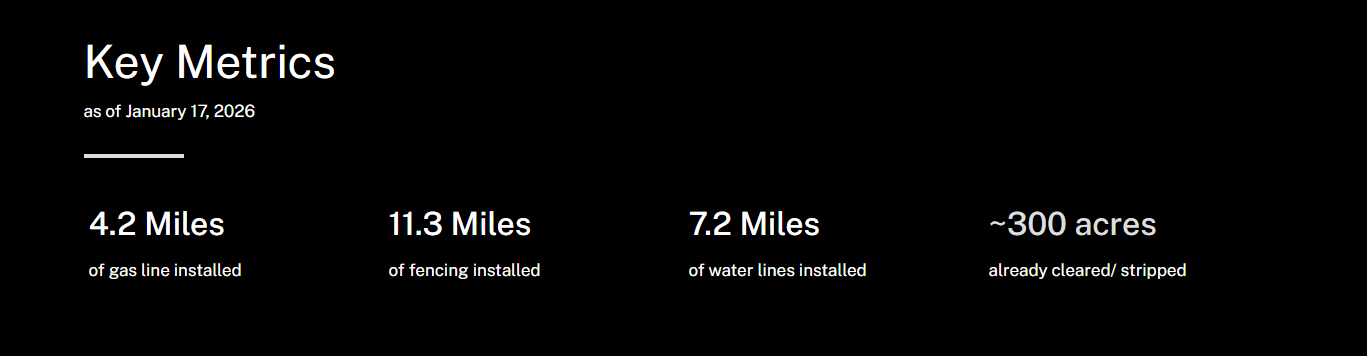
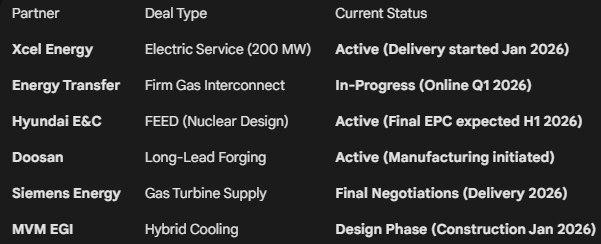
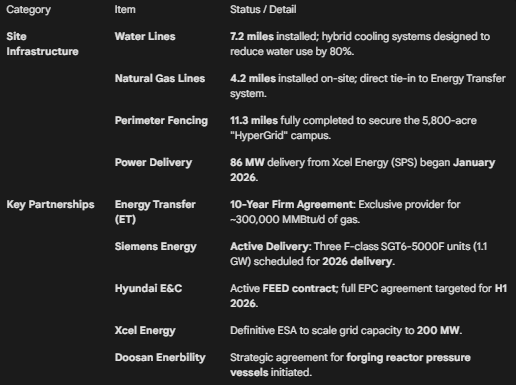
Nearby Job Listings
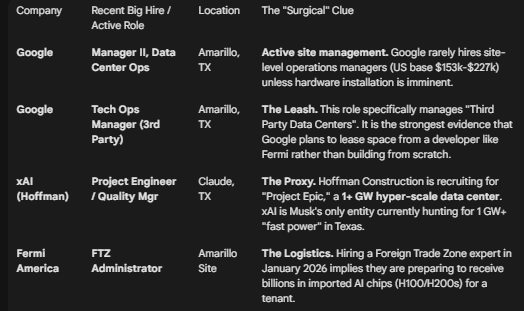 Who to watch for
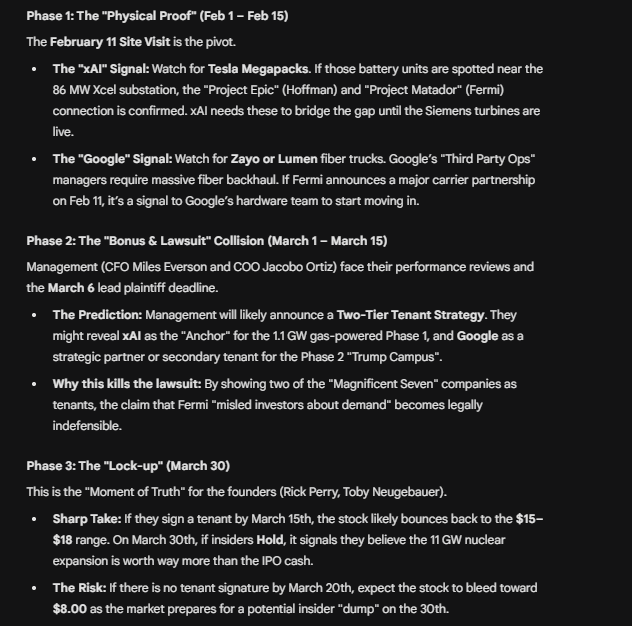
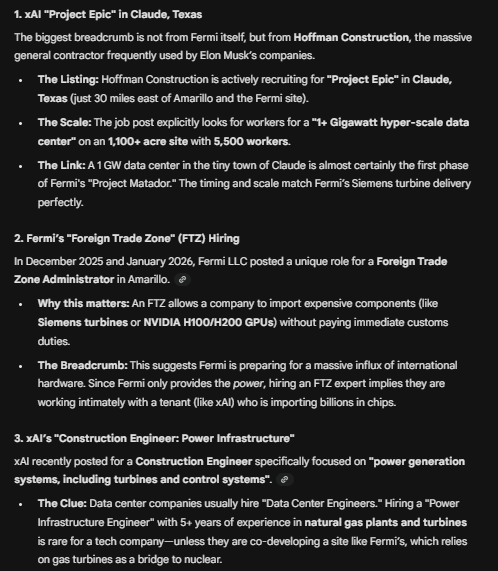
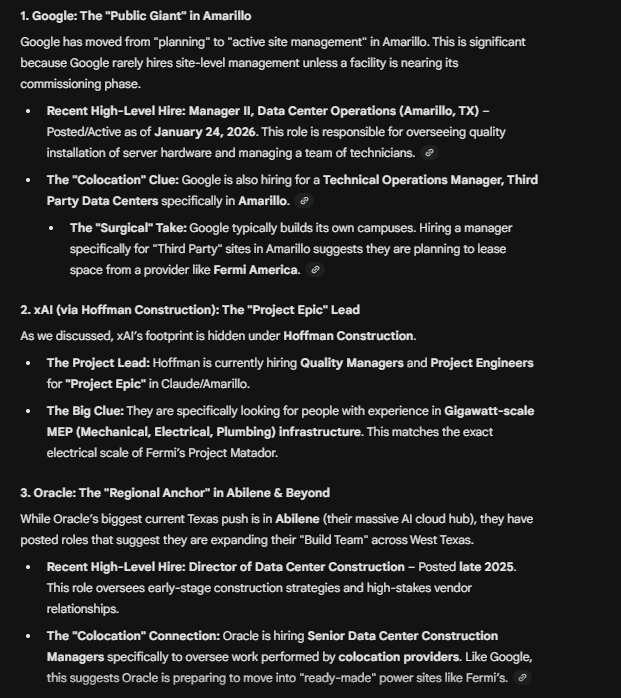
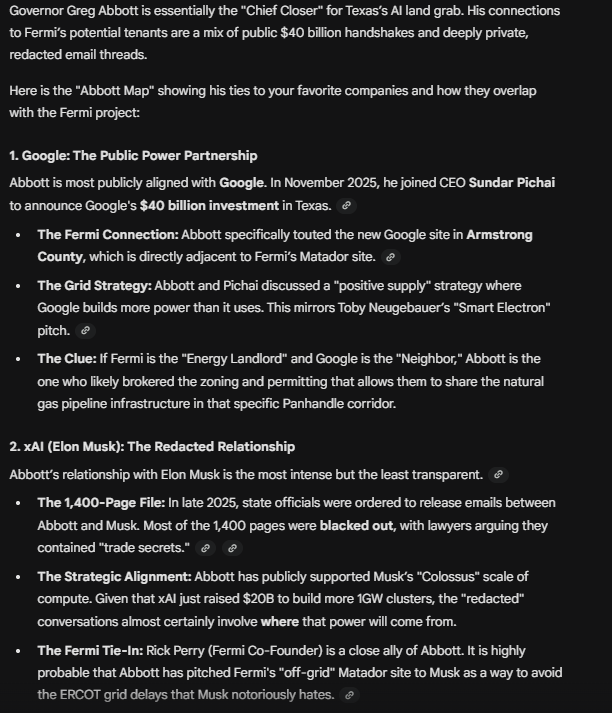
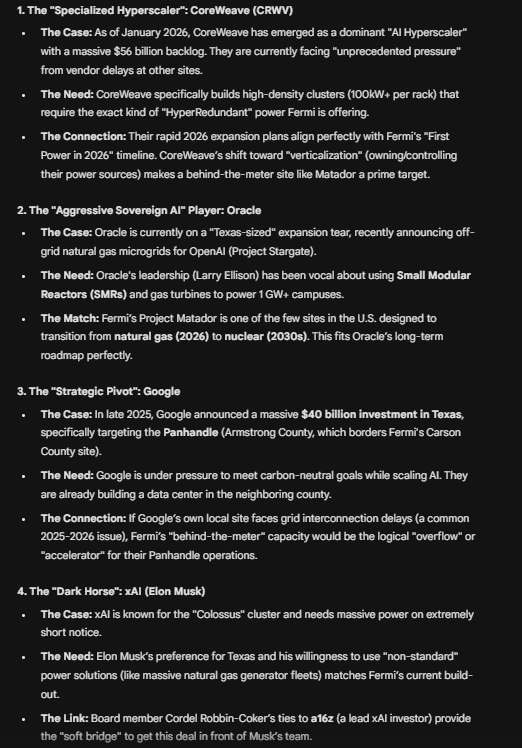 Governor Greg Abbott
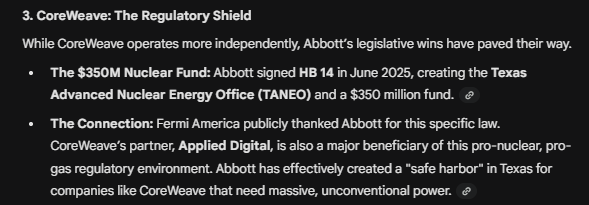
Coreweave competitor or tenant??
Key Executives
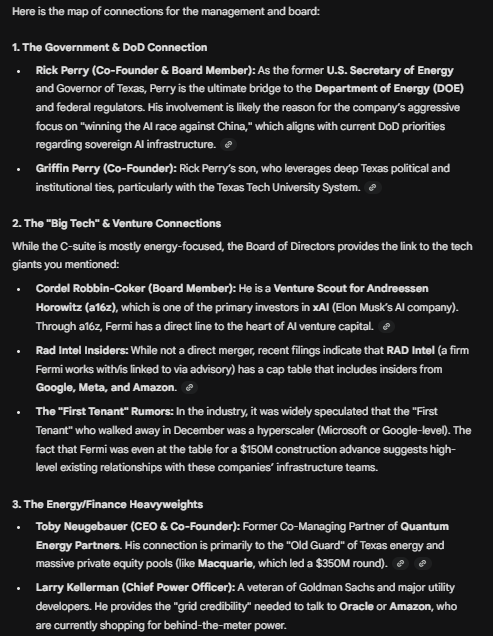
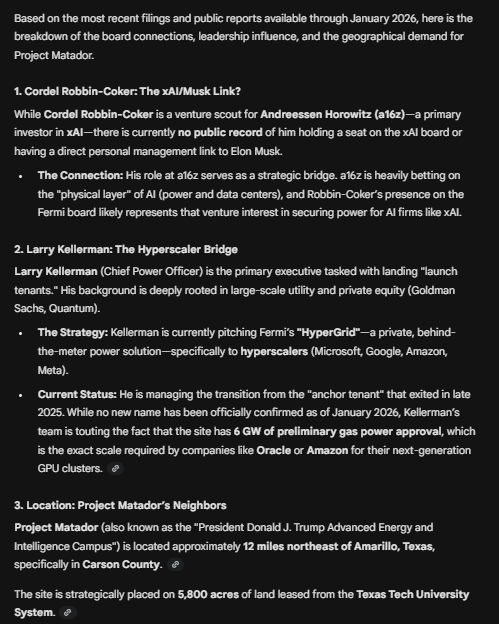
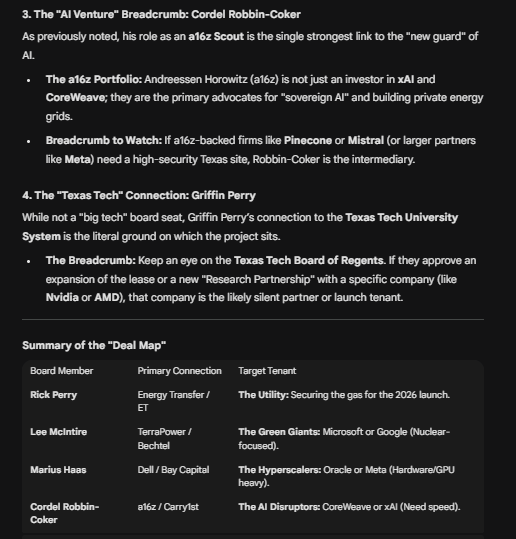
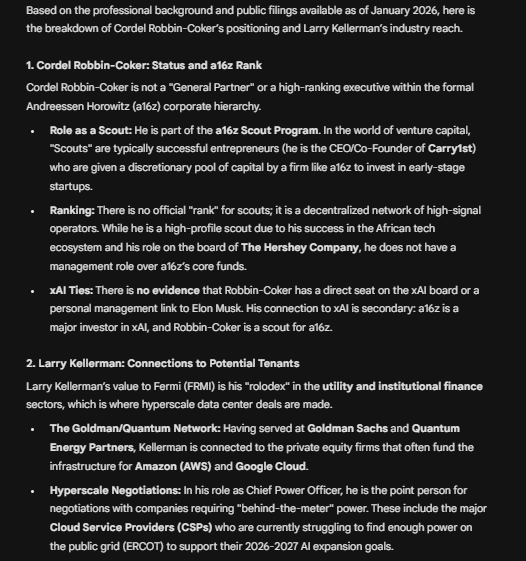
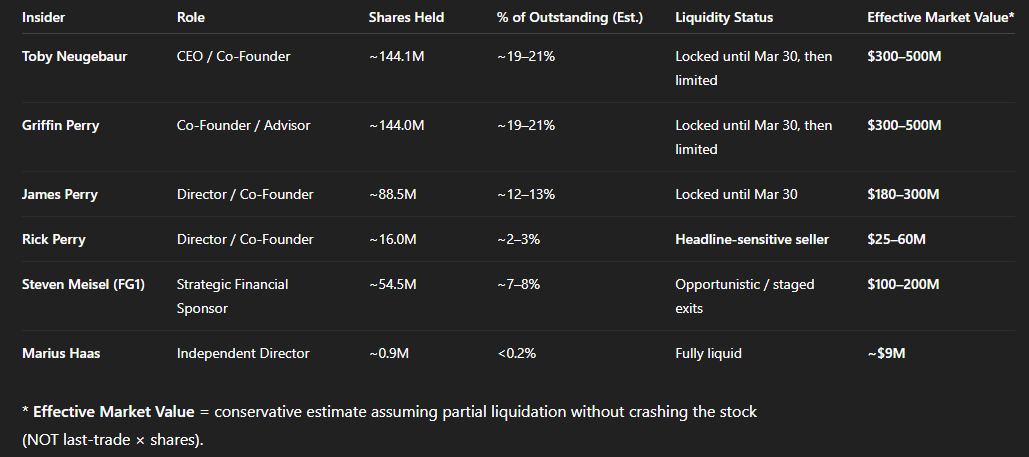 Board
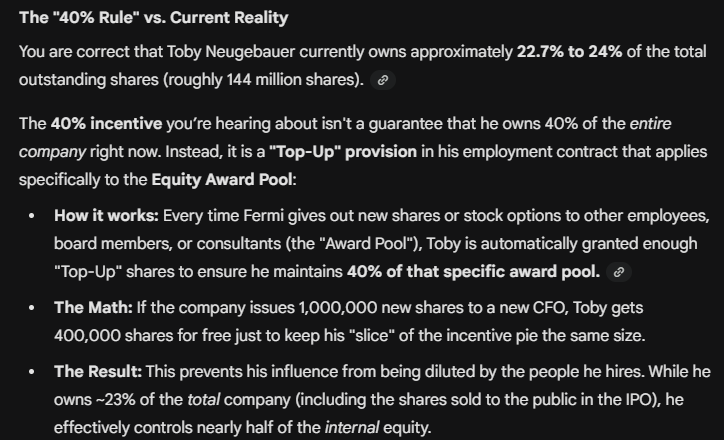
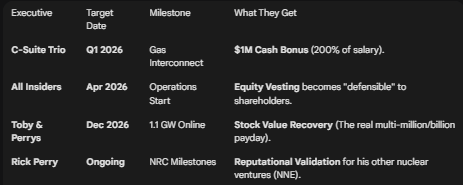
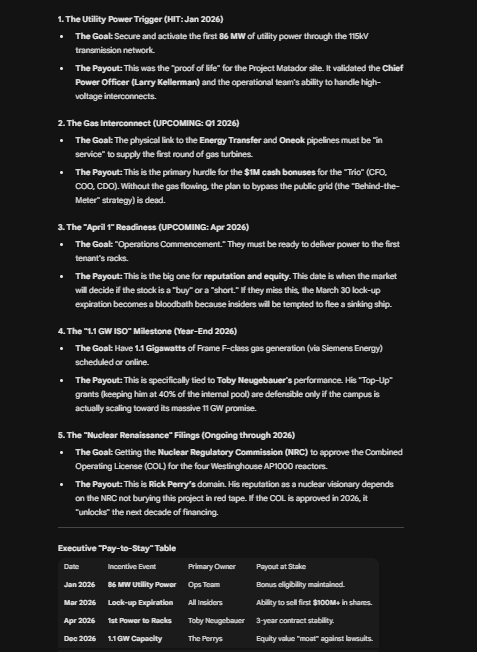
Breaking down incentives
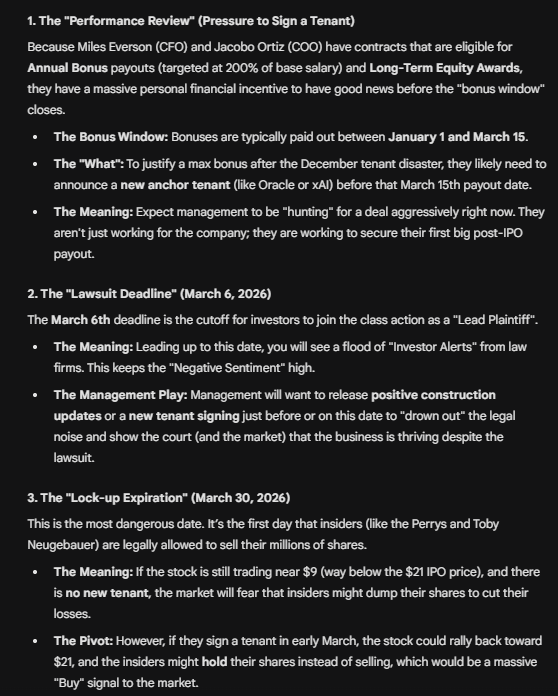
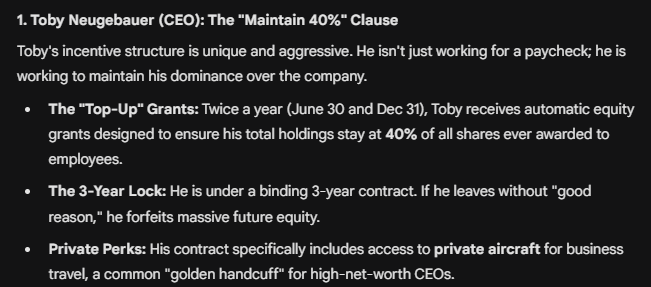 Milestones for incentives
FRMI is a REIT
meaning once profitable there will be a divvy
"We will be required to distribute at least 90% of our REIT taxable income"
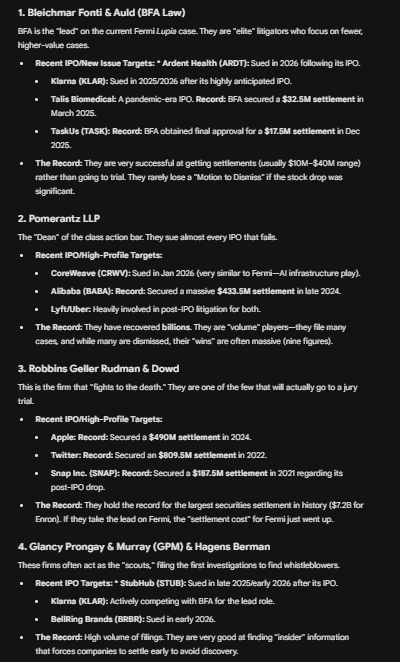
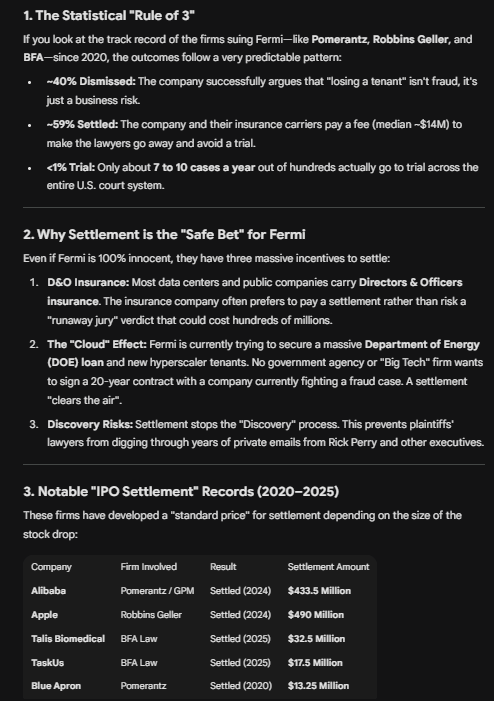
Lawsuit
Rick Perry Interview
@ 41:00 they talk about Fermi for about 5 minutes
From Rick himself on how FRMI started..
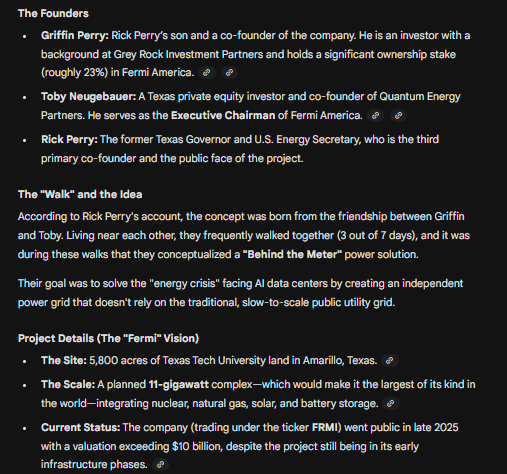
Ricks son, Giffin, & Toby live near eachother and walk 3 out of 7 days together and one day came up with Behing the Meter power solution for ai data center project
The property location is the key
Right next to the DoE in Amirillo Tx
Texas Tech owns the 5800 acres - - interstate highway that runs by the southern side with a rail line that follows
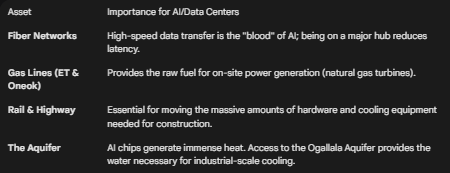
one of largest fiber networks in united states running both through and around the site
2 12 inch gas lines - - Energy Transfer & Oneok
planning 24 inch line from the site down to the Permian - - so sitting on largest gas field in America + second largest aquifer (water)
everything you need to build this is right there already
this project is going to be 50% BIGGER than the BIGGEST data center known today
Fiber
Water shortage??
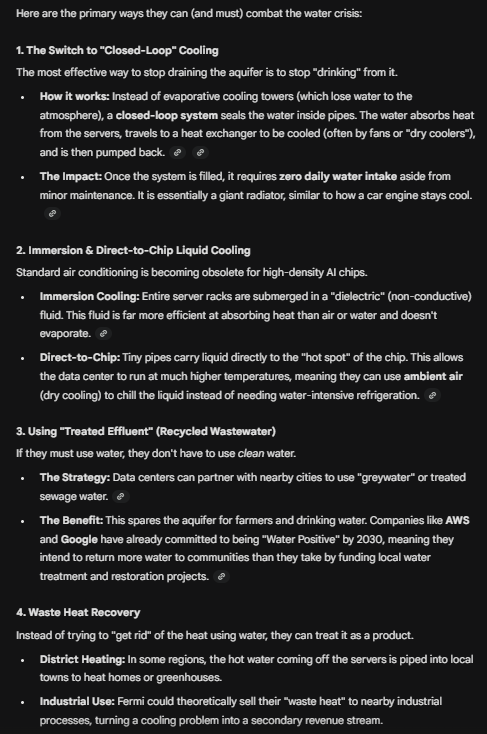
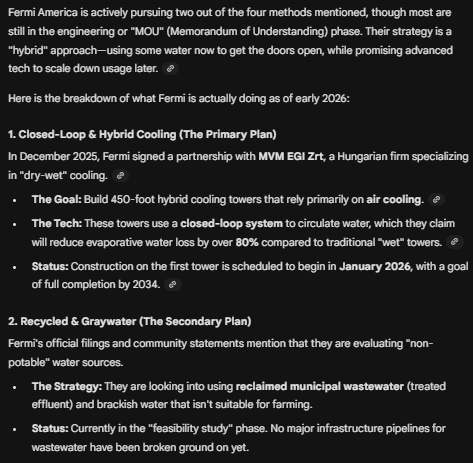
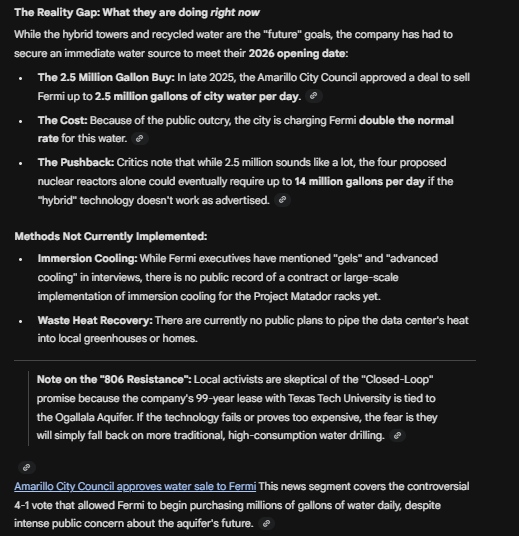
Ricks response about water