

Recently, Kinder Morgan, the largest operator of the natural gas transportation system in the United States, has attracted investor attention due to a significant increase in its stock price – over the last 12 months, the price has risen by as much as 100%. However, despite such an impressive result, there is a possibility of market cooling in the near future.
The company's management emphasizes that a significant increase in demand for natural gas is expected, especially in the LNG production sector, as well as for the development of new technologies, including artificial intelligence, cryptocurrency mining, and data center operations. In light of these factors, Kinder Morgan is focusing on the restoration of the industrial base in the country, which should positively impact gas consumption both domestically and abroad.
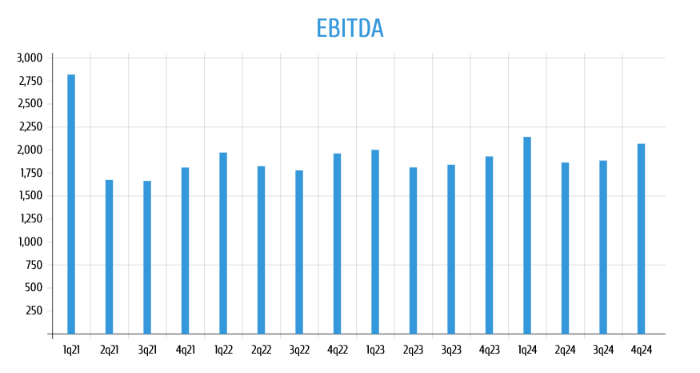
Despite optimism regarding future gas demand, the company’s financial forecasts are rather modest. EBITDA is expected to grow by only 4% by 2025, and the increase in dividends will be just 2%. Meanwhile, revenue is expected to remain virtually unchanged.
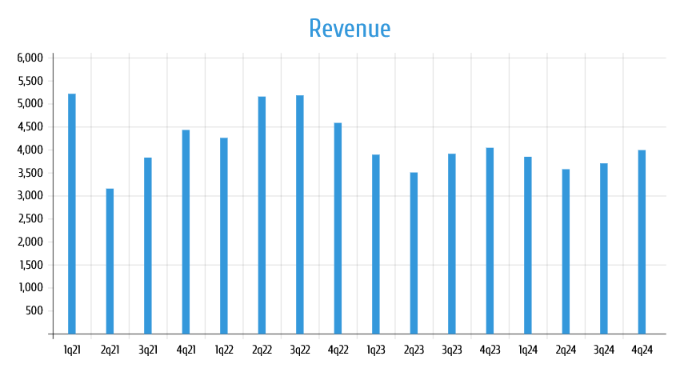
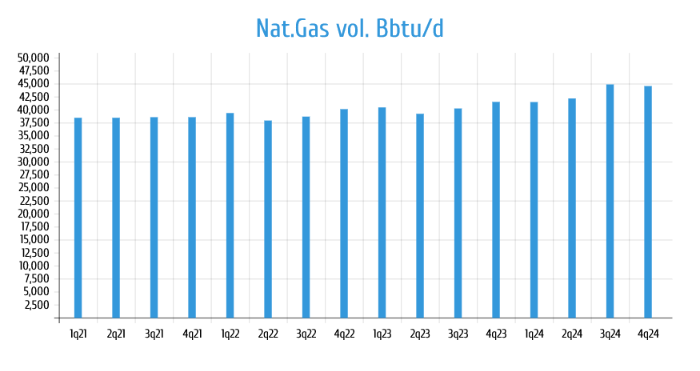
However, it is worth noting that gas transportation volumes have increased by 15% over the past three years, which is a significant achievement for such a large company. However, these improvements have not led to a corresponding increase in cash flows.
The distribution cash flow (DCF), from which dividends are paid and capital expenditures are funded, remains stable. This means that although gas transportation volumes have increased, the cash flows from this process have remained at the same level.
Experts attribute this to the rise in operating expenses and the need for significant investments in infrastructure upgrades.
For reference, note EBITDA. Despite the increase, the indicator does not account for things such as interest or depreciation – pipes need periodic updates.
One positive aspect is the company's low debt level. Currently, the net debt to EBITDA ratio stands at 4.0, and management expects this figure to decrease to 3.8 by 2025.
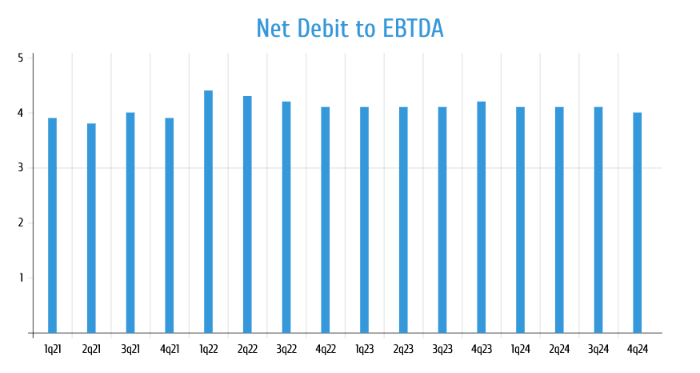
This indicates a stable financial position for Kinder Morgan.
However, the company’s valuation raises some concerns. The Price to DCF ratio has reached 12.6, while in the fourth quarter of 2023, it was 8.3.
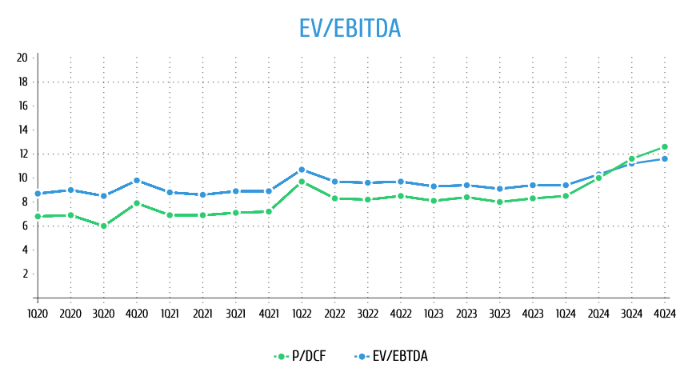
This sharp jump may be explained by expectations of increased oil and gas production as a result of political decisions by the new president, but it is important to remember that there have been no fundamental changes in the company’s business.
If you hold shares in this company, you may want to lock in profits, considering the current valuations and moderate growth prospects. Despite Kinder Morgan’s strong position in the market and expected growth in natural gas demand, the potential for further stock growth seems limited.
Become a member to receive more useful information. Thank you to everyone who shared the post on social media.
It is not an investment recommendation. Consult with a financial advisor before making investment decisions